
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Value Rating Upgrade Might Change The Case For Investing In Enel Stock (BIT:ENEL)
- Recent research commentary highlights Enel as a value-focused utility, with a forward P/E of 11.67 and valuation ratios below sector averages.
- The company’s A-rated value profile and comparatively low P/S ratio point to investors paying close attention to Enel’s earnings power relative to peers.
- We examine how Enel’s valuation metrics may influence its investment narrative for investors focused on earnings quality and pricing.
Compare Enel’s value profile with other potential underpriced opportunities by scanning our hand picked list of 172 high quality undervalued stocks across sectors that also prioritize earnings quality and disciplined pricing.
Enel Investment Narrative Recap
To own Enel, you need to be comfortable with a large, regulated utility that is leaning into renewables, digital grids, and electrification while still carrying meaningful debt and currency exposure. The big near term swing factor is execution on grid and renewable projects that are intended to support earnings quality even if demand in Italy and Spain stays flattish.
The most immediate risk sits in that funding and cash flow balance. Debt is not well covered by operating cash flow and profit margins have recently come down, so any regulatory hit in core European markets or fresh FX pressure in Latin America could tighten financial flexibility more than the valuation signal alone might suggest.
The recent focus on Enel’s forward P/E of 11.67 and its A-rated value profile is effectively a fresh look at the same operational story. You are being asked to weigh a lower earnings multiple and low P/S ratio against the realities of heavy capex, complex regulation, and slower forecast revenue growth of 3.5% a year.
That emphasis on valuation metrics is most relevant to the catalyst that matters most right now. It brings the spotlight back to whether Enel’s cost savings, grid digitalization and renewable expansion can support the 10.2% forecast earnings growth while the balance sheet still carries debt that is less than comfortably covered by operating cash flows.
Enel's analyst narrative points to revenues of €86.7b and earnings of €7.8b by 2029, built on forecast revenue growth of 3.6% a year and an earnings step up of about €4b from current earnings of €3.8b.
Uncover why Enel's fair value indicates a 13% potential upside to its current price that could narrow quickly.
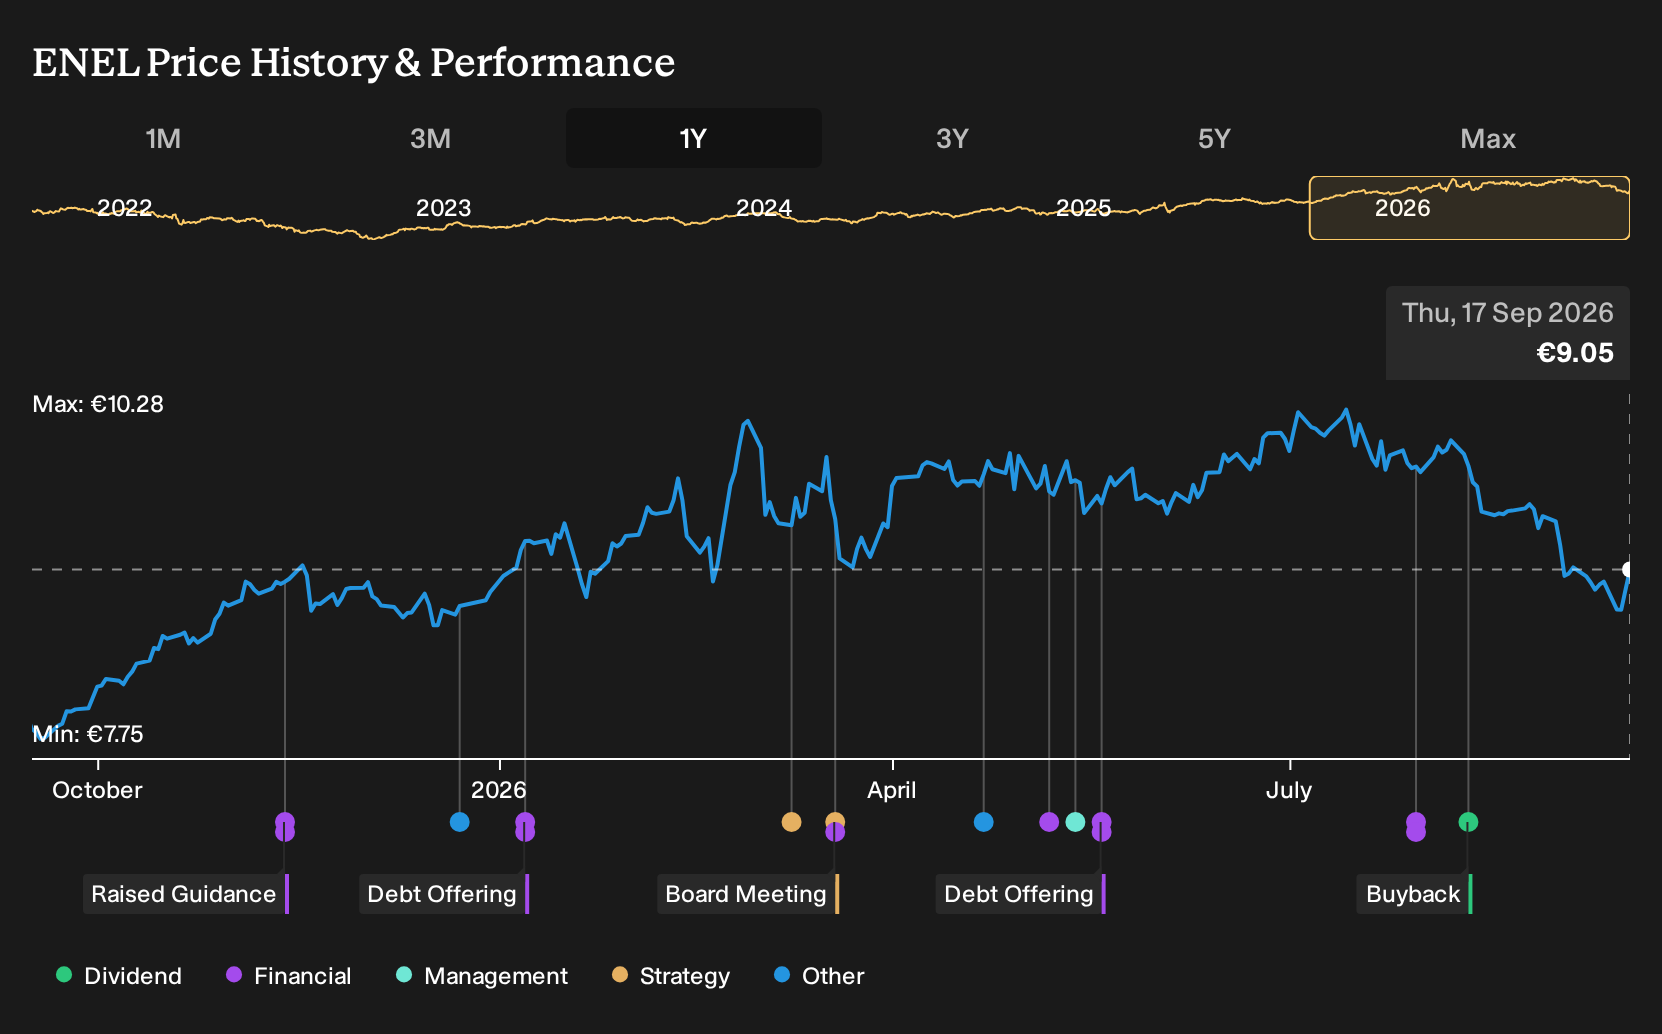
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly €10.22 to €32.84, so some retail investors see Enel as deeply underpriced while others are far more cautious. Set that against concentrated capex in Europe, FX risk in Latin America, and you get very different views on how Enel’s earnings profile might evolve. Explore those alternative perspectives before you decide how this story fits your portfolio.
Explore 2 other Enel fair value estimates, including one that suggests it could be worth just €10.22.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Enel research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Enel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Enel's overall financial health at a glance.
Looking for more investment ideas beyond Enel?
Once you have a view on Enel, it can help to line that opinion up against other opportunities with very different risk and return profiles so your portfolio is not leaning on a single story.
- For investors who want lower volatility and sturdier fundamentals at the portfolio level, scan a 104 resilient stocks with low risk scores that may help anchor returns when markets get choppy.
- If income is a priority and you want payouts backed by real cash generation, review a set of 159 dividend fortresses that combine higher yields with fundamental checks.
- For those hunting for under-followed opportunities with strong basics, sort through a 618 high quality undiscovered gems that can sit alongside a larger holding like Enel.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com