
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hudbay Minerals (TSX:HBM) Tracks Record Copper Prices, Is The Upside Already Priced In?
Hudbay Minerals (TSX:HBM) is back in focus after London Metal Exchange three month copper hit an intraday record of $14,694 per tonne on September 8, 2026, alongside weaker Chilean output.
Investors have been leaning back into copper producers, and Hudbay Minerals has ridden that interest with a 1 day share price return of 4.93% and a year to date share price gain of 34.17%. The 1 year total shareholder return of 100.12% and very large 3 and 5 year total shareholder returns suggest momentum has been strong over a longer horizon, even though the 90 day share price return declined 5.32%.
Spot other copper producers that could be reacting to the same supply squeeze by scanning our hand picked 29 top copper producer stocks.Hudbay Minerals has real copper exposure, real assets, and a big recent run. The harder question now is whether that strength is already fully priced in.
Most Popular Narrative: 13.8% Undervalued
Hudbay Minerals last closed at CA$37.03, while the most followed narrative pegs fair value closer to CA$42.94. As a result, the gap depends on how effectively copper growth projects translate into lasting free cash flow.
The partnership with Mitsubishi and enhanced Wheaton streaming arrangements provide Hudbay with financial flexibility, accelerated project timelines, and reduced up-front CapEx risk. This supports strong free cash flow and lowers the likelihood of equity dilution or excessive debt, all of which benefit future earnings per share.
See why 34 investors see Hudbay Minerals as 14% undervalued.
Result: Fair Value of CA$42.94 (UNDERVALUED)
Still, Hudbay Minerals leans heavily on a few large projects such as Copper World, and any permitting setbacks or cost overruns could quickly challenge this upside story.
Find out about the key risks to this Hudbay Minerals narrative.
Another View: What A Cash Flow Model Says About Hudbay Minerals
That 13.8% undervalued narrative is one story. A very different picture comes from the SWS DCF model, which puts Hudbay Minerals at a fair value of just CA$6.67 versus the current CA$37.03, implying the shares look expensive on that cash flow lens.
The gap between a CA$42.94 fair value based on earnings and multiples, and CA$6.67 based on future cash flows, is wide. It raises a simple question for investors: Which set of assumptions feels more realistic for a copper focused miner with big projects still to deliver?
Look into how the SWS DCF model arrives at its fair value.
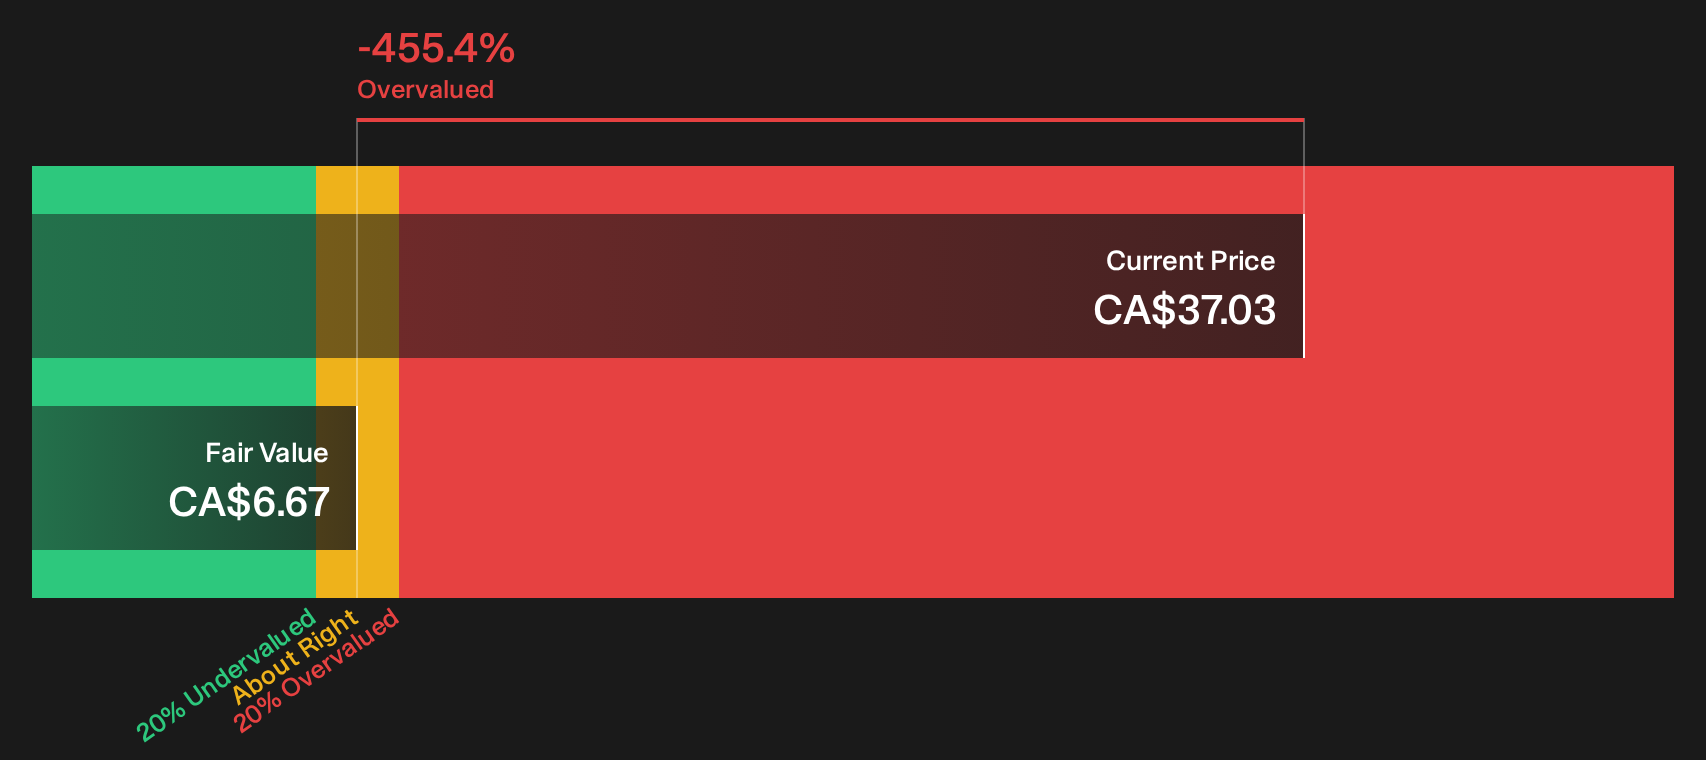
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hudbay Minerals for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals and a split view on Hudbay Minerals make this a good moment to move quickly, check the full data set, and stress test your own thesis against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Hudbay Minerals?
Do not stop with Hudbay Minerals alone. Use this copper story as a launchpad and line up a broader watchlist that fits your own risk and income goals.
- Target resilient returns by checking companies on the 1 resilient stocks with low risk scores that aim to keep volatility in check while still giving you meaningful exposure.
- Hunt for stronger balance sheets by scanning the list of solid balance sheet and fundamentals (7 results) to spotlight businesses built on healthier debt profiles and steadier fundamentals.
- Spot early stage opportunities by reviewing the 9 high quality undiscovered gems where smaller, less followed stocks might offer fresh angles for your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com