
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Amgen (AMGN)'s Shorter IMDELLTRA Monitoring Means For Shareholders
- Amgen reported that the FDA approved a significant update to IMDELLTRA's U.S. prescribing information, reducing the recommended monitoring after the first two infusions to 6 to 8 hours from roughly a full day, while keeping later cycle guidance and safety precautions intact.
- The shorter monitoring window directly affects real world treatment logistics by potentially easing capacity constraints for community oncology clinics, where most U.S. cancer patients receive care, and lowering practical barriers to IMDELLTRA use.
- This article reviews how Amgen's investment narrative is influenced by IMDELLTRA's reduced monitoring requirements and the advancing DeLLphi-305 program.
What Is Amgen's Investment Narrative?
To own Amgen you need to believe this is a durable therapeutics platform that can keep refreshing itself with new drugs while defending a broad portfolio. The IMDELLTRA label change and DeLLphi 305 data speak directly to that refresh. Shorter monitoring and first line potential do not automatically translate into revenue, but they do make it easier for community clinics to use the drug, which can matter for uptake and, over time, for how investors think about the oncology franchise.
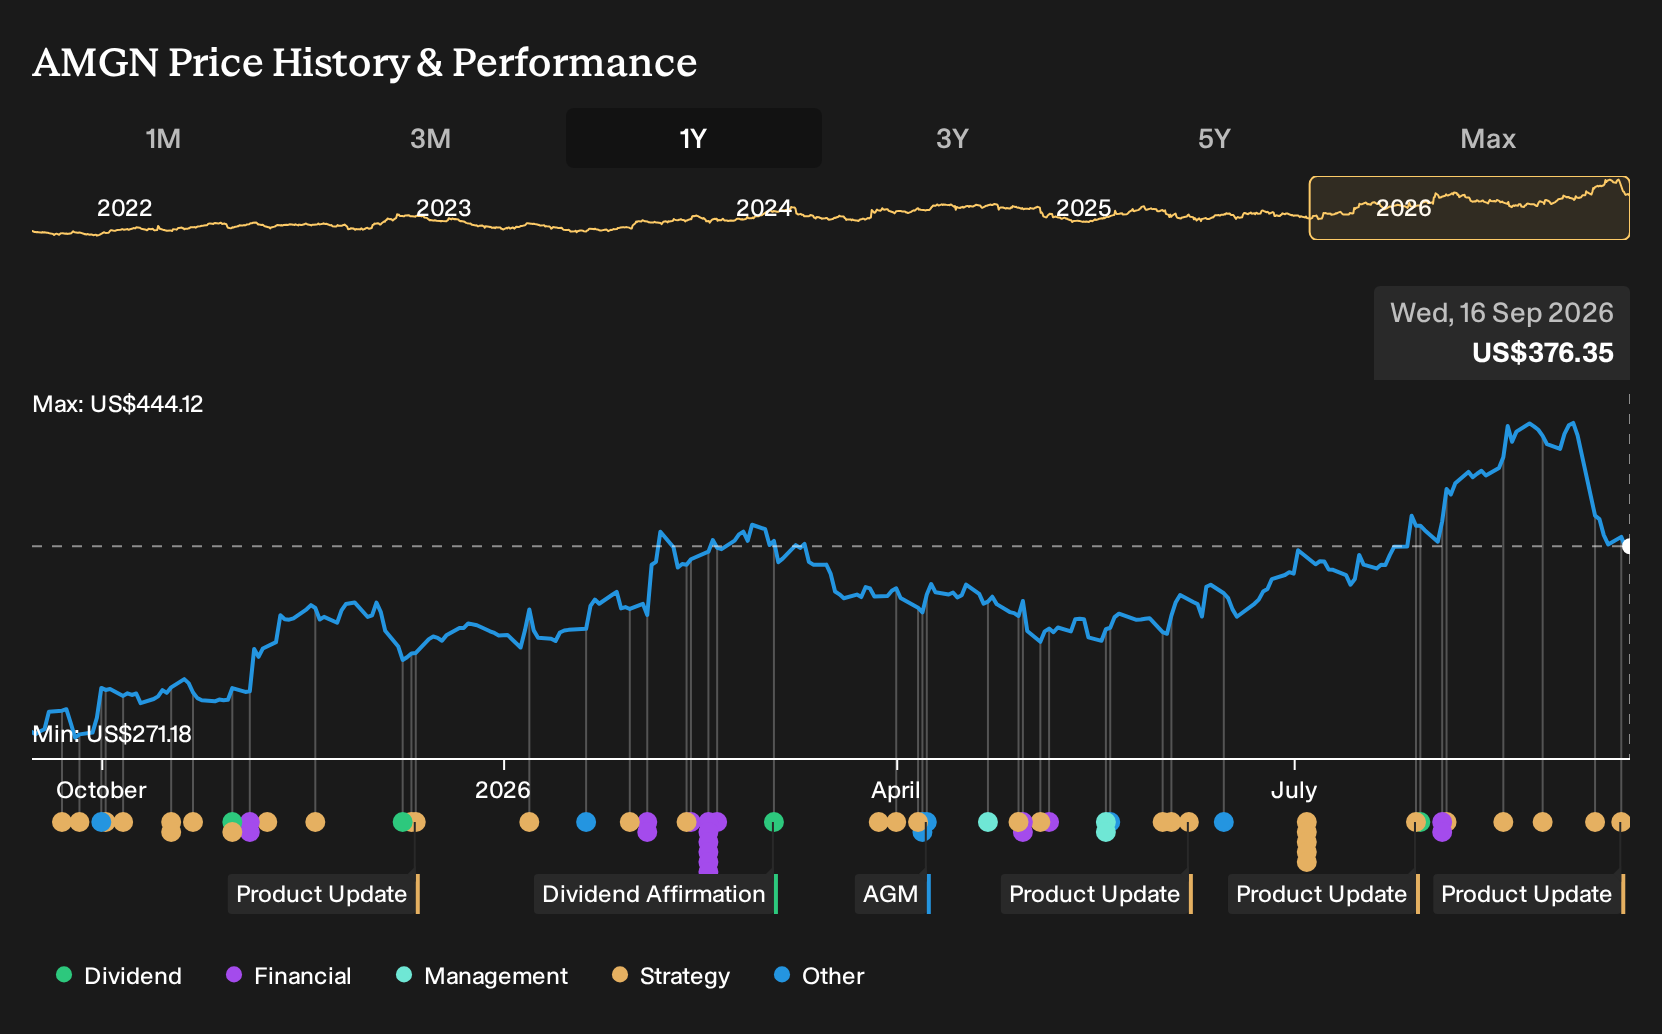
At the same time, the share price drop after the pelacarsen news shows how sensitive Amgen is to sentiment around key pipeline programs like olpasiran. You are dealing with a mature business that already generates US$38.1b of revenue and US$8.7b of net income, carries a high level of debt, pays a 2.65% dividend, and grows earnings at a pace that is solid rather than explosive. The near term story turns on execution in oncology and obesity, careful capital allocation, and how that debt profile flexes if one important assumption moves against management...
Even so, there is a specific pressure point in the story that rarely makes the headlines and that hinges on...
There's only one way to know the right time to buy, sell or hold Amgen. Head to Simply Wall St's company report for the latest analysis of Amgen's Fair Value.
Exploring Other Perspectives
One alternate view puts much more weight on Amgen’s older drugs and patent pressure. The lowest analysts were assuming revenue would sit near US$38.9b with earnings stuck around US$8.7b and a lower P/E by 2029. This represents a far more cautious script. You can treat the IMDELLTRA news as a fresh reason to reassess which camp you lean toward.
Explore 4 other Amgen fair value estimates, including one that suggests as much as 5% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Amgen research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amgen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amgen's overall financial health at a glance.
Looking For More Investment Ideas Beyond Amgen?
If IMDELLTRA and Amgen have sharpened your focus on quality and resilience, it can be useful to widen the lens and see how other businesses stack up on balance sheet strength, income potential, and risk. The Simply Wall St Screener can help you filter that broader universe into a short list that actually fits your approach.
- For investors who care most about financial resilience and cleaner balance sheets, start with a curated list of solid balance sheet and fundamentals (23 results) that share some of the sturdier traits often associated with larger pharma groups.
- If income is the priority and you want yields that work harder, scan a set of 6 dividend fortresses that aim to combine payout with staying power rather than just headline yield.
- When you prefer to hunt for quality that is less crowded, focus on 16 high quality undiscovered gems where solid fundamentals meet relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com