
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ON Semiconductor (ON) Unveils EPP And Subaru Tie Up, Is It 37% Below Fair Value?
ON Semiconductor (ON) is back in focus after unveiling its Embedded Power Platform and confirming a technology engagement with Subaru. Both moves link the stock directly to AI data centers and future electrified vehicles.
Recent trading tells a story of enthusiasm colliding with caution. ON Semiconductor’s share price has fallen about 44% over the past 90 days and is down 14% on a 30 day view, even though the year to date share price return is 20.46% and the 1 year total shareholder return is 31.78%. The longer 3 year total shareholder return is still in decline, while the 5 year total shareholder return is in positive territory.
The pullback accelerated after Investor Day updates and the initial EPP reveal, where ambitious long term targets and capital return plans met a reset in expectations around execution risk and timing. A 2.55% 1 day share price gain to US$68.30 as the Subaru engagement and Embedded Power Platform details were announced suggests that some investors now see the recent slide as pricing in more risk around ON Semiconductor’s AI and electrification roadmap than the business fundamentals alone would suggest.
Capitalize on the same AI and electrification themes driving interest in ON Semiconductor by scanning a curated 60 AI infrastructure stocks that could be setting up for the next major move.ON Semiconductor now sits between a sharp reset in expectations and a fresh AI and EV story taking shape. Does that mix justify stepping in at US$68.30, or does patience on price still look more appealing as the valuation picture comes into focus?
Most Popular Narrative: 37% Undervalued
ON Semiconductor’s most followed valuation story puts fair value at $107.68 against the last close of $68.30. The gap analysts are watching is wide and rooted in detailed long term assumptions about earnings, margins, and capital allocation.
The company's strategic investments in silicon carbide (SiC), wide bandgap technologies, and advanced power management solutions for both automotive and AI data centers position it at the forefront of key structural growth markets; as these high-value products ramp, they are expected to enhance margins and drive long-term earnings growth.
See why 118 investors see ON Semiconductor as 37% undervalued.
The narrative behind that $107.68 fair value uses a discount rate of 11.98% and leans heavily on analysts’ projections that earnings could grow meaningfully from $630.2m of profit on $6.2b of revenue. It also assumes ON Semiconductor can shift mix toward higher margin power and sensing products while managing risks around competition, manufacturing utilization, and exposure to cyclical auto and industrial demand.
On these numbers, the story hinges on whether the business can move from current net profit margins of 10.2% toward the 27.4% level analysts have in their models, while sustaining revenue growth that is forecast around the low double digits annually. The implied 21.7x future P/E in 2029 is below the current US Semiconductor industry average P/E of 45.9x used in the narrative, so the upside case rests more on earnings compounding than on multiple expansion.
Result: Fair Value of $107.68 (UNDERVALUED)
Still, ON Semiconductor’s story could be knocked off course if automotive demand softens further or manufacturing utilization stays low for longer than analysts expect.
Find out about the key risks to this ON Semiconductor narrative.
Another Take On ON Semiconductor’s Valuation
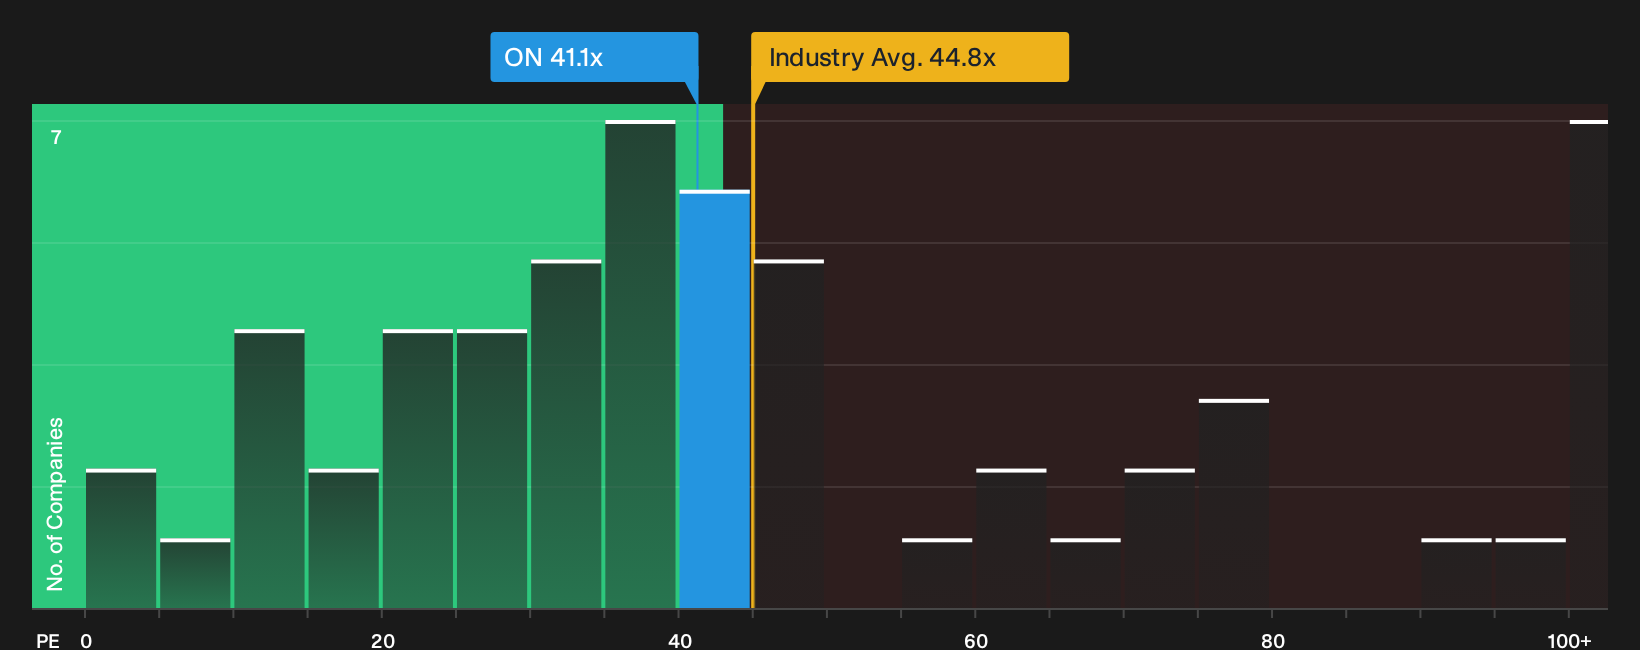
The first story says ON Semiconductor looks 37% undervalued, but the current P/E of 42.2x paints a more cautious picture. That ratio is slightly cheaper than the US Semiconductor industry at 44.8x and well below peers at 90.8x, yet still above the 38x fair ratio the regression points to.
In practical terms, you are paying more than the fair ratio suggests, even if the stock trades a little leaner than its sector and peer group. Is that extra premium a fair price for ON Semiconductor’s AI and EV ambitions, or a signal to demand a wider margin of safety at this stage?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading through all this optimism and caution around ON Semiconductor, it is clear the picture is mixed. Act quickly. Check the underlying data. Compare the upside with the issues on your radar, and weigh the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond ON Semiconductor?
If ON Semiconductor has your attention, do not stop there. Broader opportunity often sits in places you have not checked yet, and you do not want to miss them.
- Target potential upside by scanning a curated set of quality companies that look mispriced through the 29 high quality undervalued stocks.
- Seek more predictable income streams by focusing on businesses built to sustain payouts with the 6 dividend fortresses.
- Aim to reduce portfolio stress by concentrating on financially robust candidates through the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com