
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Strong Earnings Outlook Require Action From BBVA (BME:BBVA) Investors?
- Recent commentary on Banco Bilbao Vizcaya Argentaria highlights strong earnings growth expectations and positive estimate revisions, supported by cash flow strength and an outlook that points to capacity for business expansion.
- Valuation metrics such as forward P/E, P/B and P/CF sit below industry averages, which suggests BBVA’s operating progress is not fully reflected in current pricing.
- Next, the focus shifts to how Banco Bilbao Vizcaya Argentaria's earnings momentum and valuation profile may reshape its broader investment narrative.
Banco Bilbao Vizcaya Argentaria Investment Narrative Recap
To own Banco Bilbao Vizcaya Argentaria, you need to be comfortable with a large European bank whose earnings engine leans heavily on emerging markets and digital scale. The big positive story is about using its presence in Mexico, Turkey and South America, plus cost efficiency from technology, to keep earnings growing even as mature markets slow. The key near term catalyst is continued delivery on that earnings trajectory.
The biggest risk is that volatility in those same regions, or quicker pressure on interest margins in Spain and Mexico, eats into that earnings profile. The recent focus on strong growth metrics and positive estimate revisions supports the near term earnings story, but does not materially change currency, political or regulatory risk in BBVA's core markets.
The most relevant piece of recent commentary ties directly to BBVA's earnings outlook. Zacks highlights a top Growth Score and positive revisions to earnings estimates, pointing to expectations for stronger EPS this year and faster growth than the broader banking industry. That sits squarely on the same axis as the main short term catalyst, which is BBVA continuing to convert its footprint and digital push into higher profits.
For you, the practical question is whether that earnings profile adequately compensates for the risk mix. BBVA's exposure to Mexico and Turkey, the high but improving quality of its loan book, and its investment in digital banking all feed into whether those positive revisions can hold. If growth moderates, or emerging market stress bites harder, the current narrative around value and earnings momentum could be tested.
Banco Bilbao Vizcaya Argentaria is currently modeled to reach about €48.1 billion in revenue and €12.3 billion in earnings by 2029, based on analyst consensus. That path assumes revenue grows at roughly 12.1% per year and earnings rise by about €1.6 billion from current earnings of €10.7 billion.
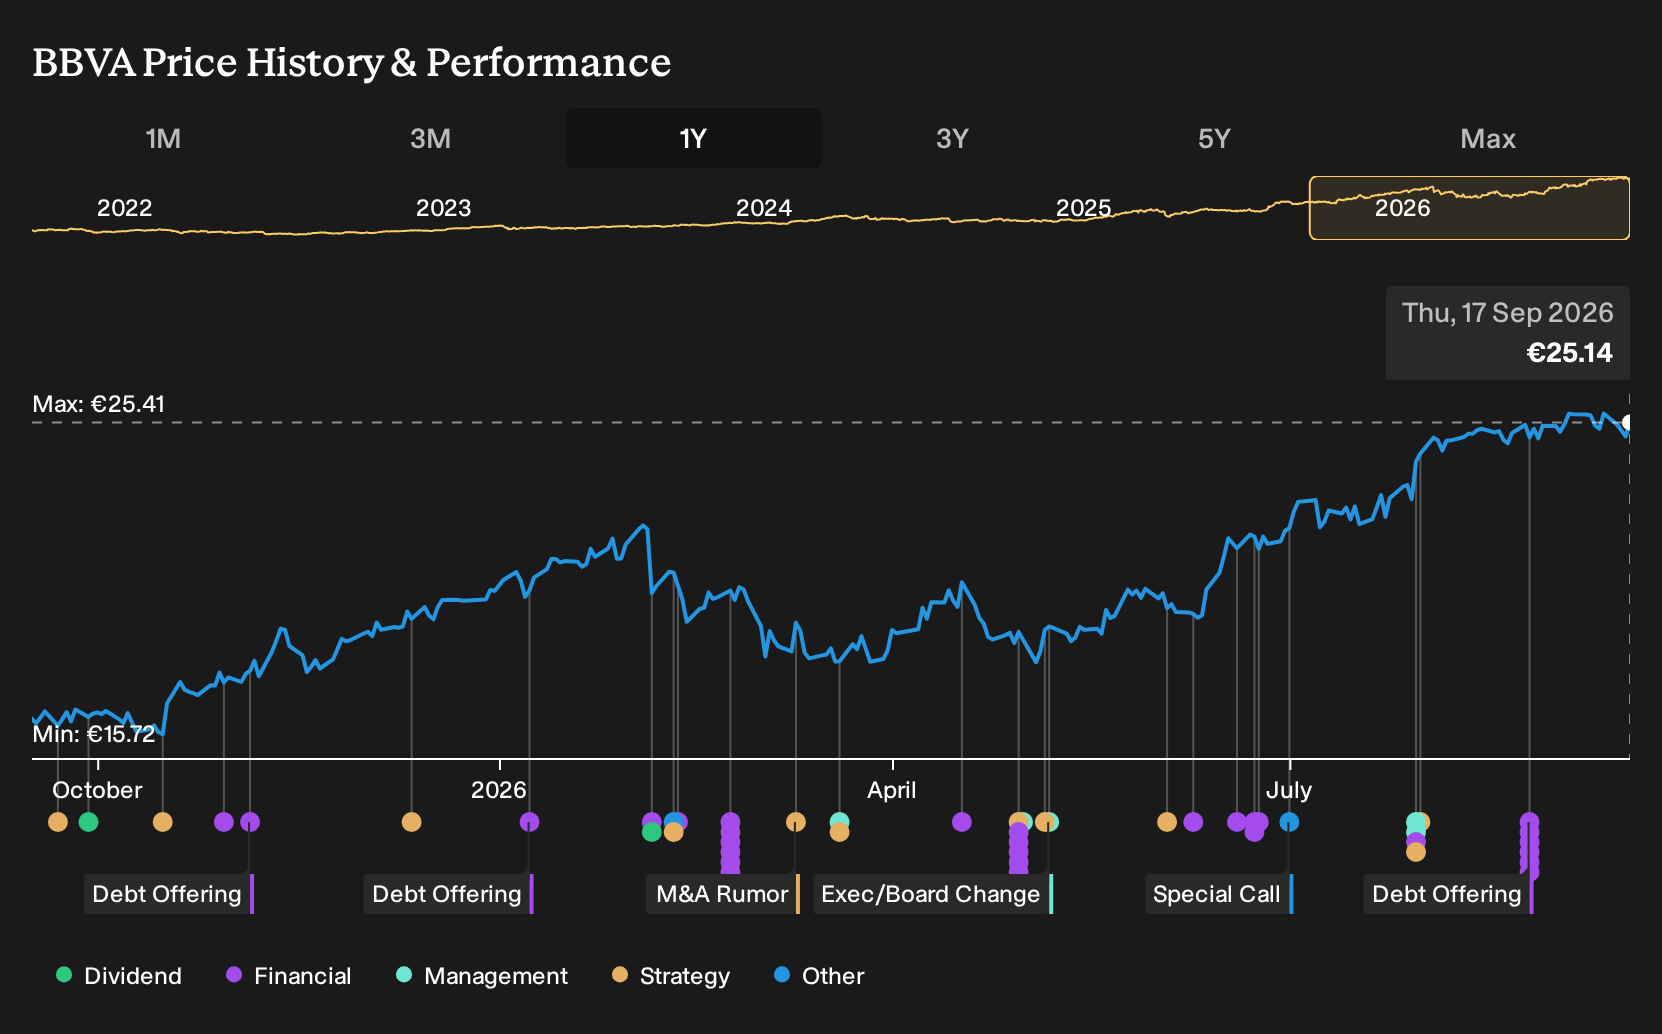
Uncover how Banco Bilbao Vizcaya Argentaria's fair value indicates a 9% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Banco Bilbao Vizcaya Argentaria's capital flexibility as the key catalyst. Before this news, the bullish camp was penciling in about €53.5b of revenue and €16.2b of earnings by 2029. That is far above consensus and could shift again once this latest information is fully absorbed.
Explore 4 other Banco Bilbao Vizcaya Argentaria fair value estimates, including one that suggests as much as 54% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Banco Bilbao Vizcaya Argentaria research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Banco Bilbao Vizcaya Argentaria. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Banco Bilbao Vizcaya Argentaria's overall financial health at a glance.
Looking For More Investment Ideas Beyond Banco Bilbao Vizcaya Argentaria?
If the Banco Bilbao Vizcaya Argentaria story has sharpened your thinking on earnings quality and valuation, it can help to benchmark it against other opportunities with different risk and return profiles.
- For investors who want potential upside without stretching on valuation, consider screening for companies with strong fundamentals using our 172 high quality undervalued stocks.
- If capital preservation and balance sheet strength matter most to you, narrow the field to businesses with low leverage and robust finances through a list of solid balance sheet and fundamentals (196 results).
- Those looking for opportunities the market may be overlooking can search for financially sound outliers with the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com