
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Did Green Fuel Supply Deals Just Shift IHI (TSE:7013) Stock Narrative?
- Brookfield Asset Management previously agreed to invest up to US$600 million in India’s ACME Cleantech Ventures to fund green ammonia and green methanol projects, with ACME already holding supply agreements with IHI Corporation for low carbon fuels.
- IHI’s role as an offtaker for ACME’s green fuels ties its clean energy ambitions to large scale project execution and long term infrastructure capital, rather than short term pilot activity.
- We will now examine how IHI's investment narrative could shift as it deepens long term supply commitments for green ammonia from ACME.
Scan other energy transition plays with contracted offtake momentum, such as IHI, by reviewing our hand picked 91 nuclear energy infrastructure stocks.
IHI Investment Narrative Recap
IHI appeals to investors who believe the aero engines and infrastructure businesses can keep generating healthy cash while the group gradually leans into cleaner fuels. The Brookfield funding into ACME does not change IHI’s near term engine and spare parts story, which still looks central to cash generation and reported profitability.
The key short term swing factor remains how long current civil aero spare parts demand stays strong before any downturn. The biggest risk is that earnings, which analysts already expect to soften over the next few years, compress faster than management can adjust costs and capital allocation across lower margin segments.
The ACME relationship links directly to IHI’s ambitions in low carbon fuels. Brookfield’s commitment of up to US$600 million into ACME gives that supplier more financial depth. This can help IHI treat green ammonia offtake as a credible operational pillar rather than an aspirational side project.
For catalysts, this matters most if IHI can convert long term fuel supply into repeatable infrastructure, engineering and service work while keeping a grip on risks in Power Systems and rising SG&A. Execution quality on these early green fuel projects will likely feed into how investors judge the durability of future cash flows.
IHI's narrative projects ¥2,099.8b revenue and ¥179.1b earnings by 2029. This assumes 7.7% yearly revenue growth and a ¥23.8b earnings decline from ¥202.9b today.
Discover how IHI's fair value indicates a 29% potential upside to its current price, a gap that could narrow as sentiment shifts.
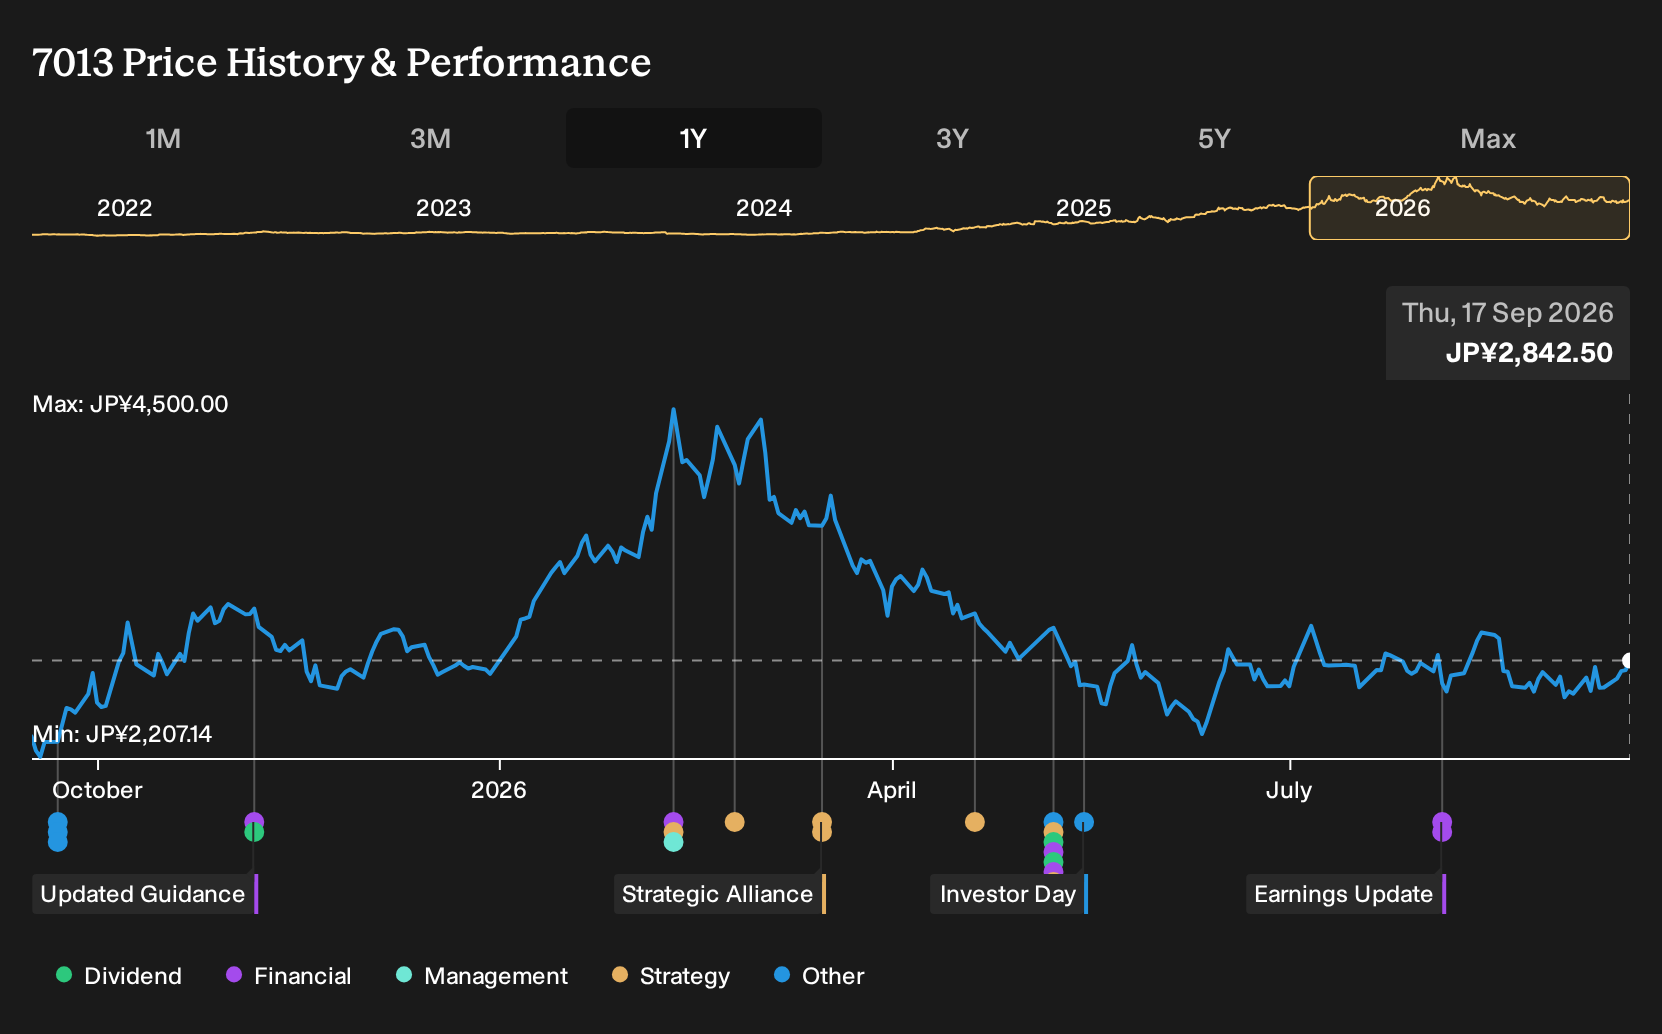
Exploring Other Perspectives
One alternate IHI story puts recurring aero spare parts in the spotlight as a long term growth engine, which contrasts with the baseline concern about a future downturn. The most optimistic analysts were already pencilling in ¥2,276.5b of revenue and ¥202.4b of earnings by 2029. Brookfield’s ACME funding could push those expectations in either direction.
Explore another IHI fair value estimate, including one that suggests there could be up to 29% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your IHI research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for IHI. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IHI's overall financial health at a glance.
Looking for more investment ideas beyond IHI?
If the IHI story has sharpened your thinking about risk, cash flow and long term themes, it can help to line it up against other opportunities using the Simply Wall St Screener.
- For investors who want income plus resilience, scan companies that meet a high yield threshold and have been tagged as potential 14 dividend fortresses.
- If capital preservation and steadier profiles matter most to you, narrow the field to businesses that appear on our 12 resilient stocks with low risk scores.
- When you want to move beyond the usual watchlist and surface lesser known opportunities with solid fundamentals, sort through the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com