
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Higher Interim Dividend Require Action From Wharf REIC Stock Investors?
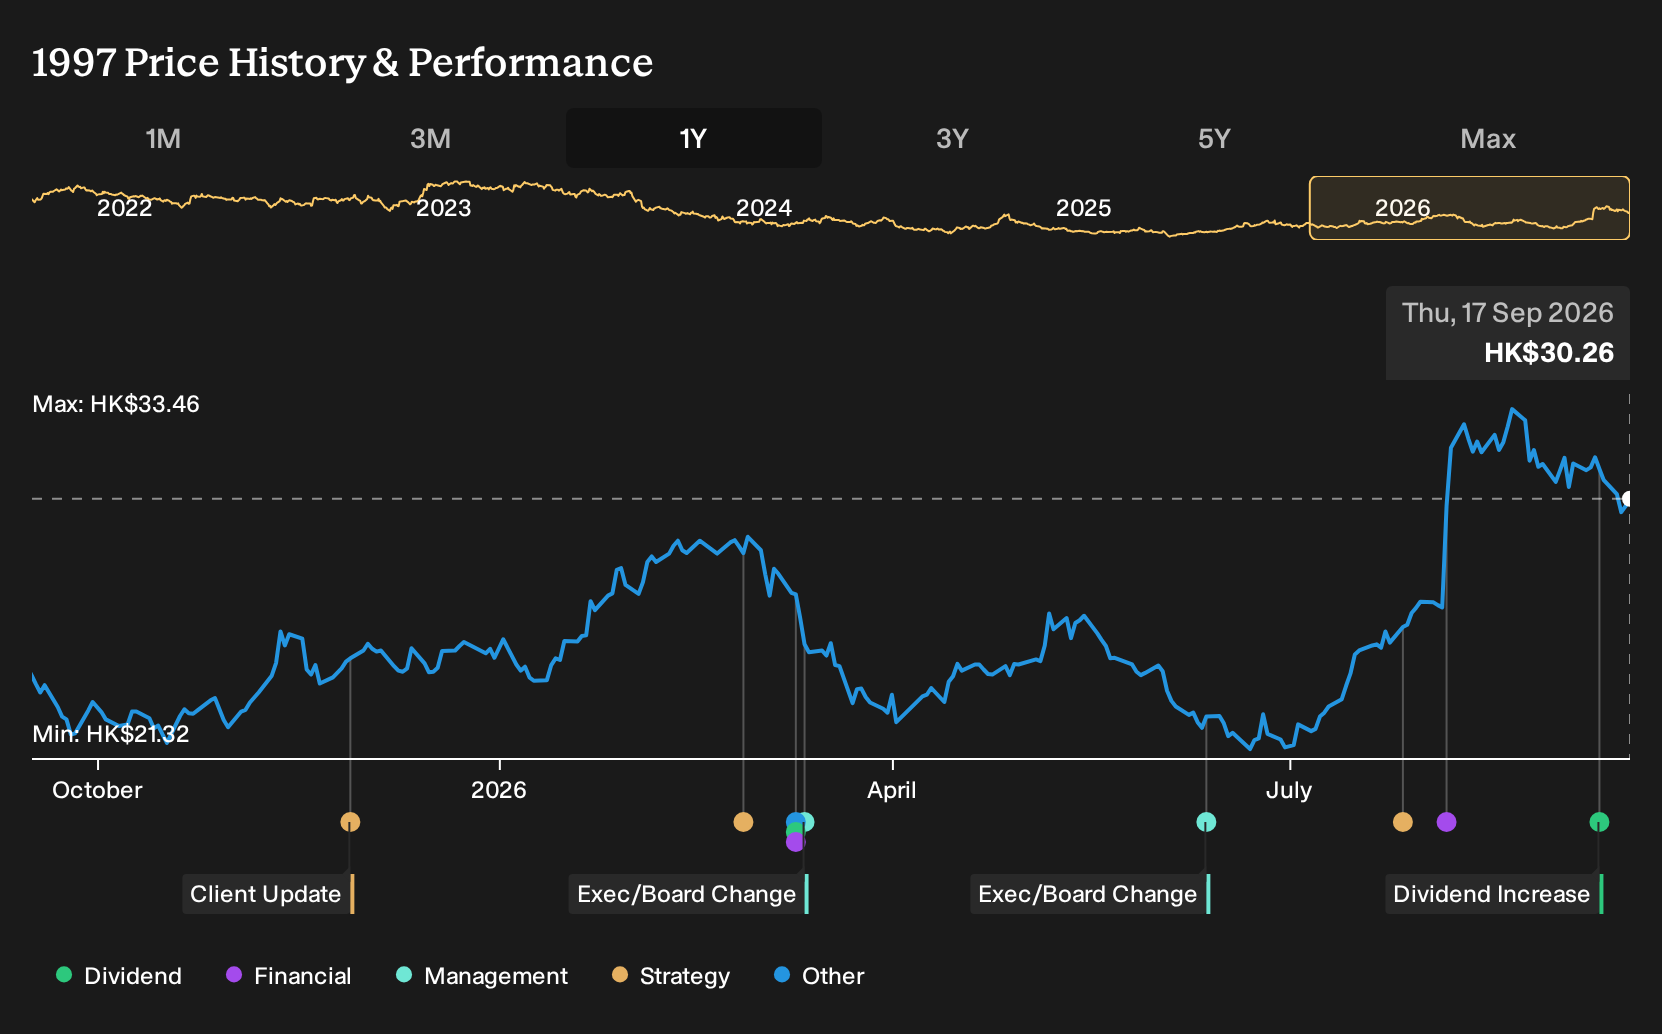
- Wharf Real Estate Investment Company Limited declared a first interim dividend of HK$0.94 per share, up from HK$0.66, with a HK$2.854b distribution paid on 10 September 2026, equal to 90% of underlying net profit from Hong Kong investment properties and hotels.
- The decision to return such a high share of underlying profit to investors highlights that Wharf Real Estate Investment is prioritising cash distribution from its core Hong Kong assets instead of retaining more earnings for reinvestment.
- It remains to be seen how Wharf Real Estate Investment's higher interim dividend payout might reshape the investment narrative investors have been using.
Scan how Wharf Real Estate Investment's latest payout compares with other high cash return opportunities by reviewing a hand-picked set of 160 dividend fortresses across the market.
Wharf Real Estate Investment Investment Narrative Recap
To own Wharf Real Estate Investment, you need to be comfortable with a Hong Kong focused landlord that leans heavily on prime retail, offices and hotels, while the sector works through what management has called a period of base building. The higher first interim dividend points to confidence in cash generation from core assets, but it does not change the reality that the group is still loss making and dependent on a gradual earnings rebuild.
The key near term swing factor remains how quickly tenant demand and tourism related spending translate into firmer occupancy and less negative rental reversions at Harbour City, Times Square and the hotel portfolio. The biggest risk is that Hong Kong retail and office conditions stay soft for longer. Combined with rising competition and ongoing capex needs, this could keep pressure on rent per square foot, margins and debt funded refurbishments even as more cash is released to shareholders.
The first interim dividend of HK$0.94 per share, equal to 90% of underlying net profit from Hong Kong investment properties and hotels, is the clearest recent signal relevant to this news. It ties the cash return story tightly to the performance of those flagship assets. It also comes at a time when analysts expect Wharf Real Estate Investment to move from losses to profitability over the next few years.
That link cuts both ways for you as a shareholder. A high payout ratio, on top of a dividend yield that independent data flags as not well covered by current earnings, can limit retained cash for large refurbishments of older hotels or further repositioning projects. If rental income or hotel profits soften again, management could face harder trade offs between sustaining dividends, funding upgrades and keeping leverage near the low gearing levels that many investors currently view as an important support for the investment case.
Wharf Real Estate Investment's narrative projects HK$13.5b revenue and HK$7.2b earnings by 2029. This projection is based on 1.8% yearly revenue growth and an earnings change of HK$9.2b from a loss of HK$2.0b today.
Uncover why Wharf Real Estate Investment's fair value indicates a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the dividend news against a different catalyst. They focus on Wharf Real Estate Investment riding a sharper luxury and tourism rebound than consensus, with earlier forecasts pointing to revenue of about HK$14.1b and earnings of roughly HK$8.4b by 2029. Those pre dividend views may shift, so compare several angles before deciding what fits your own expectations.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Wharf Real Estate Investment research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wharf Real Estate Investment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wharf Real Estate Investment's overall financial health at a glance.
Looking for more Wharf Real Estate Investment style ideas?
If the Wharf Real Estate Investment story has sharpened your focus on income, resilience and upside potential, it can help to line it up against other opportunities using the Simply Wall St Screener.
- For investors who care most about durable balance sheets and steady fundamentals, start with a list of solid balance sheet and fundamentals (194 results) that can handle tougher conditions without overstretching.
- If you want income while still keeping an eye on quality, scan a curated 160 dividend fortresses that may better match your risk and payout preferences.
- For those hunting for future leaders before they are widely followed, sort through a 618 high quality undiscovered gems that combines strong fundamentals with room to grow.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com