
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hitachi (TSE:6501) Following Its Grid And Data Center Push Looks Undervalued
Why Hitachi’s latest grid and data center moves matter for shareholders
Hitachi (TSE:6501) has put critical infrastructure front and center with a planned US$528m transformer plant in Mississippi and a fresh data center partnership that together sharpen its focus on power and AI demand.
Recent price action suggests investors are warming to this story. Hitachi’s share price return is up 5.65% over the past week and 14.92% over 90 days, while the 1 year total shareholder return of 40.01% and 5 year total shareholder return of 368.77% indicate strong longer term momentum in its grid and data center push.
Scan other grid and AI infrastructure plays that are riding similar demand trends with our hand-picked 37 power grid technology and infrastructure stocks for context alongside Hitachi’s latest moves.
Hitachi now appears to be a clear beneficiary of grid and AI build out. A harder question is whether a ¥5,475 share price already captures that strength or still leaves room based on today’s fundamentals.
Most Popular Narrative: 24% Undervalued
On the most followed view, Hitachi’s fair value sits at ¥7,200, which is well above the last close of ¥5,475. This frames the current transformer and data center story as under-priced by that narrative.
Strong demand for power grid equipment, including large HVDC projects in Europe and a sector order backlog above JPY 10 trillion, supports a multiyear buildout of transmission capacity that can lift revenue and support higher adjusted EBITDA and net margins in Energy.
See why 1 investors see Hitachi as 24% undervalued.
Result: Fair Value of ¥7,200 (UNDERVALUED)
Still, the bullish Hitachi narrative leans heavily on a grid backlog of more than ¥10t and ambitious AI productivity targets that could disappoint if execution or demand softens.
Find out about the key risks to this Hitachi narrative.
Another view on Hitachi’s valuation
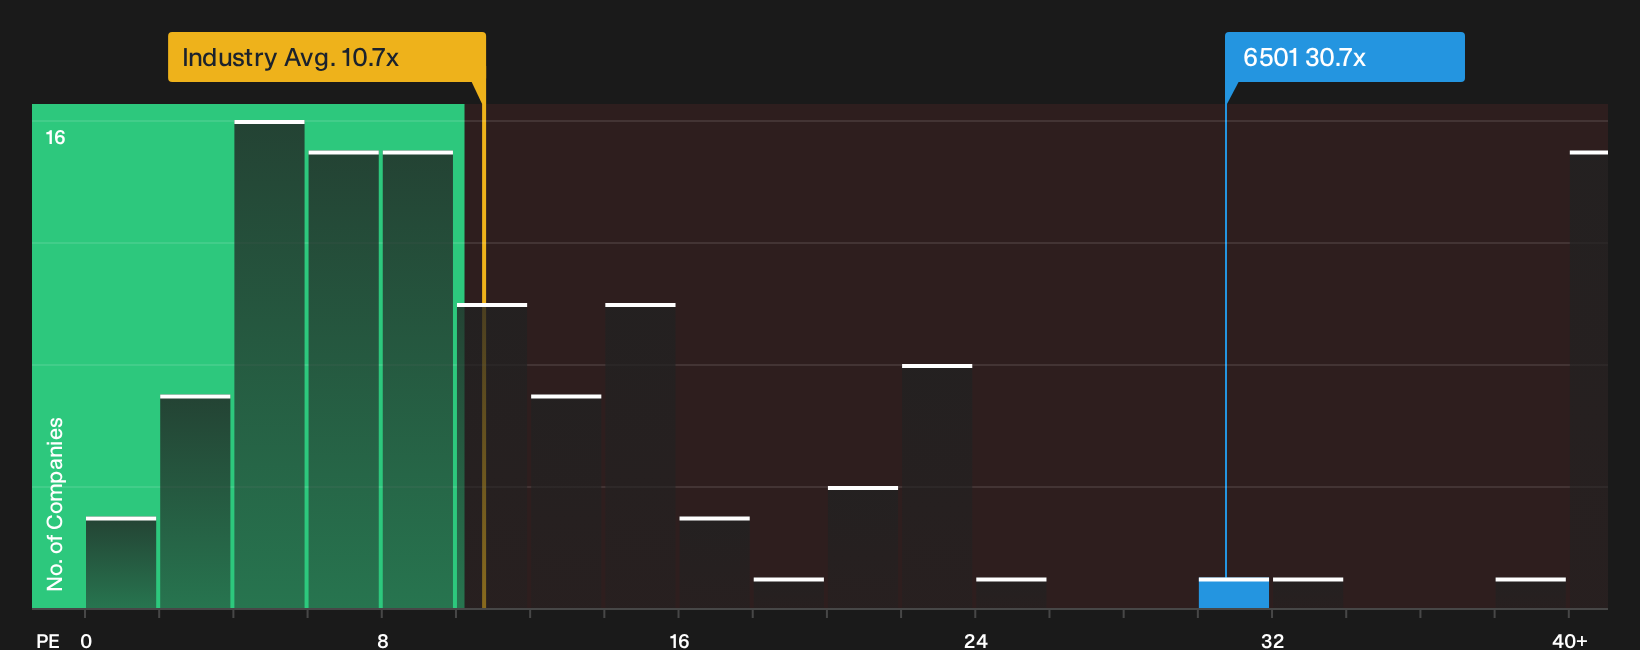
The bullish narrative paints Hitachi as 24% undervalued, yet the market is already paying a P/E of 30.7x. That is much richer than both peers at 12.4x and the Asian Industrials group at 10.7x, and even slightly below a fair ratio of 33.1x. This points to real valuation risk if expectations cool.
For a closer look at what this gap could mean in practice over time, study the full valuation breakdown, including how earnings quality and growth forecasts feed into that fair ratio, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this all sounds optimistic on Hitachi, treat it as a starting point rather than a verdict and pressure test the numbers yourself. To see the specific positives that have investors interested right now, review the 3 key rewards.
Looking for more investment ideas beyond Hitachi?
If Hitachi has sharpened your interest in long term themes, broaden your watchlist with a few focused screens that surface different types of opportunities.
- Target dependable income by reviewing companies in the 14 dividend fortresses that may suit a yield focused portfolio.
- Hunt for mispriced potential with the 17 high quality undervalued stocks that highlights businesses where fundamentals and market price appear out of sync.
- Prioritise capital preservation first by scanning the 12 resilient stocks with low risk scores that filters for resilience when conditions change fast.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com