
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Regeneron Pharmaceuticals Stock (REGN) Trial Disclosure Lawsuits
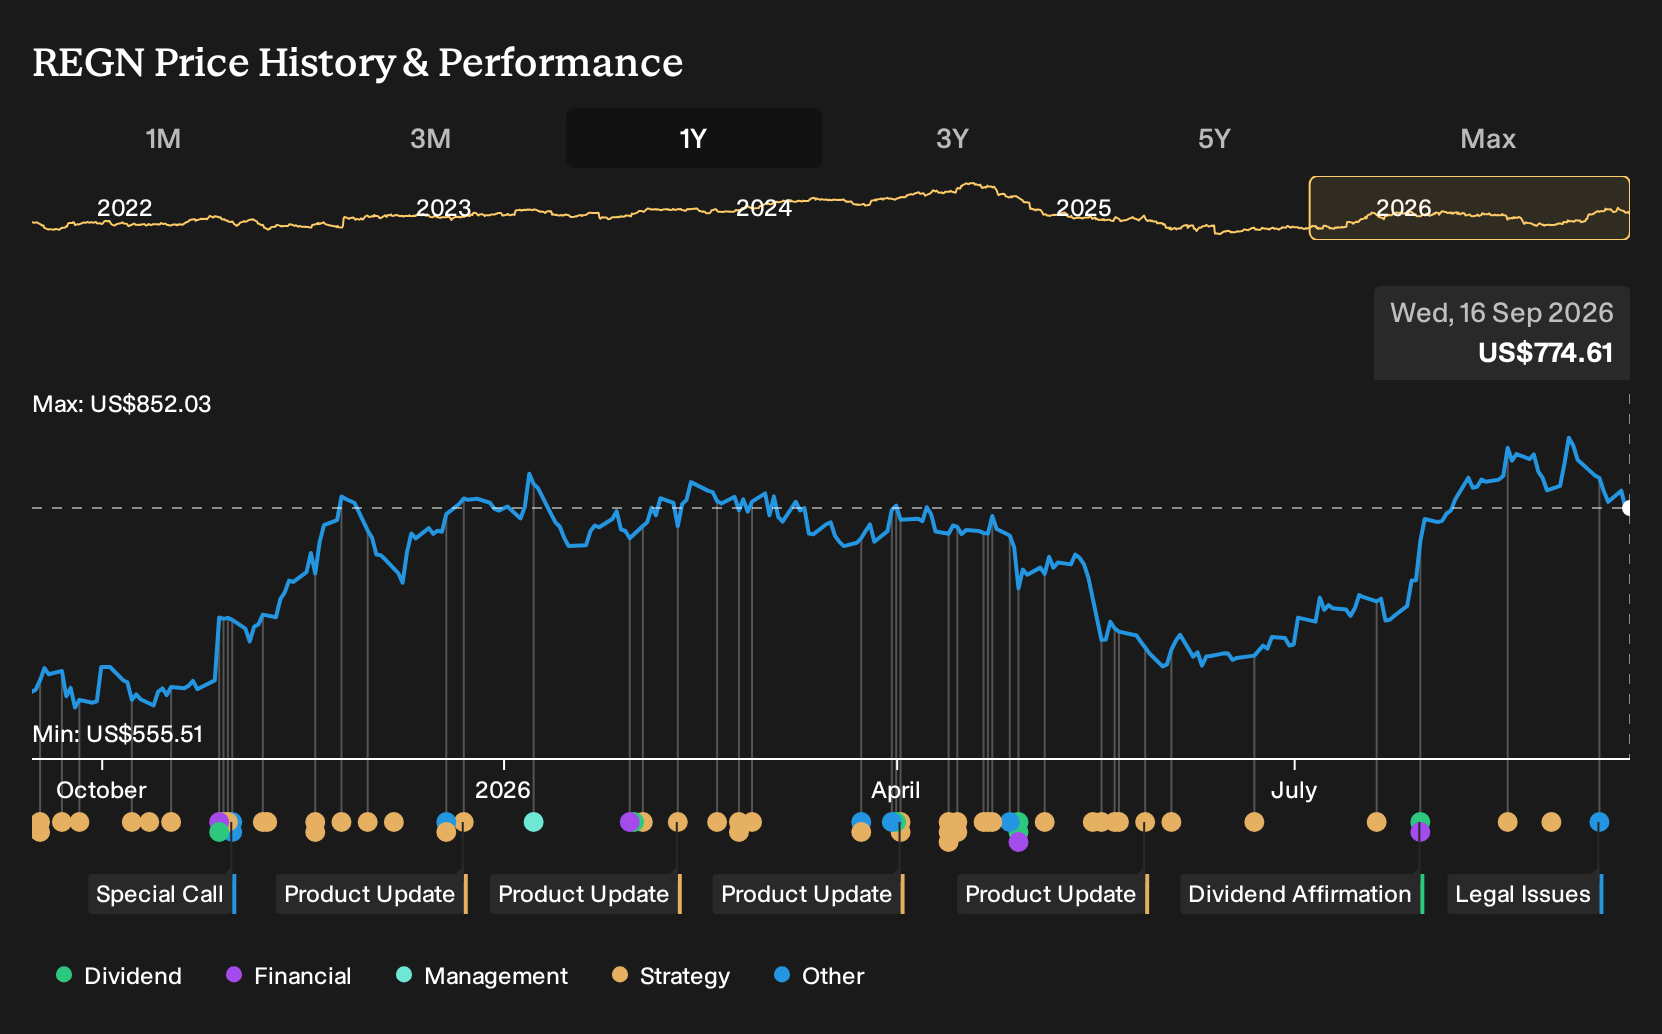
- Regeneron Pharmaceuticals is facing federal securities class action lawsuits filed in September 2026 that allege misleading disclosures about the Phase III Fianlimab Libtayo oncology trial's design assumptions and clinical prospects.
- The litigation highlights operational pressure around clinical trial design, statistical rigor, and disclosure controls, which exist alongside ongoing dependence on Dupixent and EYLEA for commercial scale.
- We will examine how Regeneron Pharmaceuticals' investment narrative is affected by these securities lawsuits over Fianlimab Libtayo trial disclosures.
Regeneron Pharmaceuticals Investment Narrative Recap
To own Regeneron Pharmaceuticals, you need to be comfortable with a story that still leans on Dupixent and EYLEA while management spends heavily to build the next wave of medicines. The securities lawsuits around Fianlimab Libtayo sit alongside that, adding legal and reputational noise but not changing the near term operational focus on immunology and retinal franchises.
The biggest swing factor near term remains how well Regeneron Pharmaceuticals offsets pressure on the EYLEA family through EYLEA HD uptake and Dupixent growth. The largest risk is erosion in retinal revenue from competition and pricing. The new litigation mainly intensifies scrutiny of trial design and disclosure, which could complicate oncology execution rather than headline cash generation.
The DPHARM presentation on September 16 matters because it puts Regeneron Pharmaceuticals in front of a clinically sophisticated audience just as Fianlimab Libtayo disclosures are under legal review. Investors can watch for detail on how management talks about statistical assumptions, data quality, and governance around future studies.
Conference appearances like DPHARM do not change trial outcomes, but they show how the business communicates around risk, pipeline productivity, and use of its growing R&D budget. For a story that already hinges on replacing concentrated EYLEA cash flows with a broader set of programs, that communication thread is part of the catalyst and part of the risk.
Regeneron Pharmaceuticals' current earnings are about US$4.4b, with analyst consensus pointing to US$6.0b in profit and US$19.4b in revenue by 2029. Based on these figures, this outlook implies revenue growth of 9.2% per year and an earnings increase of roughly US$1.6b from today's level.
Uncover why Regeneron Pharmaceuticals' fair value indicates an 8% potential upside to its current price before it closes for Regeneron Pharmaceuticals investors.
Exploring Other Perspectives
One alternate view on Regeneron Pharmaceuticals leans heavily on pricing pressure as the key risk, not just product concentration. In that storyline, the lowest analysts were already penciling in slower revenue growth of 5.7% a year and earnings of about US$5.6b by 2029. With the lawsuits and DPHARM update now in play, those forecasts may be revisited. Treat them as starting points and compare several viewpoints before you decide how to frame the story for yourself.
Explore 5 other Regeneron Pharmaceuticals fair value estimates, including one that suggests as much as 6% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Regeneron Pharmaceuticals research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Regeneron Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Regeneron Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Regeneron Pharmaceuticals?
If the Regeneron Pharmaceuticals story has you thinking about risk concentration, legal overhangs, and product durability, it can help to line it up against other businesses with different strengths and balance sheet profiles. The Simply Wall St Screener lets you filter for exactly the type of opportunities that fit your preferred mix of quality, resilience, and income potential.
- For investors who want potential upside without stretching on quality, consider a basket of resilient companies with stronger risk profiles using the 11 resilient stocks with low risk scores.
- If you are hunting for a stronger margin of safety, check out a curated group of companies trading below their estimated worth through the 33 high quality undervalued stocks.
- Income focused investors can look for steadier cash distribution by scanning a set of higher yielding payers through the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com