
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Western Digital (WDC) Pullback Following Fed Rate Move Puts Valuation Back In Focus
Western Digital (WDC) moved after the Federal Reserve lifted rates by 25 basis points, and chip stocks responded to stronger sentiment around AI infrastructure demand and Intel’s talks with SK Hynix on US memory production.
Western Digital’s recent slide, including a 7 day share price return that declined 13.54% and a 30 day drop of 22.21%, comes after earlier AI related enthusiasm and news around convertible note redemption. The stock still carries a very large 1 year total shareholder return and more than 10x total shareholder return over 3 years, indicating strong long term momentum even as short term sentiment cools.
Scan how other AI infrastructure players are reacting to the same rate move and storage theme by checking the hand picked 60 AI infrastructure stocks alongside Western Digital.
Western Digital has moved from sharp gains to a steep pullback, yet still shows very strong multi year returns and a sizable gap relative to analyst targets. With valuation coming into focus, the key question is whether current buyers continue to hold the advantage in this trade.
Most Popular Narrative: 26% Overvalued
Western Digital trades at a last close of $416.97 against a narrative fair value of $329.76, which frames the recent pullback as a repricing of very rich expectations rather than a complete reset.
The AI storage demand is real and probably durable. The question is not whether the drives get bought, but for how long the two companies making them choose discipline over market share. Almost everything in the valuation flows from that one decision, made quarter after quarter, by people whose incentives can change.
See why 36 investors see Western Digital as 26% overvalued.
Result: Fair Value of $329.76 (OVERVALUED)
Still, Western Digital’s story can unravel quickly if AI capex cools faster than expected or if new capacity and Chinese storage supply start to bite into pricing power.
Find out about the key risks to this Western Digital narrative.
Another View: Western Digital Through The P/E Lens
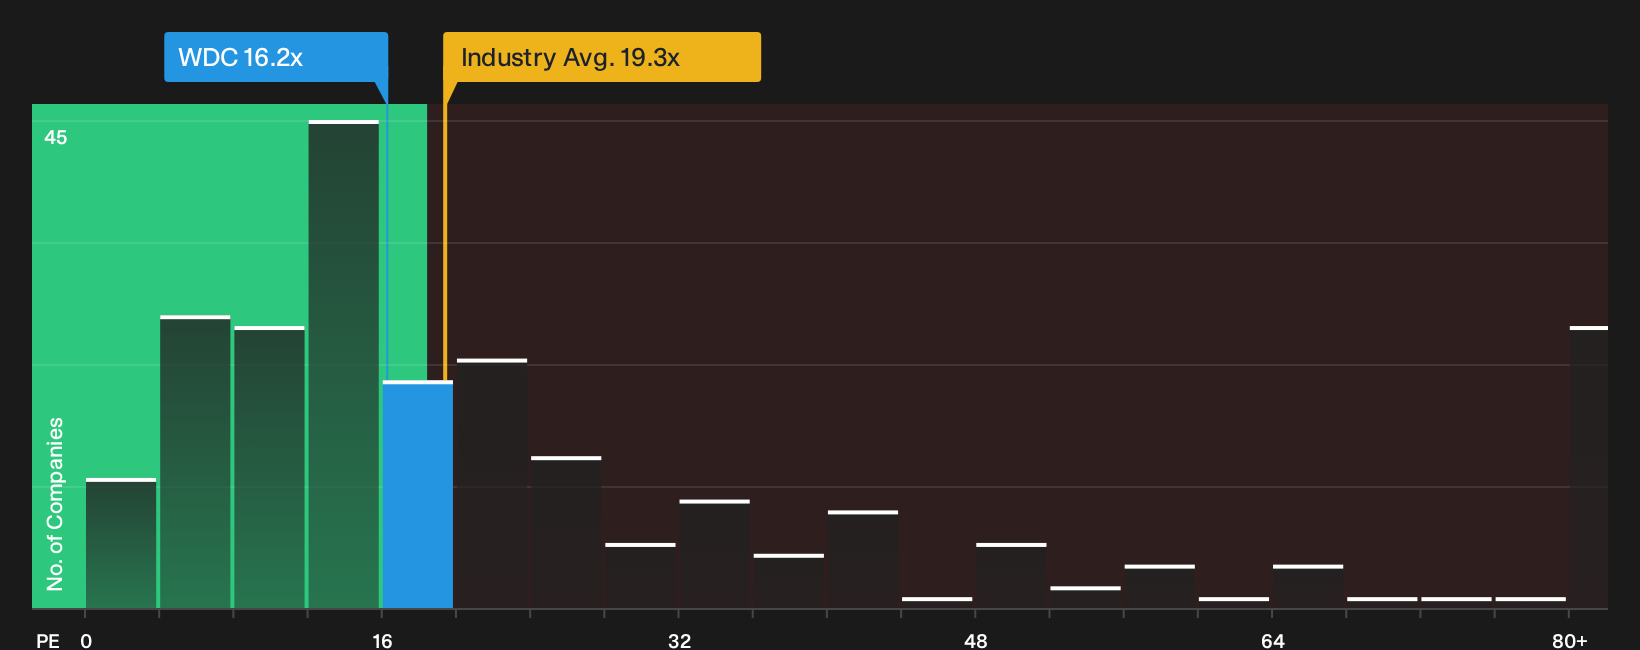
There is a sharp contrast when the Western Digital story is evaluated using earnings multiples instead of narrative fair value. At a P/E of 16.2x, the stock trades well below the global tech industry on 19.3x and peers on 33.8x, while the fair ratio is listed at 45.7x.
That gap suggests the market already prices in a margin of safety around future profitability, following Western Digital’s strong 1 year and multi year returns. The key question is whether that discount reflects real risk related to AI storage and industry cycles, or whether it leaves room for sentiment to move closer to the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling torn between Western Digital’s strong multiyear returns and the recent pullback narrative is normal, so act quickly on the data and stress test your own view using the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Western Digital?
Western Digital gives you one data point. Build a stronger watchlist by lining it up against other ideas filtered for quality, value, and resilience.
- Target potential mispricing by scanning a curated pool of companies screened for value and quality through the 33 high quality undervalued stocks.
- Protect your downside first by focusing on financially resilient businesses highlighted in the 11 resilient stocks with low risk scores.
- Get ahead of the crowd by reviewing financially sound outliers surfaced in the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com