
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is C.H. Robinson Worldwide (CHRW) A Bargain As Valuation Questions Grow?
C.H. Robinson Worldwide (CHRW) continues to draw attention after recent share price moves, with the stock closing at US$153.47 on 17 September 2026. Investors are weighing logistics exposure against performance across transportation and freight brokerage.
Recent trading has been choppy, with the share price falling 2.64% over the last session but rising 6.00% over the past month. Over the longer term, C.H. Robinson Worldwide has produced a 15.34% 1-year total shareholder return and very large 3 and 5-year total shareholder returns near a doubling. This suggests that shorter term price momentum is fading even as long term holders have been strongly rewarded.
Scan logistics peers showing similar momentum shifts using our hand picked list of 33 high quality undervalued stocks.The recent jump in C.H. Robinson Worldwide now highlights a wide gap between the US$153.47 share price and valuation estimates that reach up toward analyst targets. Where does a fair value line actually fall within that range?
Most Popular Narrative: 22% Undervalued
Based on the most followed narrative, C.H. Robinson Worldwide is framed as undervalued, with a fair value estimate of $197.04 against the recent $153.47 close, which puts the focus firmly on how its freight platform might compound efficiency gains over time.
The increasing complexity of global supply chains, driven by tariff volatility and trade uncertainties, is elevating customer demand for integrated, data-rich solutions, areas where C.H. Robinson is investing and expanding, resulting in strong customer retention and a more resilient recurring revenue base.
See why 6 investors see C.H. Robinson Worldwide as 22% undervalued.
Result: Fair Value of $197.04 (UNDERVALUED)
Still, C.H. Robinson Worldwide faces two clear swing factors: tougher trade policy shifts that could squeeze high margin customs revenue, and faster tech adoption by smaller brokers that narrows its AI edge.
Find out about the key risks to this C.H. Robinson Worldwide narrative.
Another View: What C.H. Robinson Worldwide’s P/E Is Telling You
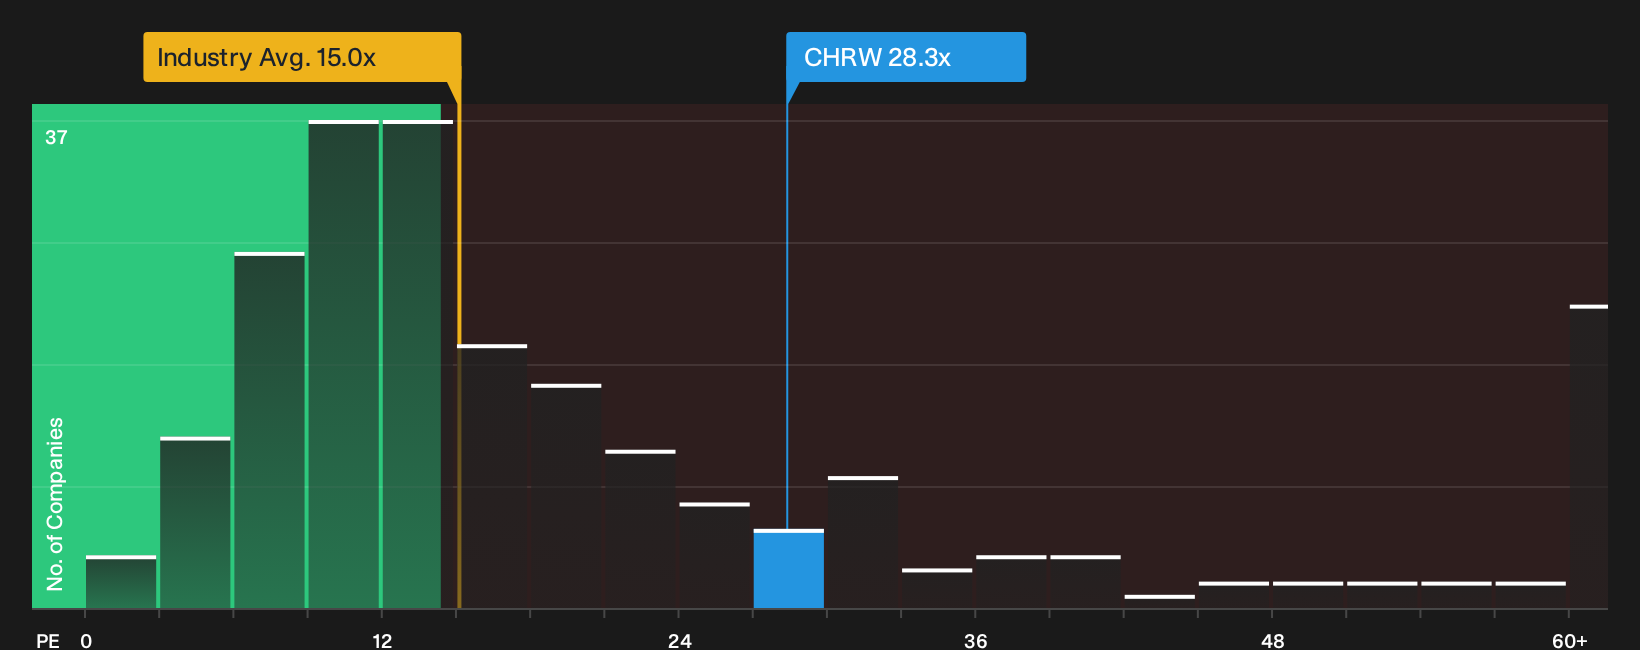
The analyst narrative presents C.H. Robinson Worldwide as 22% undervalued against a US$197.04 fair value, yet the market is already paying a P/E of 28.3x. That is far above both the fair ratio of 18.7x and peer averages near 17.8x to 15.1x, which points to potential valuation risk if expectations reset.
For anyone weighing that richer multiple against the bullish story on AI productivity and margins, it may be useful to consider which side of the argument you find more compelling and how much premium you are willing to pay for it.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of optimism and concern sit side by side in the C.H. Robinson Worldwide story right now, so move quickly, review the details, and weigh both sides by checking the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond C.H. Robinson Worldwide?
If C.H. Robinson Worldwide has you thinking more broadly about opportunities, do not stop here. The market rarely waits for investors who hesitate too long.
- Target higher potential upside by scanning the 11 elite penny stocks with strong financials that pair small size with stronger balance sheets than many expect in this corner of the market.
- Sharpen your value focus by checking the 16 high quality undiscovered gems that combine quality fundamentals with lower visibility and less crowded trade setups.
- Dial down portfolio volatility by reviewing the 11 resilient stocks with low risk scores that score well on resilience while still offering room for upside.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com