
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Vitkac Addition Altering The Investment Case For Prada (SEHK:1913)?
- Vitkac Sp z o o recently added Prada S.p.A. to its curated luxury portfolio, placing the Italian fashion house alongside brands such as Miu Miu, Balenciaga, Fendi, Valentino and Givenchy across clothing, footwear, bags and accessories.
- This partnership gives Prada another curated European distribution channel that focuses on selection rather than scale, which may deepen engagement with high-intent luxury shoppers on Vitkac’s international platform.
- We will now explore how Prada’s inclusion in Vitkac’s tightly curated portfolio could influence the broader investment narrative around the brand.
Prada Investment Narrative Recap
To own Prada, you need to believe the group can keep translating brand heat into consistent earnings, even as tourism, currencies and regional demand move around. The Vitkac deal fits that story at the margin. It supports the push into curated wholesale and high-intent online shoppers, but it is unlikely to change the near term earnings path on its own.
The near term swing factor still sits in execution around product, retail culture and digital reach, while cost inflation and heavier investment pressure margins. The biggest risk right now is that spending on marketing, stores and technology runs ahead of sales momentum, which could dilute net margins if demand softens in key regions.
Among recent developments, Prada ruling out a takeover attempt for Armani and keeping focus on integrating Versace looks most relevant when you think about catalysts. Management is concentrating on cost efficiencies, synergies and improving Versace operations instead of adding another large label, which keeps balance sheet and execution risk more contained.
For you, that matters more than the Vitkac announcement, because Versace integration, store refurbishments such as the expanded Galleria Vittorio Emanuele space and ongoing retail investment are closer to the core earnings story. These moves tie directly into the main upside drivers analysts flag, but they also magnify the risk that higher operating expenses outpace revenue progress.
What The Prada Consensus Is Really Pricing In
Prada's story in the analysts' models is less about the Vitkac partnership and more about what the next few years of revenue and profit delivery might look like if the current playbook holds.
Consensus forecasts assume Prada can grow revenue by 6.7% each year over the next three years while gradually lifting profit margins from 13.2% today to 13.5% by 2029. Earnings are projected to move from €792.9 million now to €987.7 million in that same year, with some analysts pencilling in as much as €1.1b if things skew more positively.
Those earnings expectations feed straight into the P/E math that underpins current price targets. To line up with the central analyst view, you would need to accept Prada on a 19.8x P/E against the 2029 earnings estimate, compared with about 14.5x today and a reported 9.3x for the wider Hong Kong luxury peer group.
Prada's narrative projects €7.3b revenue and €987.7 million earnings by 2029. This assumes 6.7% yearly revenue growth and an earnings increase of about €195 million from €792.9 million today.
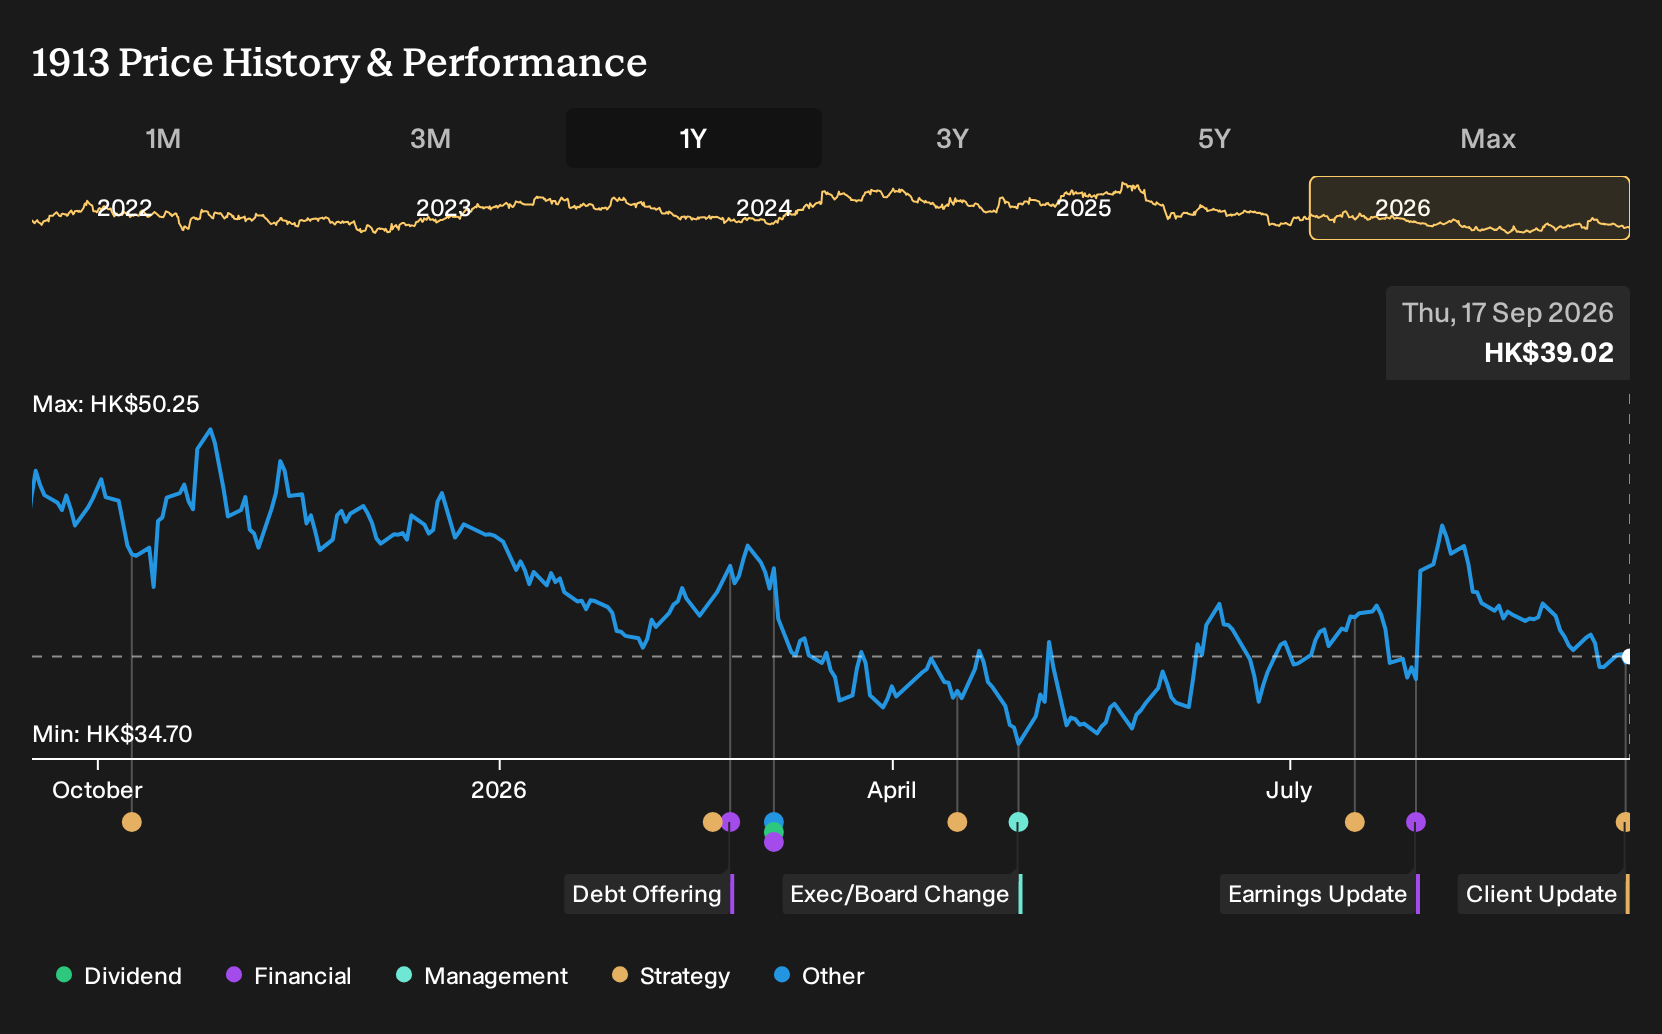
The price targets cluster around HK$49.86 per share, using those future cash flow and profitability assumptions alongside a discount rate of roughly 12%. The spread between the most optimistic HK$66.53 view and the HK$33.96 lowlight shows how divided the market is on how fully Prada can convert brand interest, retail upgrades and digital spend into hard numbers on the income statement.
For you as an investor, the key test is simple: decide whether mid single digit annual revenue growth, a small lift in margins and a higher P/E multiple relative to both Prada's current level and the sector feel reasonable given your view of tourism trends, cost pressure and the pace of execution on Versace and the wider store network.
Uncover why Prada's fair value indicates a 28% potential upside to its current price. This discount could close faster than you expect.
Exploring Other Perspectives
One alternative take on Prada focuses on Asia risk rather than tourism. The most bearish analysts were pencilling in about €7.2b revenue and €904.3 million earnings by 2029 before this Vitkac news, with a lower 12.6% margin. That is a more cautious script. Consider using this deal as a prompt to weigh how your own view might differ.
Explore 2 other Prada fair value estimates, including one that suggests it could be worth just HK$49.86!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Prada research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Prada. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Prada's overall financial health at a glance.
Looking For More Ideas Beyond Prada?
If Prada has sharpened your thinking about brands, margins and execution risk, it can help to line it up against a wider watchlist built around clear financial filters. The Simply Wall St Screener lets you jump straight to groups of companies that match the type of balance sheet strength, income potential or upside profile you want to research next.
- For investors who care most about downside protection, start with businesses screened for resilience and financial stability by checking out 104 resilient stocks with low risk scores.
- If reliable income is a priority, focus on companies that combine higher yields with sturdier fundamentals through the 160 dividend fortresses.
- When the goal is to uncover potential future leaders before they are widely followed, widen your net using the 618 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com