
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Archrock (AROC) Undervalued After The Strong Sell Rating And Earnings Estimate Cuts?
Fresh concern around Archrock (AROC) arose after Zacks shifted the stock to a Strong Sell rating, following downward revisions to consensus earnings estimates and recent negative surprises on both earnings and revenue.
At around $31.05 per share, Archrock has seen short term momentum cool, with the 7 day share price return down 5.79% and the 30 day share price return down 10.31%. This comes even though the year to date share price return is 16.60% and the 1 year total shareholder return is 33.89%, reinforcing a picture of strong multi year gains alongside fading near term enthusiasm.
Spot fresh compression service opportunities beyond Archrock by scanning our hand picked 33 high quality undervalued stocks. These combine sturdy cash flows with balance sheets built to handle earnings setbacks.Short term weakness, longer term gains and a fresh Strong Sell label now collide at roughly $31 per share. Does that set up a better entry later, or is Archrock already cheap enough to price in the hit to earnings expectations?
Most Popular Narrative: 31% Undervalued
Archrock last closed at $31.05. The most followed narrative on the stock pegs fair value closer to $44.88, which puts the recent Strong Sell label next to a very different long term story.
Archrock, Inc. (NYSE: AROC), a leading outsourced natural gas compression service provider in the United States, has built a unique moat to meet this structural demand with its 4.5 million horsepower (HP) capacity, electric motor drive (EMD) vision, and strategic acquisitions. Archrock''s compression services and aftermarket maintenance operations have transformed the company into an infrastructure monopoly that isolates itself from commodity price volatility, generating predictable cash flows and protected by contracts spanning decades.
See why 26 investors see Archrock as 31% undervalued.
Result: Fair Value of $44.88 (UNDERVALUED)
Still, the Archrock story carries clear risks if compression engine bottlenecks ease more quickly than expected, or if LNG and data center gas demand materializes more slowly.
Find out about the key risks to this Archrock narrative.
Another View: Archrock Through A Simpler Multiple
That detailed user DCF pins Archrock near $44.88, yet a quicker cross check tells a calmer story. At a P/E of 16.8x versus the US Energy Services average of 25.5x and a peer average of 40.9x, plus a fair ratio of 18x, the stock screens as cheaper than both its sector and its own historical relationship to fundamentals. Is that a margin of safety or a warning that the market sees slower days ahead?
To see how that pricing gap could close in either direction, and what the numbers imply for risk, See what the numbers say about this price — find out in our valuation breakdown.
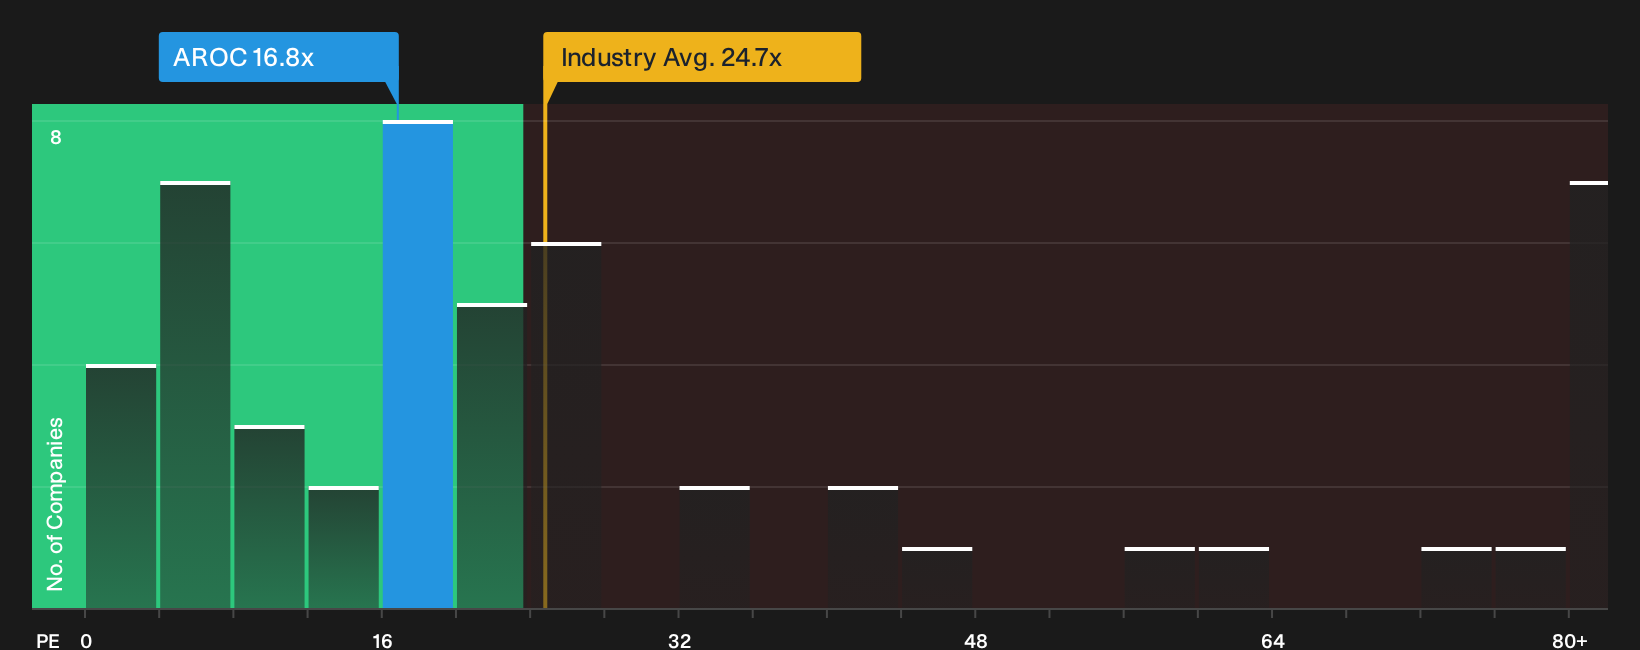
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Archrock for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Archrock now feels split between opportunity and risk, so consider acting promptly, review the evidence yourself and weigh both sides using the 5 key rewards and 2 important warning signs.
Looking for more Archrock style investment ideas?
If Archrock has your attention, do not stop here. Broaden your watchlist now with a few focused ideas that could help sharpen your overall portfolio decisions.
- Target reliable income by reviewing companies screened as dividend fortresses through the 6 dividend fortresses.
- Hunt for potential bargains by scanning a curated 16 high quality undiscovered gems that many investors may be overlooking.
- Dial down portfolio stress by checking a 11 resilient stocks with low risk scores designed around resilient balance sheets and lower risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com