
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Applied Digital (APLD) Could Be 67% Undervalued On Long Term Hyperscaler Leases
Applied Digital (APLD) has become a flashpoint after reporting very large year over year revenue growth and signing multi billion dollar, long dated leases with investment grade hyperscalers, even as heavy debt and sector repricing pressured the stock.
The share price tells a different story from the contracts. Applied Digital trades at about $24.39, with the stock down 21.78% on a 30 day share price return and 47.65% over 90 days, even though the 1 year total shareholder return is 23% and the 3 year total shareholder return is roughly 7x. This suggests that long term holders are still sitting on sizable gains, while shorter term momentum has faded as investors reassess leverage and capital intensity across AI infrastructure plays.
Capitalize on what this Applied Digital reset is revealing about sentiment in AI infrastructure by reviewing the hand picked 60 AI infrastructure stocks now shaping the next leg of this theme.Applied Digital now trades at a steep discount to analyst targets while carrying heavy debt and long dated leases that lock in revenue visibility. Is this caution simply prudent, or is the market mispricing the cash flows on the table?
Most Popular Narrative: 67% Undervalued
Applied Digital's most followed valuation storyline points to a fair value of about $73.36 against a last close of $24.39. This frames the current slump as a sharp gap between contracted revenue and how the market is pricing those future cash flows.
The accelerating industry need for high-density, geographically distributed data centers to support AI and machine learning workloads places Applied Digital in a favorable position, capitalizing on digital transformation trends that are set to drive ongoing utilization growth, improved asset values, and ultimately earnings expansion over the next several years.
See why 244 investors see Applied Digital as 67% undervalued.
That narrative leans heavily on long duration, take or pay leases with investment grade hyperscalers, and a fair value estimate of $73.36 that is built using a 9.52% discount rate and analyst assumptions about future earnings, margins and share count. The implied 67% discount to this figure highlights how much faith those followers are placing in Applied Digital's ability to turn contracted megawatts into durable profitability, even with a current loss of $249.243 million and a value score of 0.
Analysts feeding into this view are modeling high revenue expansion, a shift from losses into positive profit margins, and a 2029 earnings profile that would support a P/E of 288.4x on their forecasts. That is far above the 16.6x P/E cited for the broader US IT sector in the narrative. This means the story is not just about growth; it is also about investors accepting a premium valuation multiple if those data center campuses perform as expected.
At the same time, the narrative itself flags the pressure points that could break the thesis, including $688.2 million of debt, less than one year of cash runway, reliance on higher risk funding sources and exposure to cryptocurrency customers alongside concentrated hyperscaler relationships. For readers weighing Applied Digital today, the key step is to test those bullish revenue and margin paths against personal assumptions on utilization, refinancing costs and the pace of AI infrastructure demand.
Result: Fair Value of $73.36 (UNDERVALUED)
Still, Applied Digital’s reliance on a few hyperscaler tenants and a heavy debt load could quickly flip sentiment if contracts are reworked or if project timelines slip.
Find out about the key risks to this Applied Digital narrative.
Another View On Applied Digital: High Sales Multiple, Very Different Message
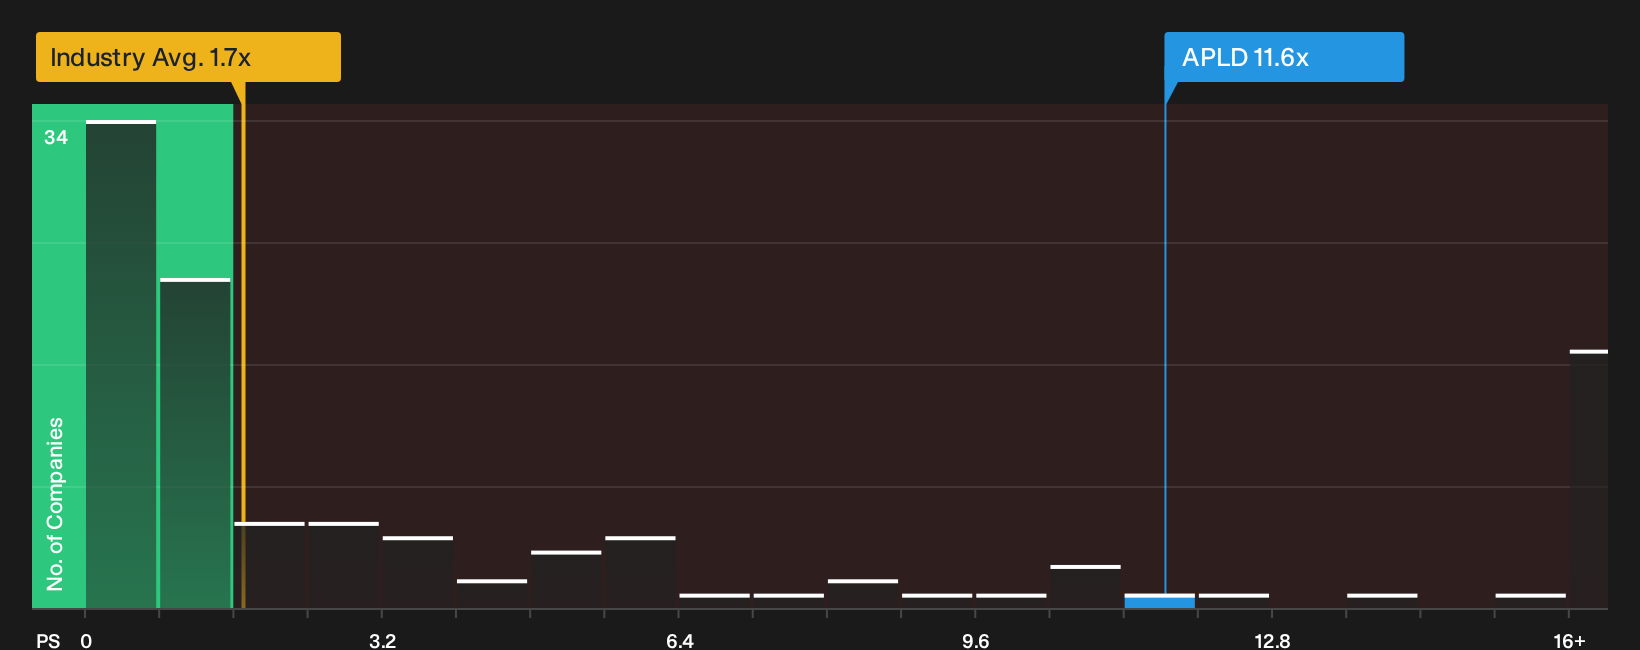
The first story around Applied Digital leans on long term leases and a modeled fair value of $73.36. A simple sales based lens tells something very different. At a P/S of 11.6x, the stock trades well above the US IT sector at 1.7x and peers at 6.4x, and even above a fair ratio of 8.6x that the market could drift toward if enthusiasm cools.
That kind of gap means investors are already paying a rich price for every dollar of current revenue, despite a reported loss of $249.243 million and a value score of 0. If the crowd ever demands profits to catch up with those contracts, how comfortable are you owning Applied Digital at this kind of premium?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Reading through the Applied Digital debate, the split between risk and reward is obvious. Move quickly, dig into the data, and decide where you land with 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Applied Digital?
Do not stop your research with a single AI infrastructure story. Broaden your watchlist and give yourself more options before the next big move hits.
- Target potential mispricings by scanning a curated set of 33 high quality undervalued stocks that combine solid fundamentals with room for sentiment to improve.
- Prioritize resilience by focusing on a list of solid balance sheet and fundamentals (22 results) that can better handle shocks and still support long term business plans.
- Spot future leaders early by reviewing a focused group of 16 high quality undiscovered gems before they appear on everyone else's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com