
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
McDonald's (MCD), Why Is Investor Attention Building Again?
Investor focus on McDonald's (MCD) has intensified ahead of its late September Investor Day, as softer consumer demand, inflation pressure, and neutral analyst views intersect with questions around traffic, efficiency, and long-term growth.
Recent trading has reflected those worries. McDonald's share price has slipped over the past month, with a 30 day share price return of a 6.4% decline and an 18.0% decline year to date, while the 1 year total shareholder return has fallen 16.4%. This signals fading momentum ahead of Investor Day as investors reassess both growth prospects and risk.
See how McDonald's compares with other consumer names facing similar pressures by exploring our hand picked 33 high quality undervalued stocks.
McDonald's share slide can hint at deeper cracks in the business, or just reflect investors cooling on the story. The next step is to see whether the current valuation lines up with the cash it actually produces.
Most Popular Narrative: 6% Overvalued
The most followed McDonald's narrative pegs fair value at $233.67, which sits below the recent $248.56 close, so the story skews slightly cautious on upside from here.
Please, as always, remember that the fair value estimate has a 100% probability of being wrong and it will never be a precise number, even if it has decimals next to it.
Back in my high school days working there, I saw in Portugal the shift to kiosks and the table RFID delivery system, things that are now second nature and seamlessly integrated. It makes me feel confident about their AI integration and the company’s future. Long story short, I really like this company, and I’m totally biased about it.
See why 40 investors see McDonald's as 6% overvalued.
Result: Fair Value of $233.67 (OVERVALUED)
Still, this narrative could unravel if consumer health trends pressure McDonald's menu more than expected, or if AI and efficiency projects take longer or cost more than planned.
Find out about the key risks to this McDonald's narrative.
Another View On McDonald's Valuation
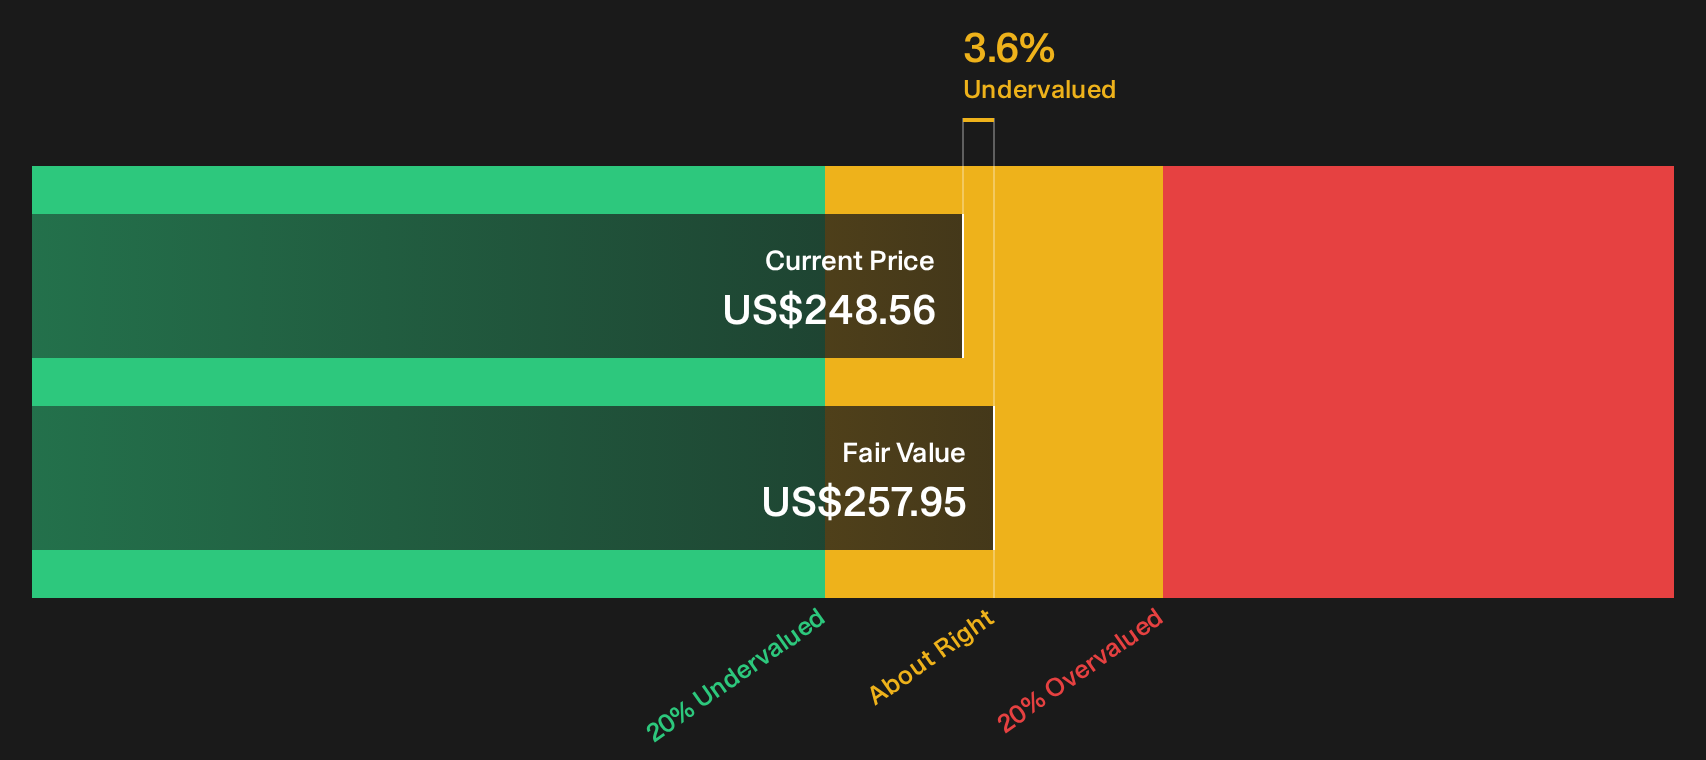
That 6% overvalued fair value from the narrative sits awkwardly next to our own SWS DCF model. On current inputs, the discounted cash flow result points to a fair value of $257.95, which is above the $248.56 share price. By this lens, McDonald's looks modestly undervalued. So which story do you trust when the models disagree on direction?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on McDonald's value can create noise, so consider acting while sentiment is split and build your own view by weighing the 6 key rewards and 1 important warning sign.
Looking for more McDonald's style investment ideas?
If McDonald's valuation story has you thinking harder about where you put capital next, do not stop here. Broaden your watchlist with focused ideas that line up with your risk tolerance and income goals.
- Target potential mispricings by reviewing our hand picked 33 high quality undervalued stocks that combine solid fundamentals with room for sentiment to shift.
- Strengthen portfolio resilience by scanning a list of solid balance sheet and fundamentals (22 results) so you are not caught off guard by fragile financing or stretched leverage.
- Lock in reliable income streams by checking a curated 6 dividend fortresses that can help you build a portfolio where cash returns play a central role.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com