
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Does Huntington Bancshares (HBAN) Tempered Outlook Mean For Its Loan Growth?
- Huntington Bancshares (NasdaqGS:HBAN) lowered its profitability outlook as persistently high interest rates pressure loan economics.
- Management highlighted weaker loan yields, with particular softness in commercial real estate and indirect auto lending portfolios.
- The CEO reiterated a focus on credit discipline and expressed confidence in the bank's ability to outperform despite macro headwinds.
- There is more to Huntington's tempered profitability outlook and pressured loan books than this single update captures. Our analysis turns up 5 other big wins for Huntington Bancshares as well.
For readers tracking how higher-for-longer rates affect income-focused banks, it is worth comparing this update with peers through 6 dividend fortresses.
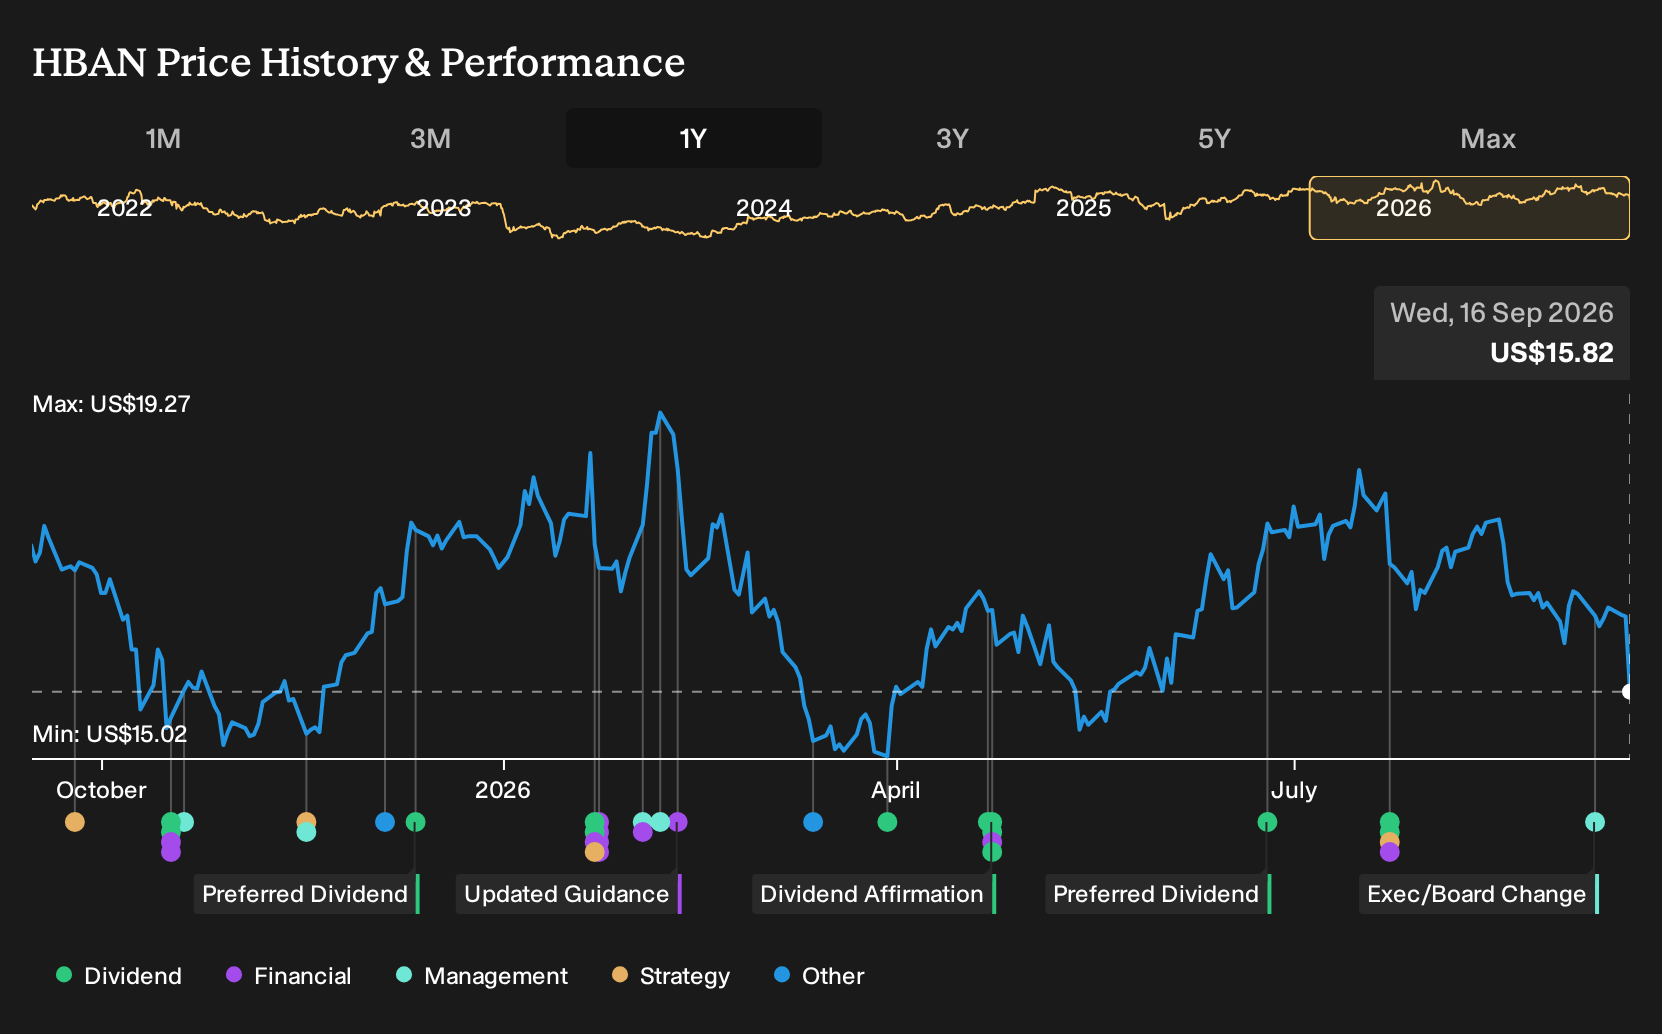
Huntington Bancshares, a US$33.8b regional lender, leans heavily on commercial, consumer, and mortgage banking, so shifts in loan demand and pricing feed directly into its earnings power. For readers, that footprint makes swings in commercial real estate and auto credit especially important when judging how durable its profit engine looks.
Higher-for-longer rates test Huntington Bancshares' growth and efficiency story
The Huntington Bancshares Narrative leans on a simple idea. Management is trying to use acquisitions, digital tools and operating discipline to turn a larger regional footprint into stronger long-term earnings power, even as banking conditions stay tough.
"Enhanced efficiency through technology investment, process reengineering, and scale from recent acquisitions is delivering positive operating leverage and improving the efficiency ratio trend..."
See how the full story points towards a $20.34 fair value for Huntington Bancshares.
The tempered profitability outlook cuts straight across that efficiency catalyst. Higher funding costs and weaker loan yields in commercial real estate and indirect auto lending make it harder for Huntington Bancshares to show that larger scale and digital spending are translating into better margins than peers like PNC or Fifth Third.
The new President, Brant Standridge, now has every revenue engine under his watch just as these pressures bite. That timing links leadership continuity directly to two Narrative swing factors: extracting more fee income, and keeping expansion into Texas and the Carolinas from turning into an overextension risk flagged by analysts.
To make sense of updates like this, you need a clear view of where Huntington Bancshares is trying to go, which is exactly what a focused Narrative sets out.
One Huntington Bancshares thread this story leaves hanging
Everything here has focused on what Huntington Bancshares looks like today. However, the analyst models sketch a very different destination a few years out that could reshape how you think about its earnings power. See where analysts expect Huntington Bancshares to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com