
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Novo Nordisk (CPSE:NOVO B) Stock May Be Undervalued Following Fresh AI Drug Discovery News
Novo Nordisk has been busy reshaping its pipeline and brand at the same time as its share price has retreated, which puts fresh focus on whether today’s valuation still lines up with what the business earns. With Novo rolling out new obesity and cardiometabolic initiatives while the stock has given back a large chunk of its prior gains, the key issue for you is how much of that story is already embedded in its earnings profile.
- Over the past 3 years the share price has fallen 52.6%, which raises the question of whether the market has reset expectations on Novo’s earnings too far or not far enough.
- The new partnerships in cardiometabolic drugs and AI driven discovery, plus preparations to launch products like FREHEMGO and potential new uses for semaglutide, can influence how quickly profits grow and how durable Novo’s earnings base might be.
- There is a second opinion on Novo Nordisk worth weighing. See what analysts think Novo Nordisk's shares could be worth.
The stock’s next move may depend on whether Novo Nordisk’s current price can be explained by the earnings power investors see in the business today.
If you are weighing Novo Nordisk’s earnings story after a 52.6% share price decline over 3 years, it can help to benchmark it against other 177 high quality undervalued stocks
Is Novo Nordisk Still Cheap on Earnings?
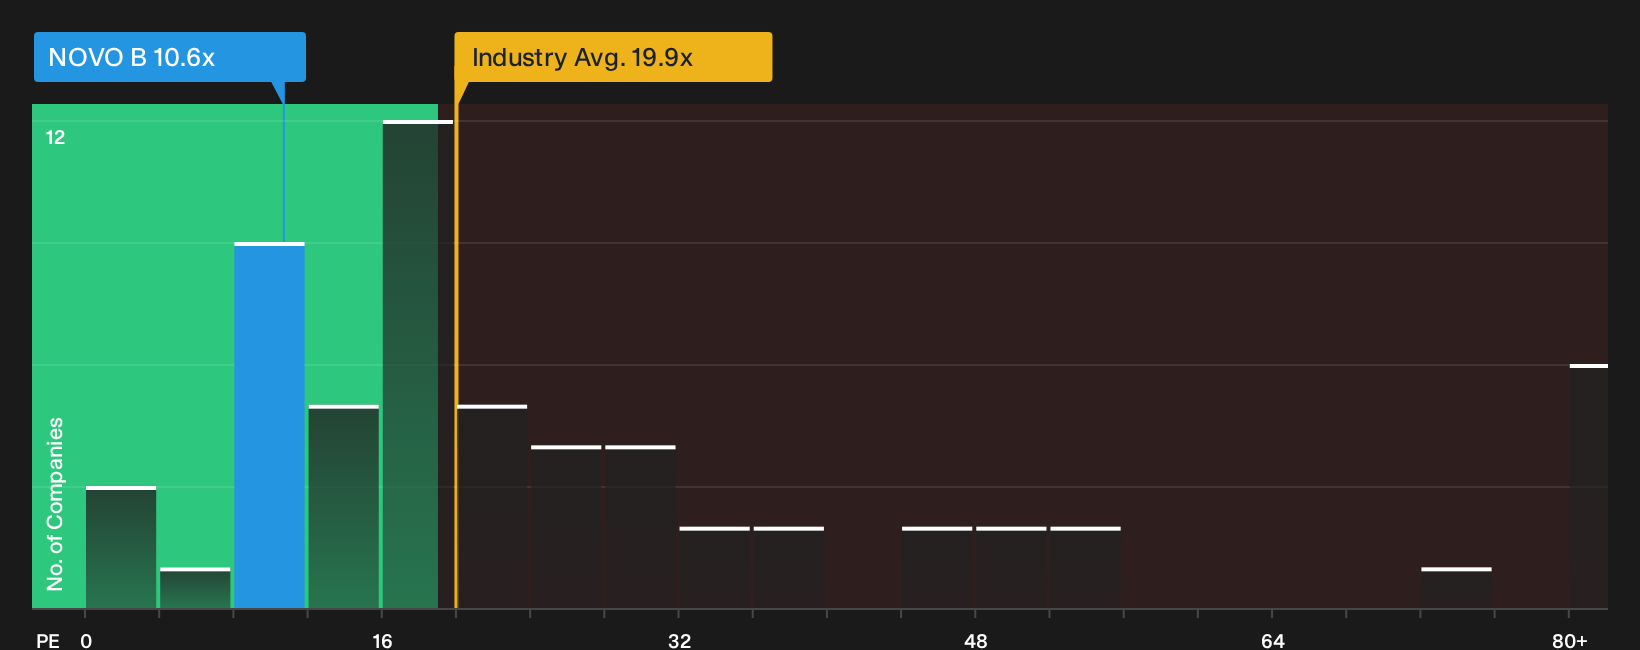
The P/E ratio fits Novo Nordisk because earnings remain the main lens investors use for mature pharmaceutical groups. Novo trades on a P/E of 10.6x, which is less than half the wider Pharmaceuticals industry average of 21.8x and also well below the peer group on 22.0x. On this framework, the stock changes hands at a marked discount to what investors are currently paying for similar businesses.
The Fair Ratio, which reflects what the P/E might look like after adjusting for Novo Nordisk’s margins, growth profile, size and risk, points to the current 10.6x level as undervalued. Because the rebrand to “Novo” and the AI powered drug discovery partnerships have not stopped the share price from resetting lower, the gap between today’s multiple and this tailored yardstick suggests the market is pricing in a more cautious earnings outlook than those fundamentals alone would imply. You still need to weigh pipeline execution, obesity market competition and regulatory outcomes before deciding whether that discount is deserved or an opportunity. Explore the numbers behind Novo Nordisk's P/E valuation.
The Novo Nordisk Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle leaves off for Novo Nordisk. They spell out the earnings, margin and growth paths that would need to play out for the current share price to look either conservative or stretched, and each one connects its number back to a clear view on how Novo Nordisk's growth, profitability and risks could evolve. This gives you something specific to revisit as new information arrives.
Community views on Novo Nordisk’s valuation pull in opposite directions, with one camp seeing a discounted leader and the other flagging mounting risks.
Bull case: 67% undervalued
"With high barriers to entry, a booming market for obesity treatment, and a pipeline that keeps expanding, Novo Nordisk’s future looks remarkably secure…"
Discover why this Narrative puts Novo Nordisk at 67% undervalued.
Bear case: 40% overvalued
"Heavy reliance on blockbuster therapies and looming patent expirations expose Novo Nordisk to revenue pressure from biosimilar competition and pricing headwinds…"
Explore why this Narrative puts Novo Nordisk at 40% overvalued.
For Novo Nordisk, the share price is only half the story
Numbers on a screen do not tell you who is steering Novo Nordisk or how those leaders are rewarded for the choices they make with your capital. See who runs Novo Nordisk and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com