
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Investor Forum Targets Could Be A Big Moment For Ciena (CIEN)
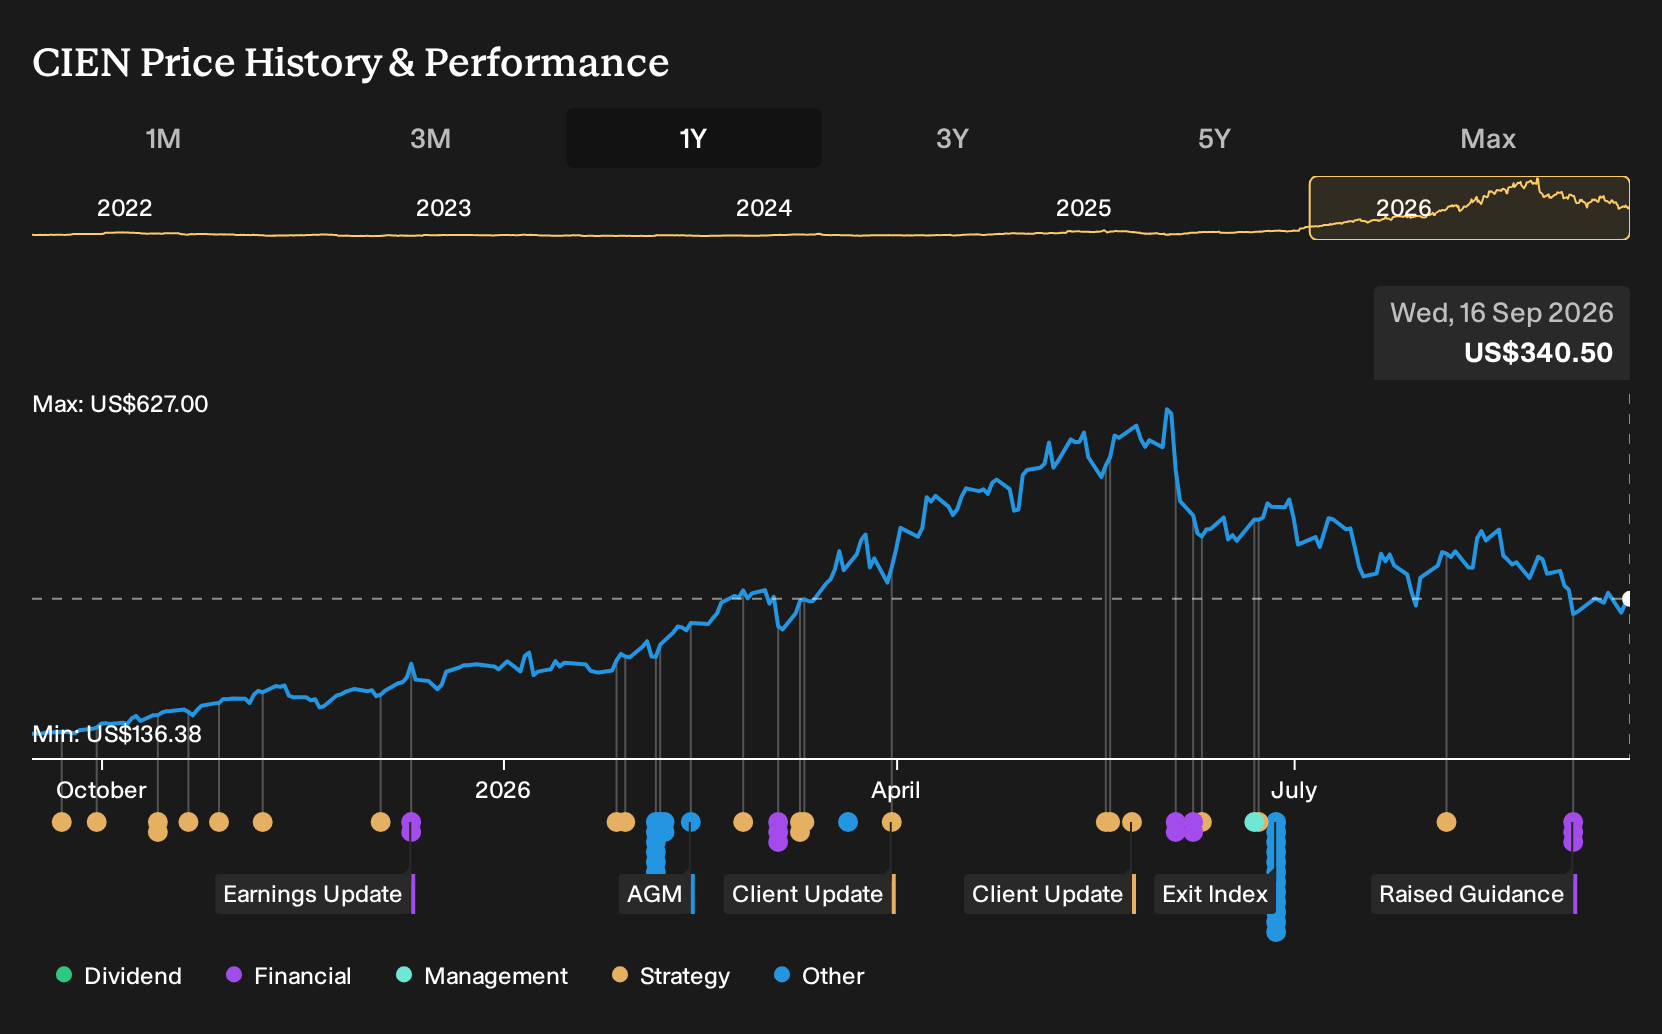
- Ciena reported Q3 2026 revenue of US$1,671.13 million and net income of US$266.42 million, raised full year revenue guidance to about US$6.42b, outlined Q4 2026 revenue expectations, updated progress on its buyback, and later held an Investor Forum to set three year financial targets through 2029.
- The new three year plan, which includes around 30% targeted revenue CAGR, roughly 50% adjusted gross margin and a 32% to 35% adjusted operating margin range, reflects how Ciena’s management is framing long term execution priorities and reshaping reporting segments around higher growth areas.
- We will now look at how Ciena's new multi year revenue and margin targets may influence the existing investment narrative that investors rely on.
Ciena Investment Narrative Recap
To own Ciena, you need to believe that AI driven data traffic and cloud networking will keep driving demand for high capacity optical systems and software, and that management can execute against those multi year targets. The recent Q3 print, higher full year revenue guidance and new 2029 margin goals keep that growth narrative front and center in the near term.
The key short term swing factor is execution on hyperscaler and neo scaler deployments without major order lumpiness or deployment delays. The biggest risk remains customer concentration and exposure to AI and cloud capex cycles, which the new guidance does not eliminate but makes more visible by spelling out revenue and margin ambitions.
The most relevant update for that story is Ciena’s raised fiscal 2026 revenue outlook to about US$6.42b, with Q4 revenue expected around US$1.75b, plus or minus US$50 million. Those figures frame how much AI and cloud driven demand is flowing into the income statement today, not just into the long term order book.
That guidance, paired with the Investor Forum targets of roughly 50% adjusted gross margin and 32% to 35% adjusted operating margin, puts execution risk squarely on whether the firm can keep mix, pricing and costs aligned while leaning harder into AI infrastructure. For you, the real question is how comfortable you are with that blend of higher growth opportunity and concentrated hyperscaler exposure.
Ciena Consensus Targets Versus Today’s Earnings Power
Ciena's analyst story hinges on revenue forecasts of US$11.1b and earnings projections of US$1.8b by 2029. That profile sits on top of an assumed 25.8% yearly revenue growth rate and an earnings path that moves from US$438.3m today to US$1.8b, which is roughly a 4x increase in profit over the period.
Uncover how Ciena's fair value indicates a 62% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view focuses on Ciena’s software and international expansion as the real long term catalyst. The most optimistic analysts were already penciling in about US$13.3b of revenue and US$2.3b of earnings by 2029, far above consensus. Those figures came before this earnings beat and Investor Forum update, so opinions may change.
Explore 5 other Ciena fair value estimates, including one that suggests up to 111% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Ciena research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ciena. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ciena's overall financial health at a glance.
Looking for more investment ideas beyond Ciena?
If Ciena's AI driven story has your attention, it can be useful to compare it with other companies that share similar quality markers or risk profiles. The Simply Wall St Screener lets you filter for traits that matter to you, whether that is balance sheet strength, steady income, or underappreciated potential.
- If capital preservation sits high on your list, consider starting with a set of companies that score well on resilience and risk, such as the 11 resilient stocks with low risk scores.
- For investors hunting for underappreciated potential, a curated basket of strong operators trading below estimated fair value, like the 33 high quality undervalued stocks, can be a useful starting point.
- If income matters more than headlines, focus on businesses built around consistent cash returns to shareholders, beginning with the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com