
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Debt Raise Change CleanSpark (CLSK) Narrative
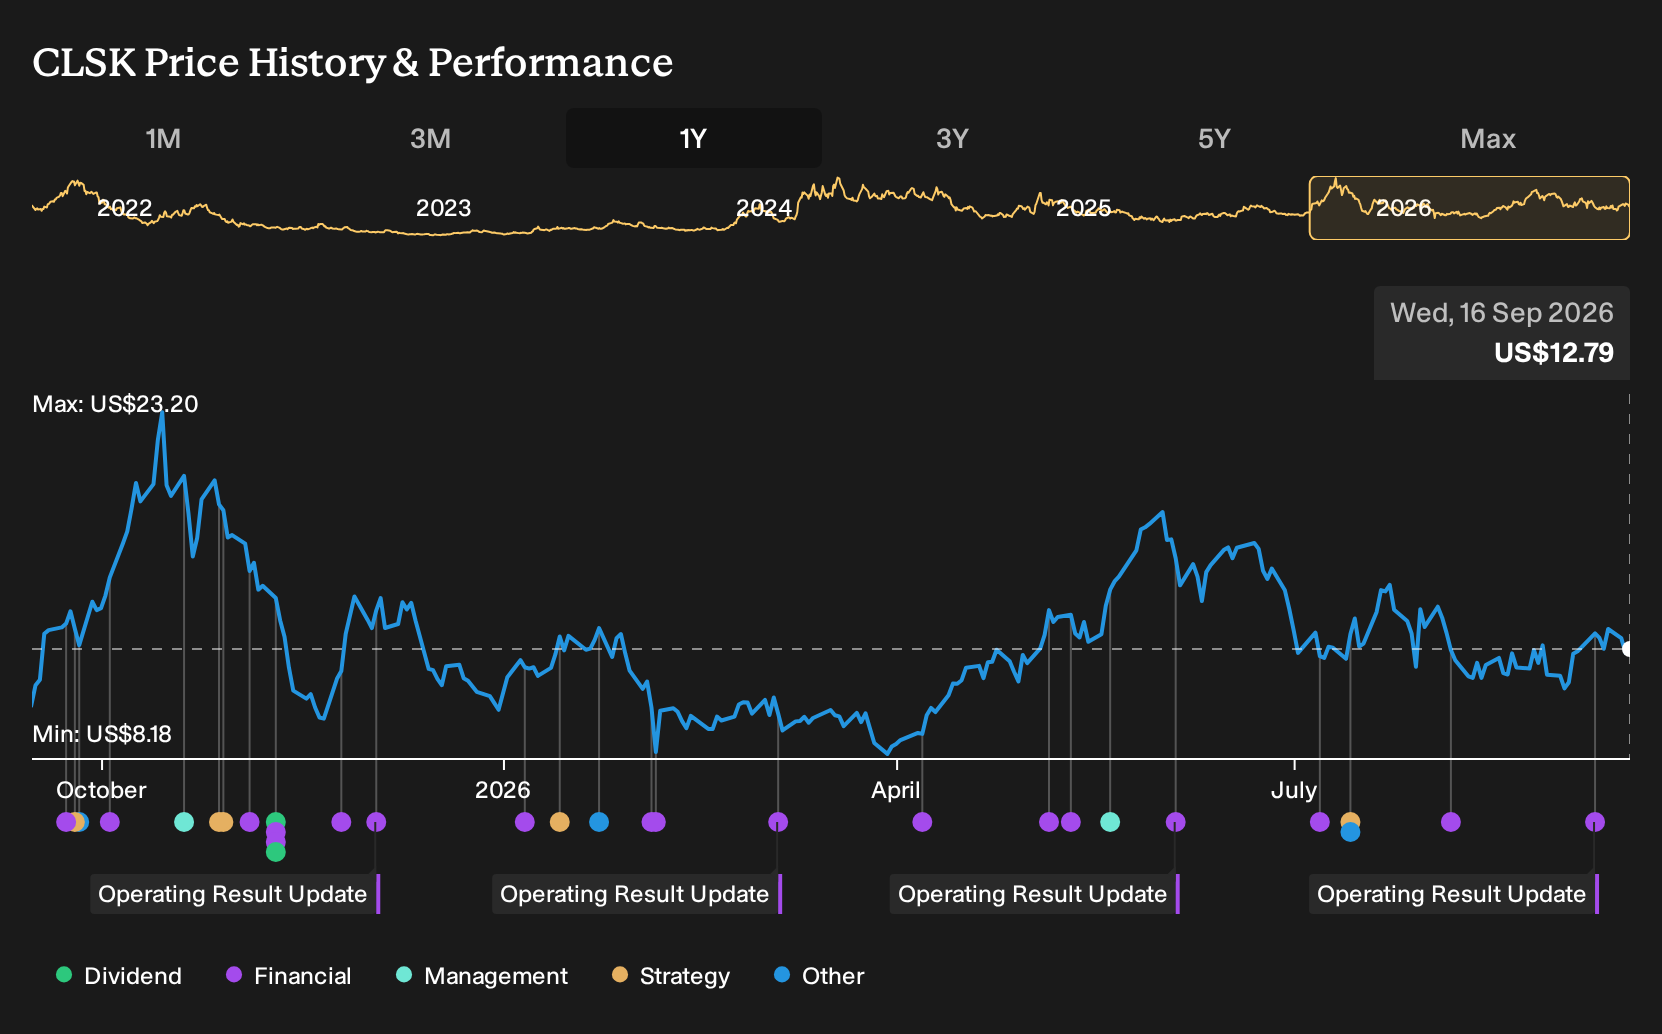
- CleanSpark, through subsidiary CSDC Finance I, LLC, recently announced an intended private offering of US$2.227 billion in senior secured notes due 2031, backed by first-priority liens and guarantees tied to its Sandersville data center assets.
- The planned bond raise concentrates financial risk and funding capacity around the Sandersville facility, turning that single data center build into a key test of CleanSpark’s capital allocation, execution discipline, and long-term operating efficiency.
- We will look at how CleanSpark's investment narrative is reshaped by this large secured notes financing for the Sandersville data center.
Scan how other bitcoin miners and data center plays are positioning their balance sheets by reviewing the hand picked 18 cryptocurrency and blockchain stocks alongside CleanSpark's latest debt move.
CleanSpark Investment Narrative Recap
To own CleanSpark, you need to believe Bitcoin mining remains economically attractive and that CleanSpark can keep scaling efficient capacity faster than costs and dilution. The big near term swing factor is execution at Sandersville and across new power approvals in Texas and Georgia. The planned US$2.227b secured notes concentrate that bet into one asset cluster and tighten the link between uptime, efficiency and balance sheet health.
The largest immediate risk is leverage layered onto an already capital hungry, Bitcoin exposed model while the business is still loss making and has less than one year of cash runway. If the notes are not priced or placed on acceptable terms, that mostly affects project timing rather than the core thesis, but it would raise questions about funding flexibility.
The August production update, with 593 Bitcoin mined in the month and 4,903 year to date, is the most useful operational anchor for this debt story. Those figures show the current scale of output that will need to support a much larger capital base if the Sandersville financing goes ahead as described.
For you as a shareholder, the question is whether that run rate plus future hash from Sandersville and the new Texas and Georgia sites can support interest costs and fleet refresh, and still leave room to reduce losses. Any disruption to mining economics, energy pricing or site completion would directly affect how manageable the new debt stack feels and how quickly CleanSpark can move closer to self funding growth.
CleanSpark's current analyst narrative points to revenues of US$857.1 million and earnings of US$98.0 million by 2029, built on an assumed 8.1% yearly revenue growth rate and an earnings swing of roughly US$1.1b from a loss of US$1.0b today to that projected profit level.
Uncover why CleanSpark's fair value indicates an 86% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Some of the most optimistic analysts focus on a different catalyst for CleanSpark. They lean into the idea that rapid build outs and power access could support much faster expansion, which is why they were modeling roughly US$1.2b of revenue and US$148.2m of earnings by 2029. Those projections were set before this US$2.227b debt plan, so you should expect opinions and narratives to evolve. Use this bond news as a trigger to compare those bullish assumptions with your own view and explore several contrasting forecasts before deciding how you feel about the stock.
Explore 4 other CleanSpark fair value estimates, including one that suggests as much as 103% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CleanSpark research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for CleanSpark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CleanSpark's overall financial health at a glance.
Looking For More Investment Ideas Beyond CleanSpark?
CleanSpark may be front of mind right now, but your portfolio decisions will usually feel stronger when you compare it against a wider set of opportunities. Use the Simply Wall St Screener to stress test your thesis and line CleanSpark up against companies with very different risk and return profiles.
- If you want potential upside with smaller market values, filter for compact operators using the 11 elite penny stocks with strong financials and see how they stack up against CleanSpark's risk profile.
- For readers who care most about price versus quality, run a screen for attractively priced businesses through the 33 high quality undervalued stocks and compare their fundamentals with what you see at CleanSpark.
- Anyone focused on capital preservation and smoother ride potential can search for sturdier balance sheets using the 11 resilient stocks with low risk scores to find shares that may complement or offset a higher risk position like CleanSpark.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com