
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Graham (GHM) Is Getting Attention Again, What Is The Market Weighing?
Graham (GHM) is drawing fresh attention after a sharp move in its share price, with the stock up 1.9% in the latest session but lower over the past month.
That 1 day share price gain comes after a much tougher stretch, with Graham down 26.2% on a 1 month share price basis and 23.0% over 3 months, even as the year to date share price return is 28.5% and the 1 year total shareholder return is 63.1%. The 3 year total shareholder return is more than 4x and the 5 year total shareholder return is above 6x, suggesting long term holders have still seen strong momentum despite the recent pullback.
Scan other industrials showing similar price swings and long term return profiles by reviewing the hand picked 16 high quality undiscovered gems alongside Graham.
That mix of sharp pullback and hefty multi year gains puts Graham in an awkward spot for fresh money. Is this the moment to step in, or does it make more sense to wait for a better price before beginning the valuation work?
Most Popular Narrative: 32% Undervalued
Analysts who follow Graham see a fair value well above the last close of $85.28. This puts extra weight on the long term growth story supporting that view.
Record backlog growth and strong book-to-bill ratio signal rising multi-year demand, underpinned by sustained U.S. Navy defense programs and increasing global infrastructure investment, supporting future revenue visibility and stability.
See why 21 investors see Graham as 32% undervalued.
Result: Fair Value of $125.75 (UNDERVALUED)
Still, this story unravels quickly if U.S. defense orders slow or if early bets on small modular nuclear and cryogenics fail to translate into meaningful programs.
Find out about the key risks to this Graham narrative.
Another View: Graham Looks Expensive On Earnings
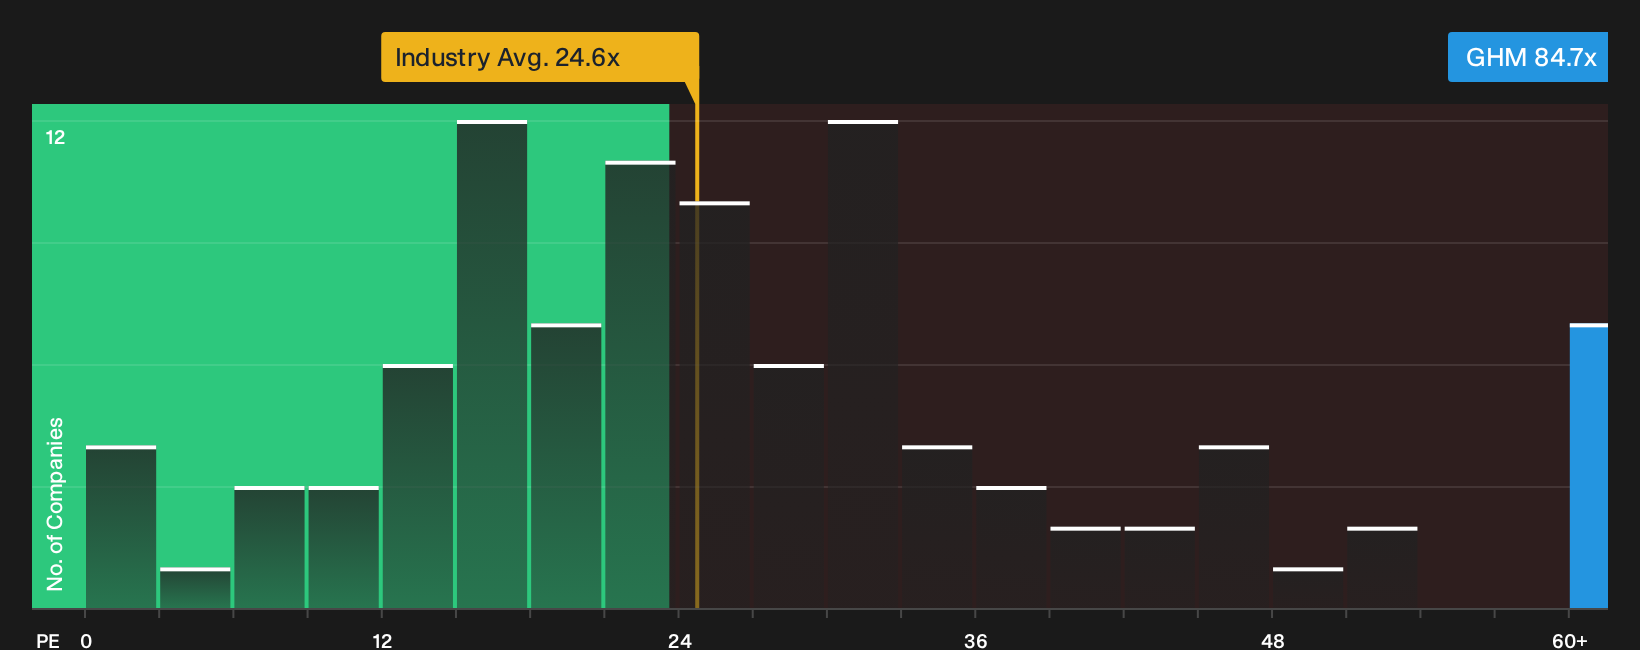
Switching from fair value models to a straightforward P/E perspective makes Graham look less forgiving. The stock trades on 84.7x earnings compared with 24.3x for the wider US Machinery group and 37.8x for direct peers, while the fair ratio stands at 34.1x.
This gap indicates that investors are already paying a substantial premium for Graham, above both competitors and the level suggested by the fair ratio. If sentiment cools or growth expectations reset, how much compression in that multiple are you prepared to tolerate?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity: you decide. If you think the reward case deserves a closer look, start by reviewing the 2 key rewards.
Looking for more Graham investment ideas?
If Graham has sharpened your focus, do not stop here. Broaden your opportunity set and let data rich stock shortlists do the heavy lifting for you.
- Target resilient cash generators by reviewing a list of solid balance sheet and fundamentals (22 results) that can help you stress test your portfolio before the next rough patch hits.
- Hunt for quality at a discount and work through a curated 33 high quality undervalued stocks before prices move away from levels that still look reasonable.
- Build a steadier income stream by scanning a focused 6 dividend fortresses that could highlight yields you might otherwise overlook.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com