
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Avery Dennison (AVY) Stock Looks Fairly Valued Following Its 12% Five Year Fall
Avery Dennison has delivered a mixed ride for shareholders over the past few years, and the stock now trades near recent levels after a patchy stretch of returns. That raises a straightforward question for anyone looking at the ticker today: Is the current price justified by the earnings the business is generating?
- Over the past 5 years the share price has declined 11.6%, which puts the spotlight on whether the market is now paying the right multiple for Avery Dennison's profits.
- Recent earnings news highlighted revenue growth and profit strength, which can feed into expectations for how reliably Avery Dennison might convert future sales into cash that supports its valuation.
- There is a second opinion on Avery Dennison worth weighing. See what analysts think Avery Dennison's shares could be worth.
The issue now is whether Avery Dennison's current valuation makes sense when lined up against the earnings it is producing today.
If you are weighing Avery Dennison against similar earnings driven stories, it can help to compare it with companies highlighted in 33 high quality undervalued stocks.
Does Avery Dennison Look Fairly Valued on Earnings?
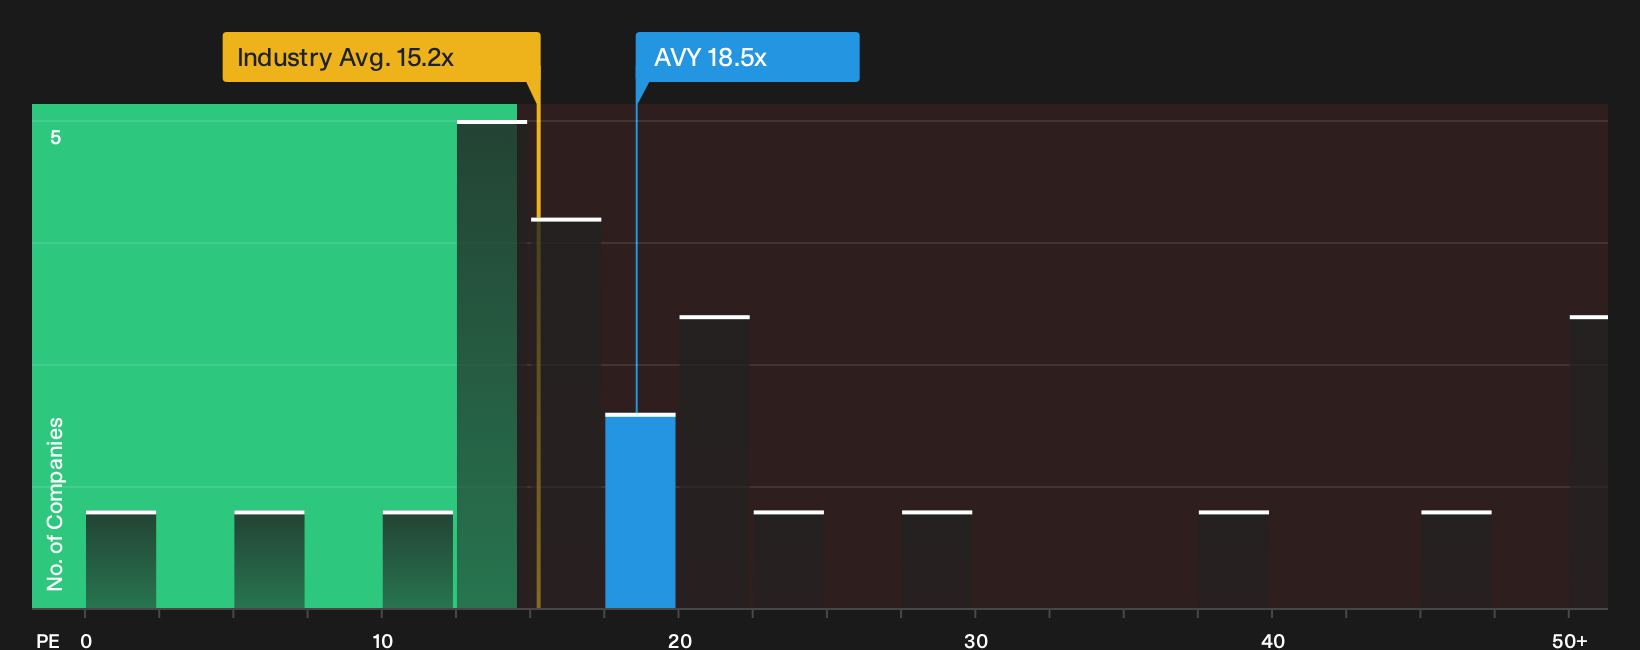
A P/E ratio suits Avery Dennison because earnings are a key yardstick for a mature, cash generating label and packaging business. On that score, the shares trade on about 18.5x earnings, which is below the broader packaging sector average of roughly 15.2x and well under the peer group on roughly 25.4x. That puts the stock in a middle ground where it is not priced at a deep discount to the industry but also not at the richer levels seen across closer comparables.
Because the latest quarter delivered revenue and profit beats, the current multiple is close to the level implied by a tailored fair value P/E that accounts for Avery Dennison's size, margins and risk profile, so the model does not flag the stock as clearly overvalued or obviously cheap on earnings alone. Despite the solid Q2 headlines, the market is valuing each dollar of profit at a level that roughly matches what this framework would suggest, which leaves the question of upside resting on how you view the durability of those earnings. Explore the numbers behind Avery Dennison's P/E valuation.
The Avery Dennison Narrative: What Would Justify Today's Price?
Narratives on Avery Dennison sit between the current P/E puzzle and your own expectations, since they spell out what would need to happen with future growth, margins and earnings for the stock to be worth materially more or less than today’s price, and they live on Simply Wall St’s Community page. Each one treats fair value as a thesis about Avery Dennison's business that can be tracked over time rather than a single frozen estimate.
One of the top community narratives on Avery Dennison: 14% undervalued
"Bullish analysts highlight the RFID partnership with Walmart as a key growth driver..."
Discover why this Narrative puts Avery Dennison at 14% undervalued.
One more Avery Dennison piece that could change how you see the stock
Everything so far has focused on what Avery Dennison earns today, but there is a separate view that looks a few years down the road and tests whether current expectations line up with that picture. Explore where analysts expect Avery Dennison to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com