
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Microsoft AI Network Deal Change Nokia's (HLSE:NOKIA) Narrative
- Nokia Corporation recently expanded its AI-focused partnership with Microsoft and reported broader AI-RAN trials with global telecom operators, highlighting concrete product, customer and alliance progress across core network automation and radio access technologies.
- The push into agent-based network automation and AI-RAN suggests Nokia is working to deepen its role inside customers’ day-to-day network operations. This can influence recurring software and services demand, as well as switching costs over time.
- We will now look at how Nokia's AI-driven network automation push with Microsoft could shape the broader investment narrative for the business.
Nokia Oyj Investment Narrative Recap
To own Nokia Oyj, you need to believe that its heavy push into AI driven automation can gradually improve a low net margin base and support steadier earnings, despite a highly competitive mobile infrastructure market. The Microsoft Fabric tie up fits that thesis because it is aimed at turning Nokia’s telco software and data assets into more repeatable, higher value software and services.
In the near term, the key swing factor remains execution in Mobile Networks and the timing of carrier capex, while currency and pricing pressure remain real risks. The expanded Microsoft partnership looks directionally helpful for Cloud and Network Services, but on its own it does not remove the pressure from commoditization, Open RAN or earnings volatility.
The extended Microsoft collaboration around a unified telco data foundation is the announcement that most directly links to Nokia Oyj’s AI RAN and automation story. It gives operators an operational path from siloed data to agent based use cases such as autonomous VoNR assurance, RAN geo experience and predictive maintenance, all using Nokia’s data products on Microsoft Fabric.
For catalysts, this matters because it turns AI from slideware into a concrete offer that can be trialed and scaled across multi vendor networks. This may support Cloud and Network Services and higher margin software revenues over time. Execution risk remains significant. Telecom buyers still face budget, integration and governance hurdles, and any delay or disappointment would keep Nokia more exposed to the slower growing, price pressured parts of its portfolio.
Nokia Oyj's current analyst narrative points to €23.5 billion in revenue and €2.6 billion in earnings by 2029, based on an assumed 4.8% yearly revenue growth rate and an earnings increase of about €1.9 billion from €702.0 million today.
Uncover why Nokia Oyj's fair value indicates a 14% potential upside to its current price that could narrow quickly.
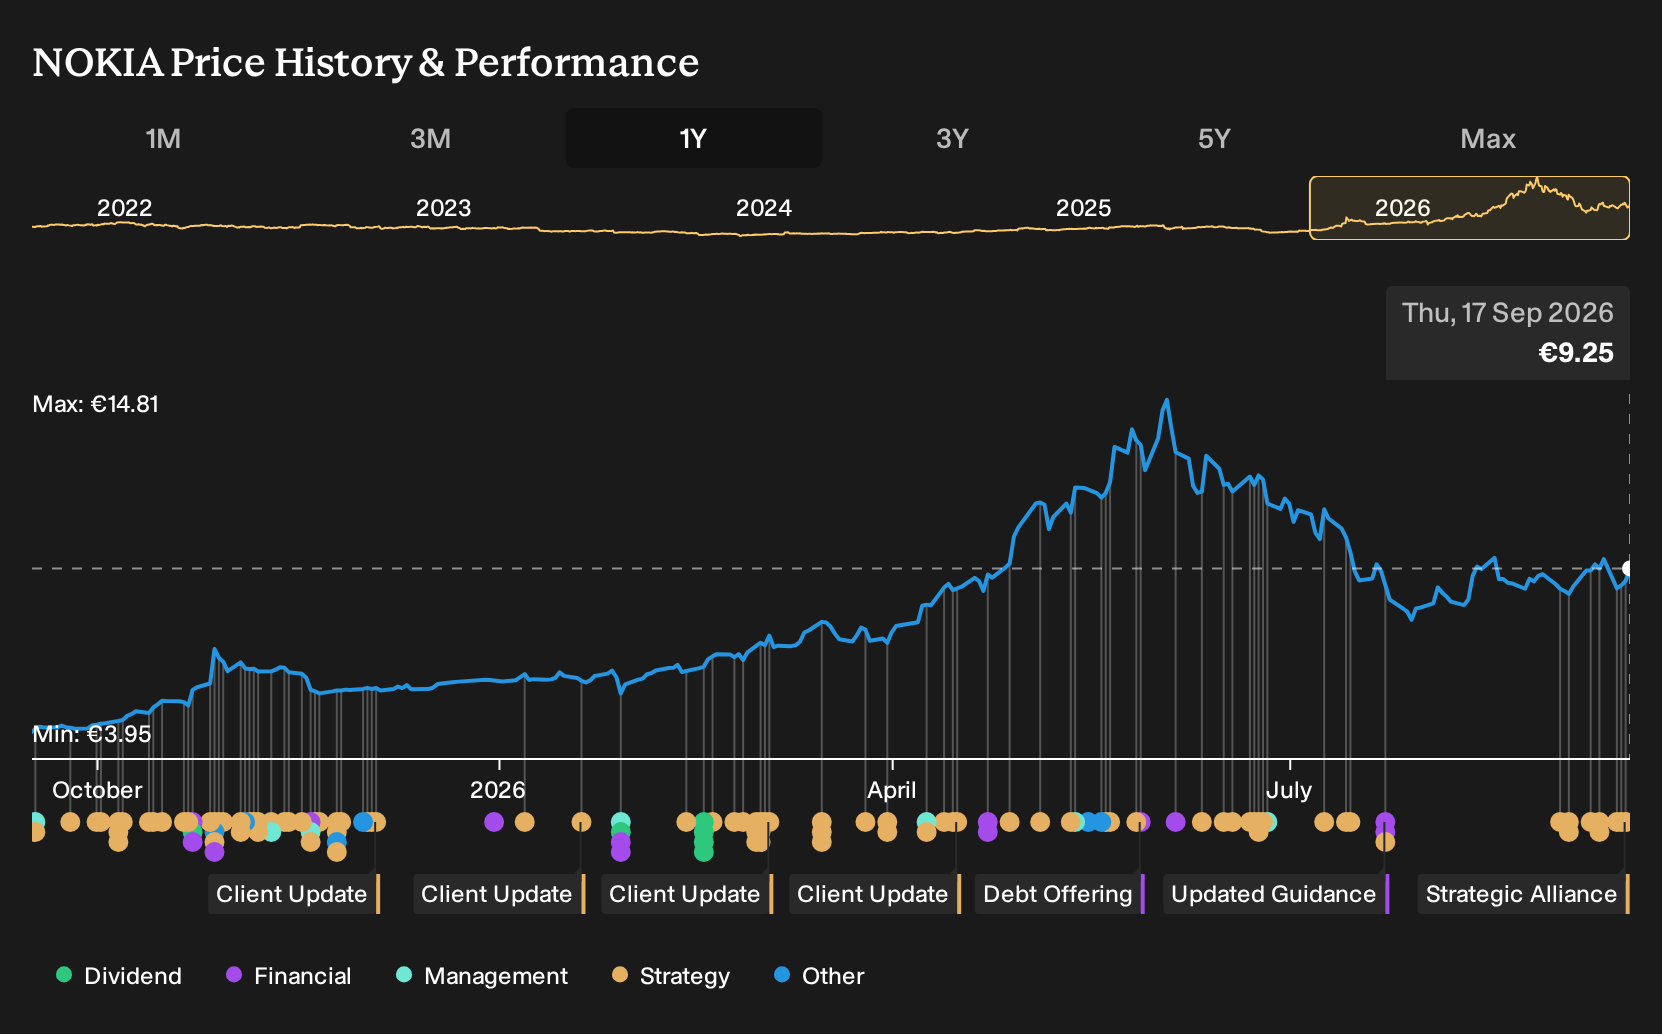
Exploring Other Perspectives
One alternate view focuses on commoditization risk. Under that lens, Nokia Oyj’s extended Microsoft AI partnership could help, but bearish analysts still see tighter room for error. They were working off revenue of about €21.8b and earnings of roughly €1.8b by 2029, which frames a far more cautious story that may shift as this news filters in.
Explore 4 other Nokia Oyj fair value estimates, including one that suggests it could be worth just €10.58.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nokia Oyj research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nokia Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nokia Oyj's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nokia Oyj?
If this Nokia Oyj story has you thinking about how AI, infrastructure and balance sheets all fit together, it can help to widen the lens and compare it with a broader set of opportunities using the Simply Wall St Screener.
- For investors who want potential value combined with quality fundamentals, take a look at 177 high quality undervalued stocks that pass a strict filter on both earnings strength and balance sheet support.
- If capital preservation matters most to you, focus on resilience and lower volatility by reviewing 104 resilient stocks with low risk scores that score well on financial stability and risk checks.
- For those hunting for lesser known opportunities with solid underlying numbers, scan through 618 high quality undiscovered gems that may not yet be widely followed but still clear key fundamental hurdles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com