
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Samsung (KOSE:A005930) Stock May Be Undervalued On Earnings Power
Samsung Electronics has seen a striking run over the past few years, which puts fresh focus on whether the current share price lines up with what its earnings can reasonably support. After such a move, the core issue for you is whether the profits behind the story are strong enough to justify paying today’s multiple.
- Over the past 3 years, Samsung Electronics has returned about 287.5%, which puts a lot of weight on whether its earnings can keep carrying that kind of value creation argument.
- The group’s role across memory, foundry and consumer hardware means its long term earnings power may depend heavily on how efficiently it can convert large capital spending into durable profit margins.
- There is a second opinion on Samsung Electronics worth weighing. See what analysts think Samsung Electronics's shares could be worth.
The stock's next move may depend on whether Samsung Electronics’ current earnings profile is strong enough to support the price investors are being asked to pay today.
If you want to test the same earnings question you are asking of Samsung Electronics across a broader opportunity set, take a look at 177 high quality undervalued stocks.
Is Samsung Electronics Still Cheap on Earnings?
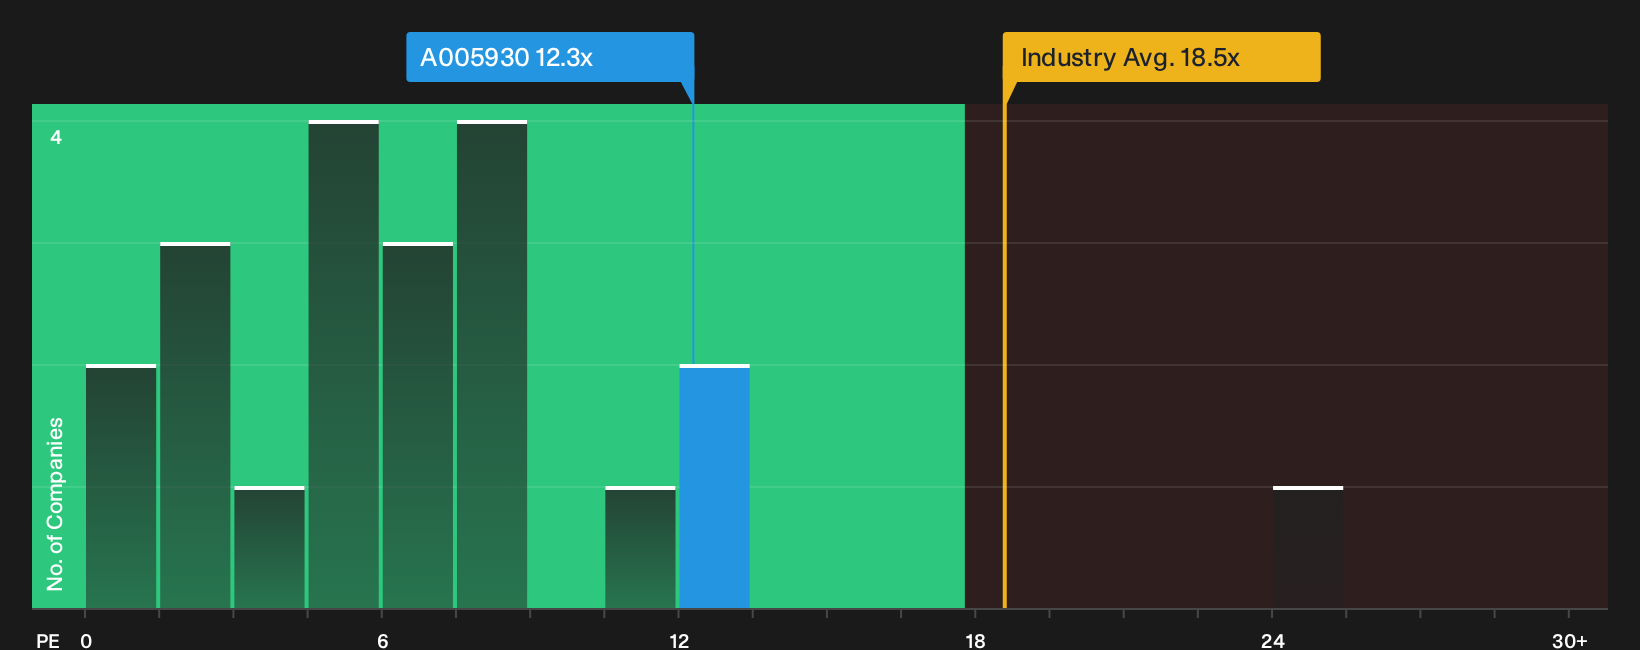
The P/E ratio is a simple way to check how much you are paying for each unit of profit at a company like Samsung Electronics. On this measure, the stock trades on about 12.3x earnings, which is well below the wider Tech industry average of roughly 19.3x and also far under the peer group sitting near 56.7x.
A fair P/E based on Samsung Electronics’ own growth profile, margins, size and sector risk screens higher than where the shares trade today. This points to the current multiple being on the undervalued side of that yardstick. That gap suggests the market is pricing the business on a materially lower earnings multiple than the model would expect for a group with Samsung Electronics’ characteristics. You would need to decide whether its cycle exposure, capital intensity or other risks justify that markdown before leaning on the discount too heavily. Explore the numbers behind Samsung Electronics's P/E valuation.
The Samsung Electronics Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Samsung Electronics pick up where the valuation puzzle leaves off by spelling out which combinations of future growth, profitability and earnings outcomes would need to play out for the stock to be worth materially more or materially less than today’s price, based on community assumptions. Each narrative ties a fair value to a specific chain of potential catalysts and risks for Samsung Electronics' business, so you can track over time which storyline appears to be taking shape.
Community views on Samsung Electronics are split between those who see more upside left in the story and those who think most of the good news is already in the price.
Bull case: 50% undervalued
"Samsung's competitors like TSMC, SKHY, MU, and INTC are not capable of what Samsung can..."
Discover why this Narrative puts Samsung Electronics at 50% undervalued.
Bear case: roughly fairly valued
"Since 1996 there have been six completed memory booms. All six died, each within roughly two years..."
Explore why this Narrative puts Samsung Electronics at roughly fairly valued.
The Samsung Electronics share price is only one piece of your decision
Valuation anchors what you pay today, but the analysts who model Samsung Electronics a few years out offer a separate reference point that may either challenge or support your own expectations. Explore where analysts expect Samsung Electronics to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com