
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Lowered Earnings Outlook At Tractor Supply Stock Has Changed Its Investment Story
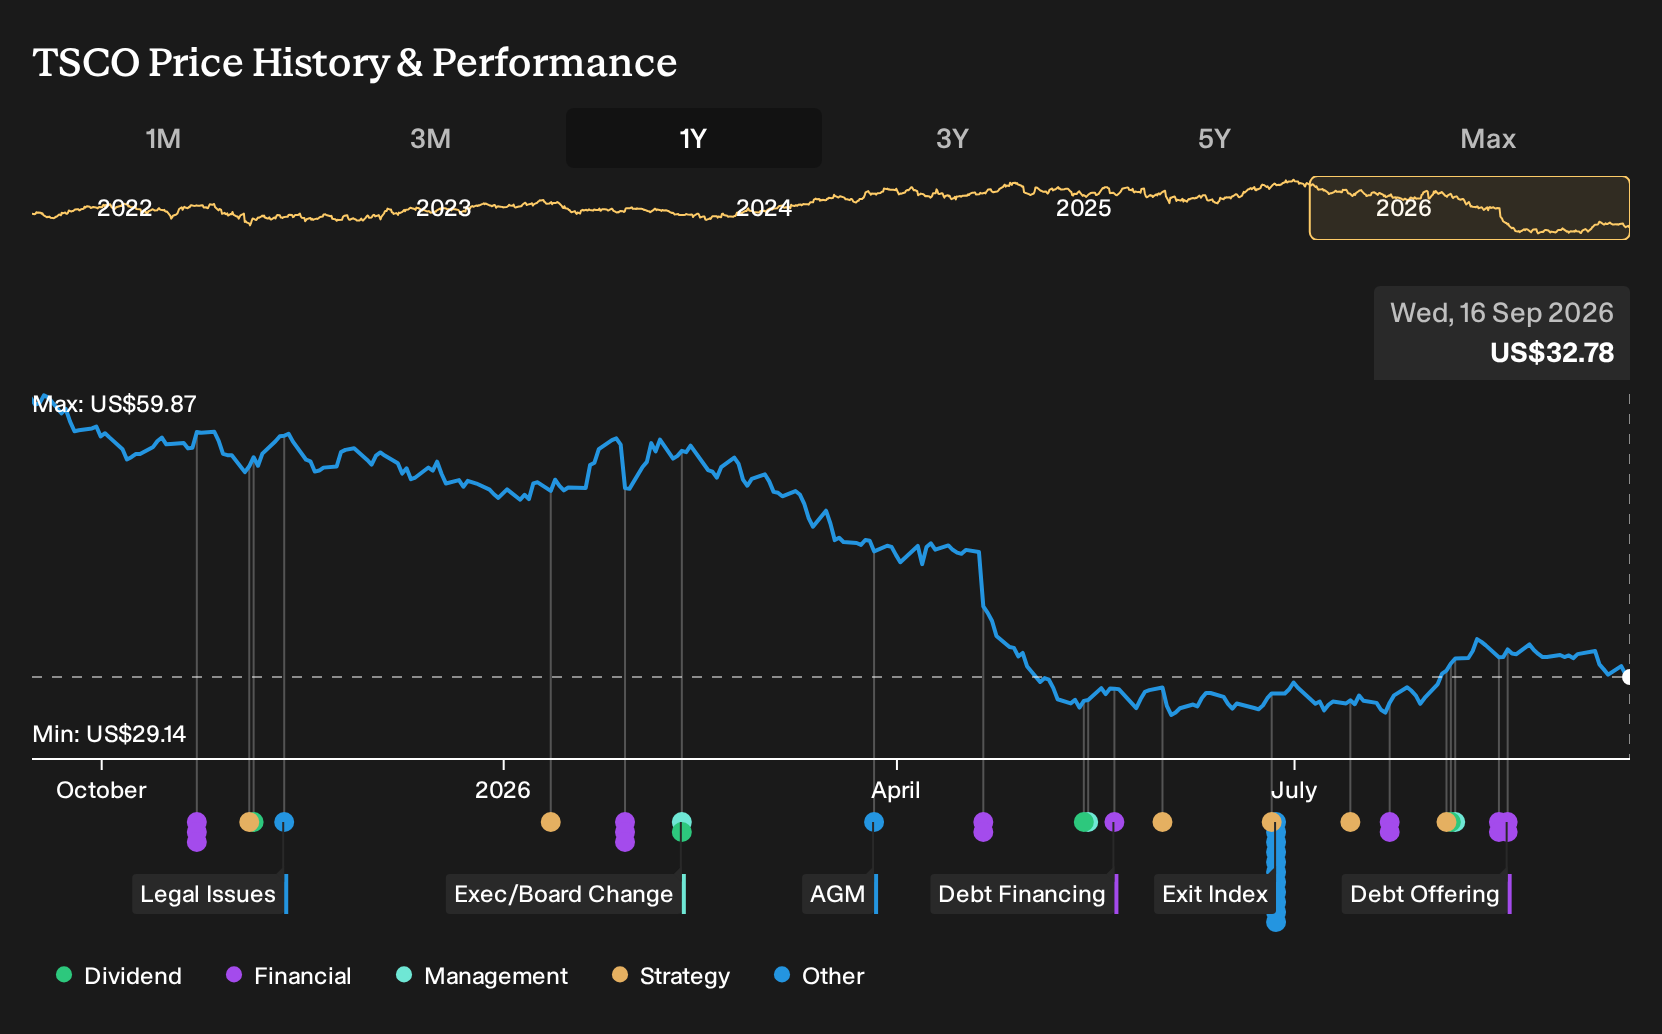
- Tractor Supply and its Petsense by Tractor Supply subsidiary recently reported softer second quarter results, weaker comparable store sales, and a reduced full year earnings outlook after scrapping a prior performance framework.
- These updates point to pressure on Tractor Supply's core store productivity and demand trends at the same time that new community programs, such as the K9s For Warriors round up campaign and the Starlink and 4 H connectivity partnership, aim to reinforce its rural and pet focused customer base.
- We will now look at how Tractor Supply's weaker comparable store performance could reshape the existing investment narrative for the business.
Pressure test Tractor Supply's recent pullback against a curated group of resilient retailers by scanning the 33 high quality undervalued stocks shaping the next wave of potential consumer rebound candidates.
Tractor Supply Investment Narrative Recap
To own Tractor Supply today, you need to believe its rural lifestyle focus and consumable mix can offset softer comparable store sales and pressure in big ticket categories. The near term hinge is whether management can stabilise traffic and ticket trends while keeping promotions and inventory under control.
The biggest risk right now is that weaker comps persist into future quarters, which could weigh on earnings and free cash flow at the same time as the business carries a meaningful debt load and a dividend not fully covered by free cash flow. Scrapped guidance raises execution risk if store productivity does not recover.
The 4 H and Starlink connectivity partnership is the announcement that ties closest to Tractor Supply's current challenges. It leans directly into the rural footprint and aims to make stores more relevant as a hub for essential services, not just discretionary spending, which matters when comparable store sales are under pressure.
For you, the question is whether programs like this can support traffic, especially among younger rural households, and help offset softer demand in weather sensitive and big ticket categories. The partnership could also reinforce Tractor Supply's community position, which may support customer retention if the broader consumer backdrop or tariffs continue to weigh on spending.
Analysts currently frame Tractor Supply's setup around revenue reaching about $18.0b and earnings of $1.2b by 2029, based on an assumed 4.6% yearly rise in sales and an increase in net income of roughly $0.2b from about $1.0b today.
Uncover how Tractor Supply's fair value points to an 8% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate read on Tractor Supply puts much more weight on pet category strain than on store remodels or weather. The most cautious analysts were working off revenue of about $17.4b and earnings of $1.1b by 2029, which is a much lower bar than consensus. Those projections all predate this latest guidance cut and community campaign news, so expect some views to shift.
Explore 5 other Tractor Supply fair value estimates, including one that suggests there could be as much as 15% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Tractor Supply research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tractor Supply. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tractor Supply's overall financial health at a glance.
Looking for more investment ideas beyond Tractor Supply?
Once you have a view on Tractor Supply, it can help to set it alongside other listed businesses with different income, risk, and balance sheet profiles. The Simply Wall St Screener lets you do that in a few clicks using ready made filters.
- Target steadier cash flows and payouts by using a pre built filter focused on dependable income payers through the 6 dividend fortresses.
- If capital preservation ranks high for you, compare Tractor Supply with companies that screen well on financial resilience through the 11 resilient stocks with low risk scores.
- For investors hunting for quality that is still off most radars, widen your search with the 16 high quality undiscovered gems and see which stocks merit a spot on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com