
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Trex (TREX) Stock Looks About Right On New Distribution Deal
Trex Company has seen its share price move around sharply in recent years, which puts fresh focus on a simple question for investors: whether the current US$43.11 price is supported by the earnings the business is producing today.
- Over the past 5 years the stock has fallen about 60.0%, which puts pressure on the case that the existing earnings profile can support a much higher valuation than the market was willing to pay in the past.
- The new distribution agreement with BlueLinx can widen Trex Company's reach in key U.S. markets, which may influence expectations for future earnings growth and the timing of cash flows from its decking and railing portfolio.
- The analysts covering Trex Company have run their own numbers. See what analysts think Trex Company's shares could be worth.
The issue now is whether Trex Company's current share price lines up with what its earnings justify.
If you are questioning whether Trex Company's US$43.11 price is justified by its earnings, it can help to compare that same question across a wider set of 33 high quality undervalued stocks
Is Trex Company Fairly Priced on Earnings?
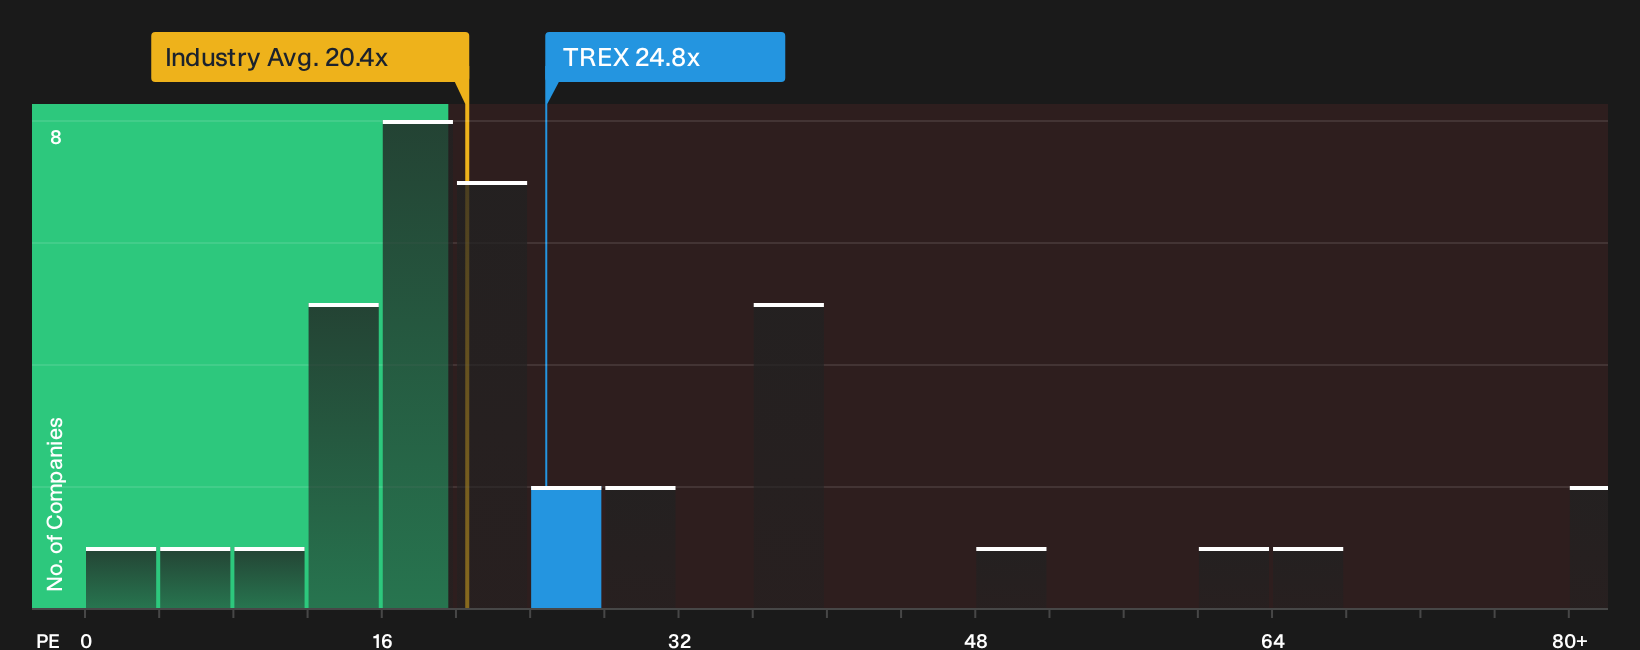
The P/E ratio is a useful lens for Trex Company because earnings are a key driver of how investors frame value for a mature building products business. At the current price, Trex trades on a P/E of about 24.8x. That sits above the broader building industry average of roughly 20.4x and below the peer group average near 38.9x, which places the stock between sector-level pricing and more highly rated comparables.
Based on the fair multiple that a valuation model estimates for Trex Company, which blends its growth outlook, profitability profile, size and risk, the current 24.8x P/E lines up closely with what that framework would suggest for the shares. Because the new BlueLinx distribution deal has sharpened focus on Trex's long term earnings potential, the market is already assigning a multiple that reflects some of that optimism without stretching far above the modelled range. Explore the numbers behind Trex Company's P/E valuation.
The Trex Company Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Trex Company pick up where the P/E puzzle leaves off and explain which paths for growth, margins and earnings would need to occur for the stock to be worth materially more or less than it is today. Each scenario anchors a fair value to a particular mix of potential catalysts and key risks so you can track over time which version of Trex Company's story is actually unfolding on the Community page.
One of the top community narratives on Trex Company: 21% undervalued
"Rising demand for eco-friendly materials and product innovation is strengthening Trex's market position and supporting revenue and margin growth."
Discover why this Narrative puts Trex Company at 21% undervalued.
Trex Company’s valuation still hinges on who is steering the ship
Price and earnings only tell part of the story for Trex Company, because the people directing capital and the way their pay is structured can heavily influence what happens next. See who runs Trex Company and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com