
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors Are Reacting To Advanced Drainage Systems (WMS) Capital Spending Tailwind
- UBS recently highlighted Advanced Drainage Systems as one of 10 industrial companies that could benefit from a broader capital-spending cycle, pointing to construction activity as a potential demand driver for its water management products.
- The report frames Advanced Drainage Systems as a possible beneficiary of increased infrastructure and construction investment, which would directly intersect with its focus on thermoplastic pipe, stormwater management systems, and related drainage solutions.
- We will now explore how this capital-spending tailwind for construction activity could influence Advanced Drainage Systems' existing investment narrative.
Scan for other potential beneficiaries of increased infrastructure investment by checking the hand picked 38 power grid technology and infrastructure stocks, which may complement your view on Advanced Drainage Systems and the broader capex cycle.
Advanced Drainage Systems Investment Narrative Recap
To own Advanced Drainage Systems, you need to be comfortable with a construction cycle that can stay choppy while still supporting long run demand for stormwater and wastewater solutions. The key near term swing factor is how residential, non-residential, and infrastructure projects actually convert into pipe and system orders, given management has previously flagged a flattish backdrop.
UBS pointing to a broader capex cycle reinforces that end market spending could help, but it does not remove the biggest immediate risk. A prolonged soft patch in new project starts or delayed infrastructure outlays would pressure volumes, especially if resin and other input costs move against the business at the same time.
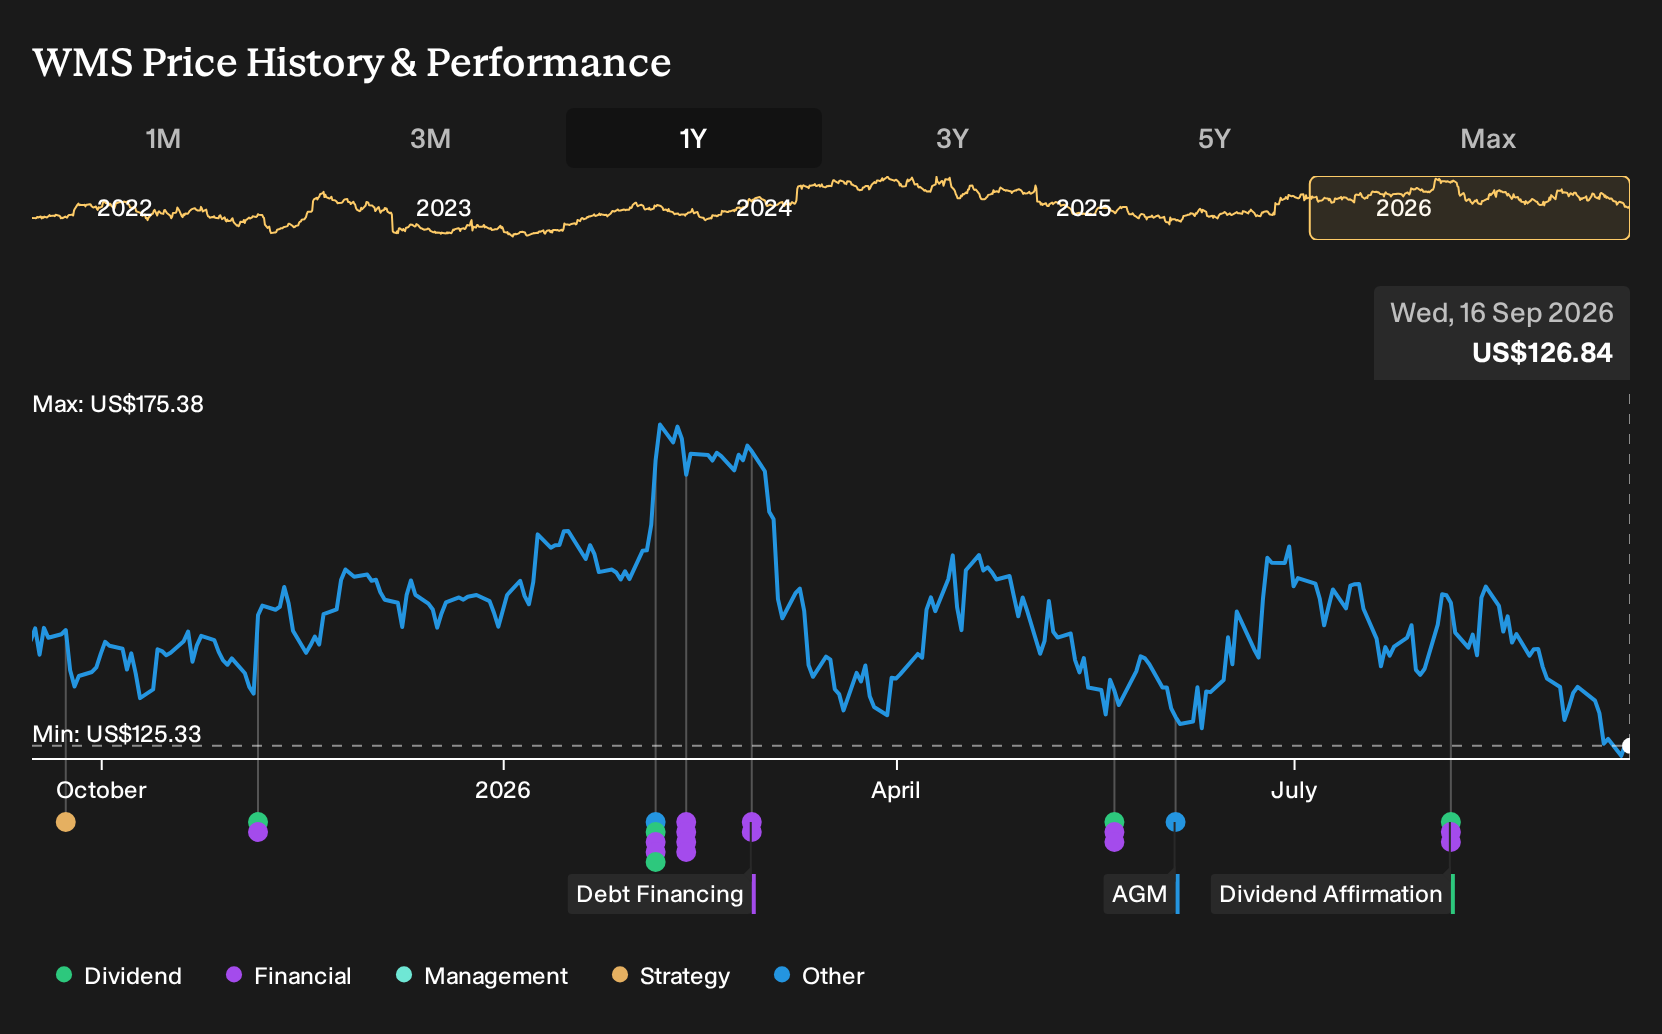
UBS highlighting Advanced Drainage Systems as having significant implied upside sits against a backdrop of mixed recent share performance. The stock is down 15.2% year to date and 9.3% over the past year. Analysts currently forecast earnings growth of 14.19% per year, and they report that earnings have grown 11.4% annually over the past 5 years.
That disconnect between price action and analyst expectations makes the UBS call most relevant as a sentiment and attention catalyst rather than an operational turning point. For you, the useful takeaway is to test whether the capex and construction argument is strong enough to offset risks around debt levels, raw material costs, and a demand profile that management has previously described as uneven.
Advanced Drainage Systems is framed around analysts’ expectations that revenues could reach about $3.9b and earnings $674.0 million by 2029, based on an assumed 8.5% yearly revenue growth rate and an earnings increase of roughly $246 million from the current $427.6 million figure.
Uncover why Advanced Drainage Systems' fair value indicates a 43% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community cluster tightly between about $169 and $181, which contrasts with UBS flagging a 62% implied upside for Advanced Drainage Systems after its capex call. That gap underlines how widely opinions can differ. Use it as a prompt to explore several alternative viewpoints before forming your own stance.
Explore another Advanced Drainage Systems fair value estimate, including one that suggests as much as 43% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Advanced Drainage Systems research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Advanced Drainage Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Advanced Drainage Systems' overall financial health at a glance.
Looking for more investment ideas beyond Advanced Drainage Systems?
If the UBS call has prompted you to reassess Advanced Drainage Systems, it can be useful to widen the lens and compare it with other opportunities that share similar qualities or offer diversification. The Simply Wall St Screener lets you do that quickly by filtering for financial traits that match your own risk and return preferences.
- If capital preservation matters most to you, start with companies that score well on stability and balance sheet strength by scanning a 11 resilient stocks with low risk scores that can help you focus on resilience first.
- If dependable income is a priority, look for established businesses with sizeable yields and payout histories by checking a curated set of 6 dividend fortresses that may complement Advanced Drainage Systems in a portfolio.
- If you prefer to look for mispriced quality, focus on companies with solid fundamentals trading below what the data suggests by reviewing a 16 high quality undiscovered gems that highlights lesser known opportunities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com