
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Atlas Copco (OM:ATCO A) Fairly Valued As It Builds Its New U.S. Service Hub?
What Atlas Copco’s New U.S. Service Hub Could Mean For Investors
Atlas Copco (OM:ATCO A) has started construction on a 355,000 square foot North American Service Center in Lancaster County, South Carolina, a long term logistics and customer support investment.
Atlas Copco’s share price has pulled back recently, with a 7 day share price return of 4.09% and a 30 day share price return of 5.80%. The year to date share price return sits at 16.69% and the 1 year total shareholder return is 29.59%. This suggests momentum has cooled in the short term, while longer term holders have still seen solid gains as the market weighs new projects like the U.S. service hub against changing expectations for future execution and risk.
Scan other industrials building out logistics and automation capacity by reviewing our hand picked 38 robotics and automation stocks alongside Atlas Copco’s latest U.S. service hub move.
Atlas Copco trades close to some fair value estimates while sitting about 12% below the average analyst target, and the new South Carolina hub adds another layer to weigh. Is the current discount cautious or is it mispriced?
Most Popular Narrative: 10% Undervalued
On the most followed narrative, Atlas Copco’s fair value sits at SEK218.48 against a last close of SEK195.75. This frames the new U.S. service hub as part of a broader capex upswing story rather than a one off project.
Sustained investments in product innovation including AI-driven efficiency in compressors and launches like the new GHS pump VSD+ position Atlas Copco to benefit from ongoing shifts toward automation, energy efficiency, and digitalization in industrial and infrastructure markets, enhancing long-term revenue growth and supporting premium pricing power.
See why 30 investors see Atlas Copco as 10% undervalued.
Result: Fair Value of SEK218.48 (UNDERVALUED)
Still, the Atlas Copco story can change quickly if currency swings continue to squeeze margins or if large compressor and Gas & Process orders remain subdued for longer.
Find out about the key risks to this Atlas Copco narrative.
Another View: Atlas Copco’s Rich Valuation On Earnings
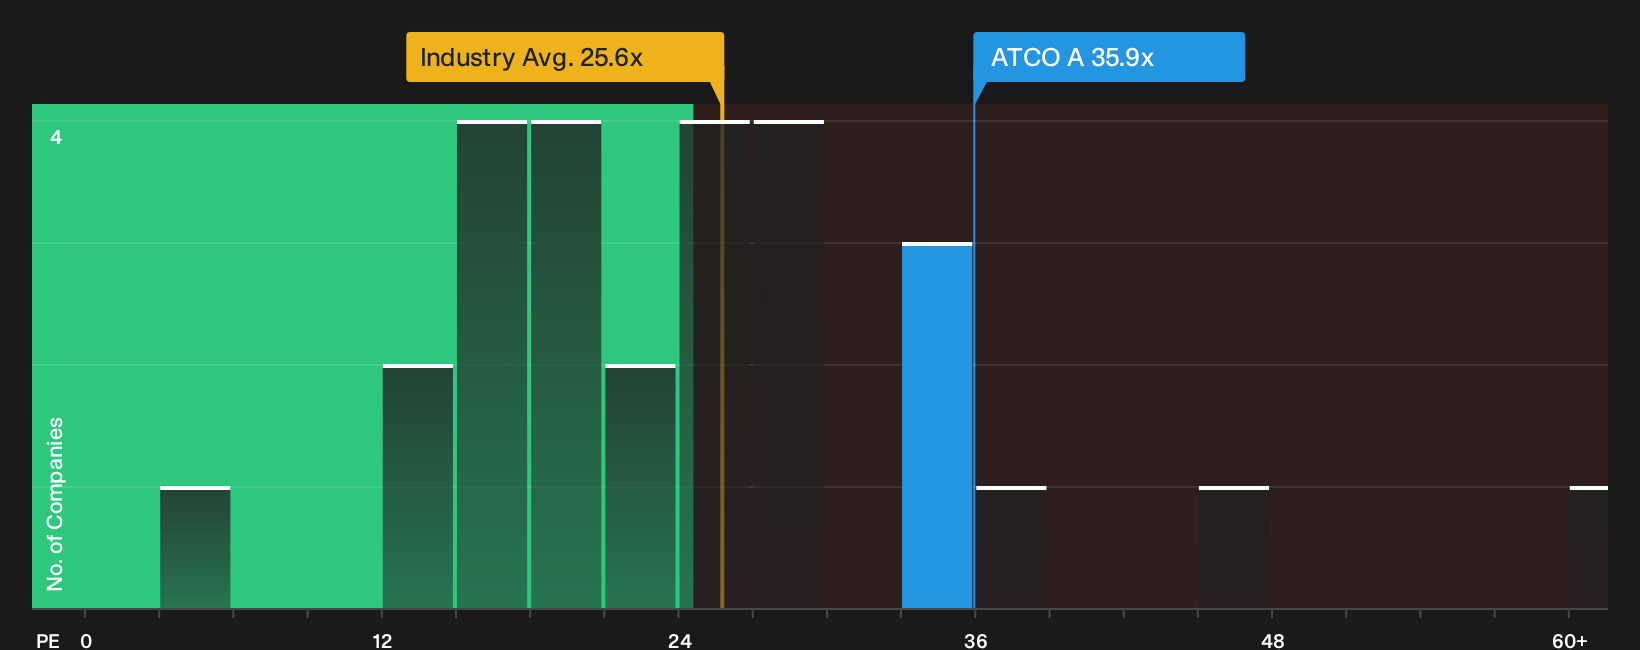
The SWS DCF model points to only a small 0.2% discount to fair value for Atlas Copco at SEK195.75 against a future cash flow value of SEK196.06, yet the market is paying a P/E of 35.9x. That is higher than both the Swedish Machinery industry on 24.5x and peers at 27.3x, and even slightly above the 35.8x fair ratio.
Paying that kind of premium can work if the growth and margins arrive as expected, but it leaves less room for disappointment if earnings or sentiment cool. Is that a risk you are comfortable underwriting at today’s price, or does it nudge Atlas Copco into the “wait and verify” bucket for you?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Atlas Copco is split, which is exactly when doing your own homework matters most. Move quickly, stress test the numbers, and pressure check the thesis against the 2 key rewards
Looking For More Atlas Copco-Sized Ideas?
If Atlas Copco has you thinking harder about pricing, quality, and risk, the next smart step is to widen your opportunity set before the market moves first.
- Target resilient income by scanning companies that aim to combine higher yields with staying power using our 162 dividend fortresses.
- Hunt for pricing gaps where business quality and balance sheets look stronger than the current valuation suggests through the 184 high quality undervalued stocks.
- Track sturdier balance sheets and cleaner fundamentals that can help limit downside shocks with our list of solid balance sheet and fundamentals (194 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com