
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Earnings Upgrades Change HF Sinclair (DINO) Stock Narrative
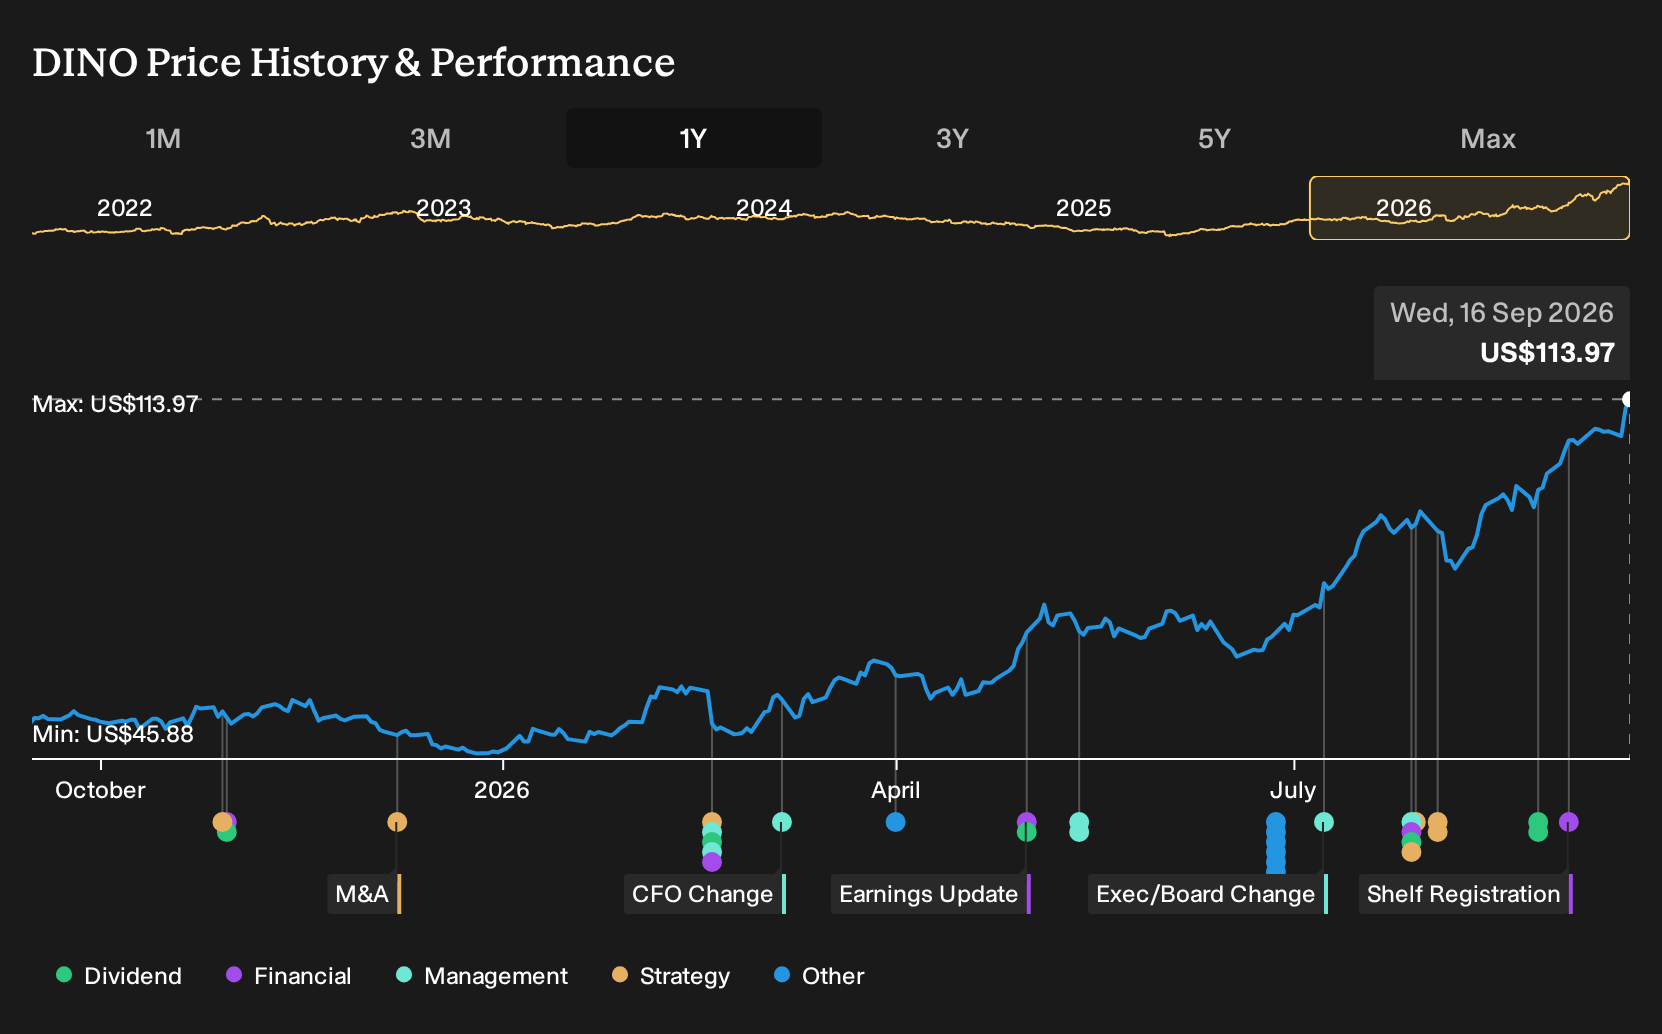
- HF Sinclair has seen upward revisions to earnings estimates in recent months. This has reinforced the market’s focus on the refiner’s underlying profit engine, cost discipline and demand trends rather than short term trading factors.
- The combination of stronger earnings expectations and a favorable Zacks Rank has put extra attention on how effectively HF Sinclair converts refining and marketing conditions into consistent cash generation.
- The focus now turns to how this shift in earnings expectations could influence HF Sinclair's broader investment narrative and appeal.
Ride HF Sinclair's earnings momentum theme by sizing up other refiner heavyweights and cash generators in our curated list of 33 high quality undervalued stocks.
What Is HF Sinclair's Investment Narrative?
To own HF Sinclair, you need to be comfortable with a refiner that lives and dies by execution on complex, capital intensive assets and the ebb and flow of fuel pricing. This is a business built around large refineries, midstream pipes and marketing channels across the Mid Continent, Rocky Mountains and West, with all the fixed cost weight that comes with that. The recent share price strength and upward earnings revisions simply put a brighter spotlight on how consistently those plants run, how well management controls unit costs and how effectively the mix across Refining, Renewables, Lubricants and Marketing turns regional demand into cash.
In the short term, the big swing factors remain refining margins, reliability at key sites and how much capital HF Sinclair has to pour back into maintenance, environmental projects and growth. Forecasts today still point to earnings and revenue declining over the next three years, so the latest estimate upgrades look more like a recalibration than a clean new growth leg. That tension between a strong recent run, a low P/E versus many peers and expectations for lower profits keeps risk tightly tied to execution and capital allocation discipline rather than just market mood.
Even so, there is a less comfortable angle investors need to weigh before leaning too hard into that refining cash machine story, and it starts with ...
There's only one way to know the right time to buy, sell or hold HF Sinclair. Head to Simply Wall St's company report for the latest analysis of HF Sinclair's Fair Value.
Exploring Other Perspectives
For HF Sinclair, the sharpest contrast is demand risk. The most pessimistic analysts were already building in roughly 4.9% yearly revenue declines, with earnings drifting from about US$1.9b to US$859.0m by 2029. That is a very different story to today’s upbeat revisions, so treat this news as a chance to reassess both viewpoints.
Explore 4 other HF Sinclair fair value estimates, including one that suggests as much as 26% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your HF Sinclair research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for HF Sinclair. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate HF Sinclair's overall financial health at a glance.
Looking For More HF Sinclair Investment Ideas?
If HF Sinclair has you thinking more broadly about where to put fresh capital to work, the Simply Wall St Screener can help you line up a wider watchlist that fits your style, risk tolerance and income needs.
- If you want lower volatility and sturdier finances to anchor your portfolio, start by scanning a list of solid balance sheet and fundamentals (22 results) that can handle tougher conditions without stretching their balance sheets.
- For investors who care more about price paid versus quality received, sort through a 33 high quality undervalued stocks that combine resilient fundamentals with what may be conservative expectations baked into current quotes.
- Income focused investors who prefer being paid while they wait can review a curated 6 dividend fortresses that aim to pair higher yields with durable cash flows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com