
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Harmonic (HLIT) Faces A Fresh Valuation Test On Its Broadband Software Push
Harmonic (HLIT) is back in focus after unveiling its cOS SensAI software and preparing a broader broadband technology showcase at two September industry events, putting fresh attention on how the business is repositioning around data driven connectivity.
Despite the product push, Harmonic’s share price has slipped recently, with a 30-day share price return down 16.98% and a 90-day share price return down 26.06%. This comes even though the year-to-date share price return is 11.28% and the 1-year total shareholder return is 11.17%, signalling fading short-term momentum against a still positive multi-year total shareholder return profile of 16.88% over three years and 25.42% over five years.
Compare Harmonic’s broadband pivot with other data driven infrastructure plays by scanning our hand picked 60 AI infrastructure stocks that are already building the next layer of connectivity.
After a sharp pullback and a louder broadband story, Harmonic now asks a simple question of investors: Does the current valuation still leave enough upside to justify the risks being taken on?
Most Popular Narrative: 27% Undervalued
Harmonic’s most followed valuation storyline pegs fair value at $15.29 per share, well above the last close of $11.15. This sets a clear gap that hinges on how broadband orders and margins play out from here.
Analysts are assuming Harmonic's revenue will grow by 15.3% annually over the next 3 years. Analysts assume that profit margins will increase from 2.1% today to 15.1% in 3 years time.
See why 17 investors see Harmonic as 27% undervalued.
Result: Fair Value of $15.29 (UNDERVALUED)
Still, Harmonic’s reliance on a few large broadband customers and the risk of slower SaaS adoption could quickly challenge that 27% undervalued narrative.
Find out about the key risks to this Harmonic narrative.
Another View: Harmonic Looks Expensive On Earnings
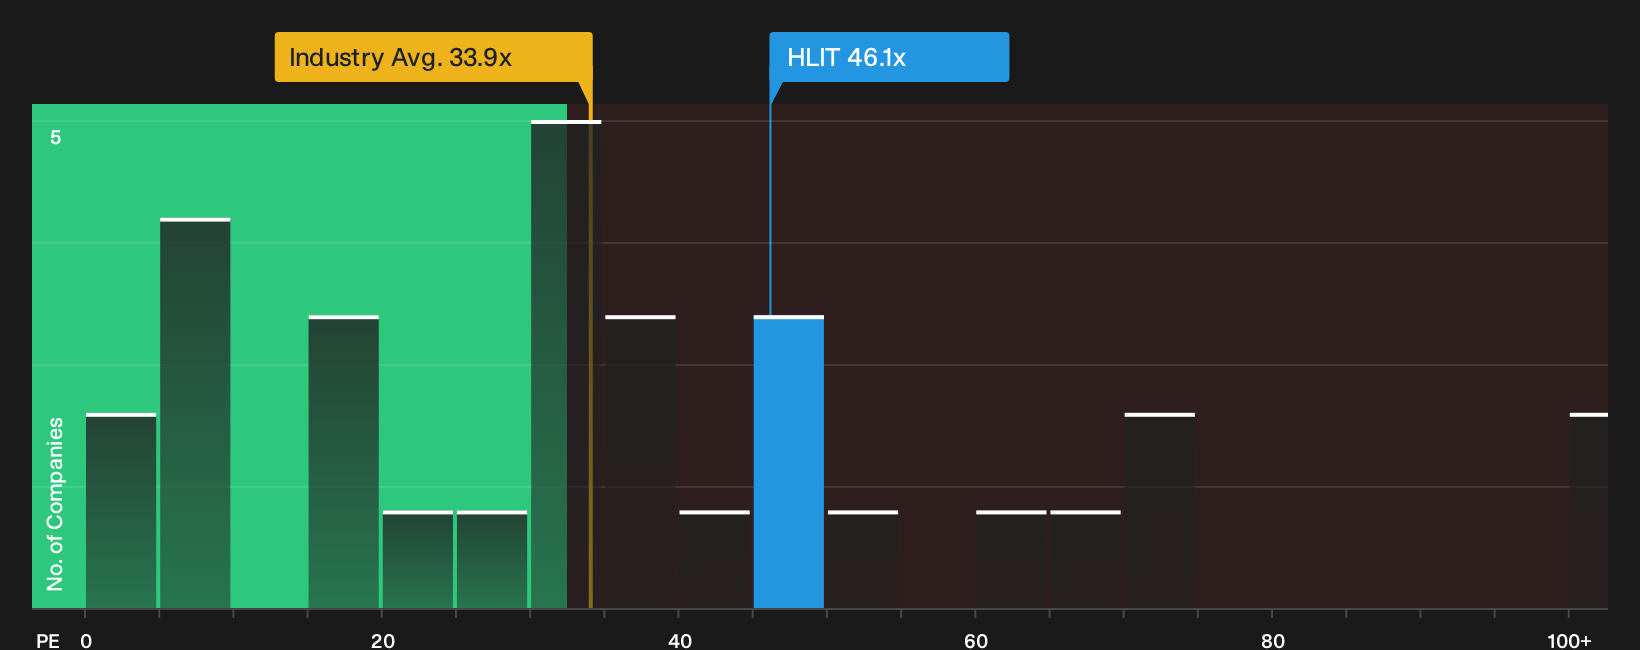
The story changes once the focus shifts from cash flows to earnings multiples. Harmonic trades on a P/E of 46.1x, while the fair ratio is 33.6x, the US Communications industry sits at 33.9x, and peers average 37.6x. That richer pricing narrows the margin of safety. Is the broadband narrative strong enough to keep investors comfortable with that premium?
To see how this earnings based view fits alongside cash flow assumptions and price targets, take a closer look at the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around Harmonic is split, which means the opportunity and the risk are both live right now. Move quickly, review the data for yourself, and weigh the 2 key rewards and 1 important warning sign.
Looking for more Harmonic sized investment ideas?
If Harmonic has your attention, do not stop here. Broaden your watchlist with fresh angles that could sharpen your overall portfolio decisions.
- Target potential mispricing by scanning a curated 33 high quality undervalued stocks that already filters for quality alongside attractive valuations.
- Lock in income focused opportunities by reviewing a focused 6 dividend fortresses built around higher yield payouts.
- Reduce portfolio stress by concentrating on a 11 resilient stocks with low risk scores that highlights companies with more resilient risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com