
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How New Philadelphia Hub At Bentley Systems (BSY) Has Changed Its Investment Story
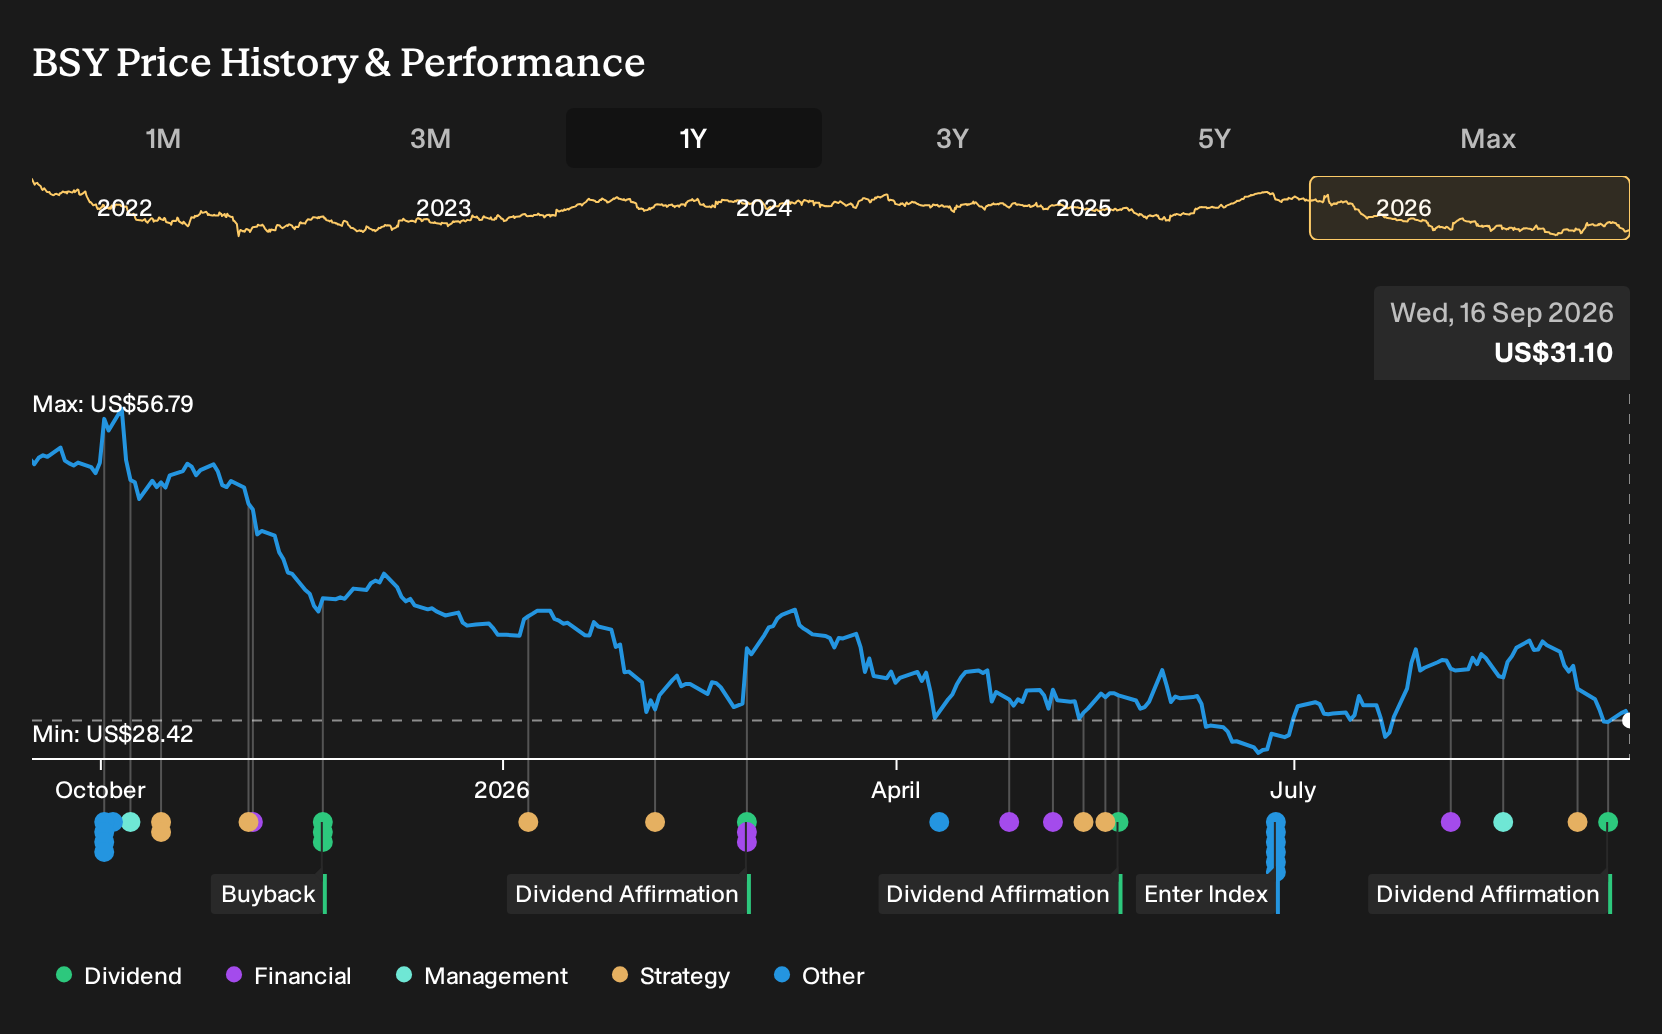
- Bentley Systems declared a US$0.07 per share third quarter 2026 dividend, payable on 29 September 2026 to Class A and Class B stockholders of record on 22 September 2026.
- The new Curtis Center office in Center City, Philadelphia deepens Bentley Systems' investment in 3D digital twin and open geospatial technology around the Cesium and iTwin platforms.
- We will now explore how Bentley Systems' new Philadelphia technology hub could influence the broader investment narrative around its infrastructure software.
Bentley Systems Investment Narrative Recap
To own Bentley Systems, you need to believe that infrastructure owners will keep shifting more design, construction, and asset management work into software platforms like MicroStation, ProjectWise, AssetWise, Cesium, and iTwin. The near term swing factor is whether subscription and consumption based revenue can stay resilient while the firm absorbs higher R&D and cloud costs tied to AI and digital twins.
The fresh US$0.07 dividend for the third quarter of 2026 signals management’s comfort returning cash while carrying a relatively high debt load and funding ongoing investment. This payout does not materially change the main risk today, which is that slower than expected revenue growth or pricing pressure could weigh on margins and challenge the current valuation.
The Curtis Center technology hub in Philadelphia sits closest to the real operational story. It concentrates Bentley Systems’ developer ecosystem around Cesium and the iTwin Platform, which are central to its push into 3D digital twins and geospatial workflows that can support higher value, data rich subscriptions.
If execution in this new hub goes well, it can strengthen Bentley’s position in asset analytics and long term infrastructure projects. Analysts already tie these areas to revenue and earnings growth expectations. If adoption of these platforms lags, or if competitors and open standards advance faster, the expanded footprint could simply add cost and make it harder to reach the profit and cash flow targets currently implied in forecasts.
Bentley Systems' narrative projects US$2.1b revenue and US$508.3 million earnings by 2029, based on the provided assumptions. This assumes 11.3% yearly revenue growth and an earnings increase of about US$226 million from current earnings of US$281.9 million.
Discover why Bentley Systems' fair value suggests a 45% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
One alternate view on Bentley Systems leans hard into the risk that open source standards take more share. Those cautious analysts were pencilling in about US$2.2b of revenue and US$489.4 million of earnings for 2029, with a lower US$37.0 price target, well before this Philadelphia hub and dividend news landed. It is worth comparing both narratives yourself.
Explore 2 other Bentley Systems fair value estimates, including one that suggests it could be worth just $45.07!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Bentley Systems research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bentley Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bentley Systems' overall financial health at a glance.
Looking For More Ideas Beyond Bentley Systems?
If the Bentley Systems story has you thinking about where digital infrastructure goes next, it can help to line it up against other businesses with different strengths and risk profiles. The Simply Wall St Screener lets you do that quickly by filtering for traits that match the kind of portfolio you want to build.
- If you want a focus on quality at a discount, start with companies that pass strict value and fundamentals filters using the 33 high quality undervalued stocks.
- For investors who care most about balance sheet strength, scan for businesses with robust finances and clean leverage profiles through the list of solid balance sheet and fundamentals (22 results).
- If you prefer to get paid while you wait, look for income ideas with higher yields and resilient cash payouts via the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com