
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Beam Therapeutics (BEAM) Undervalued Following Its BEAM 302 Clinical Update?
Beam Therapeutics (BEAM) drew fresh attention after releasing updated Phase 1/2 data for BEAM-302 in alpha-1 antitrypsin deficiency, highlighting safety, biomarker gains, and supportive FDA feedback on a potential accelerated approval path.
For Beam Therapeutics, that clinical update landed after a rough patch for the share price, with the 30-day share price return down 14.8% and the 90-day share price return down 32.3%, while the total shareholder return over the past year sits modestly in positive territory at 2.9%.
Spot 16 high quality undiscovered gems that, like Beam Therapeutics after this BEAM-302 update, pair ambitious science with clear clinical catalysts already in motion.Beam Therapeutics now trades far below the average analyst target after this BEAM-302 update. Is that a genuine discount, or is the market correctly pricing the clinical and cash burn risks ahead?
Most Popular Narrative: 55% Undervalued
Beam Therapeutics last closed at $23.10, while the most followed narrative anchors fair value closer to $51.07. This perspective puts a lot of weight on how its gene editing platforms and regulatory path play out over the next few years.
The development of ESCAPE technology aims to expand the addressable patient population for gene editing by eliminating chemotherapy, which could significantly increase the market and, subsequently, revenue and margins. Beam has nominated BEAM-103 and BEAM-104 for their ESCAPE program, which could bring transformative changes in transplant medicine by enabling non-genotoxic conditioning, leading to broader patient access and a potential increase in revenue.
See why 59 investors see Beam Therapeutics as 55% undervalued.
Result: Fair Value of $51.07 (UNDERVALUED)
Still, the Beam Therapeutics story can break if busulfan safety issues persist or if ongoing funding needs force heavier dilution than analysts currently model.
Find out about the key risks to this Beam Therapeutics narrative.
Another View: Beam Therapeutics Through A Sales Lens
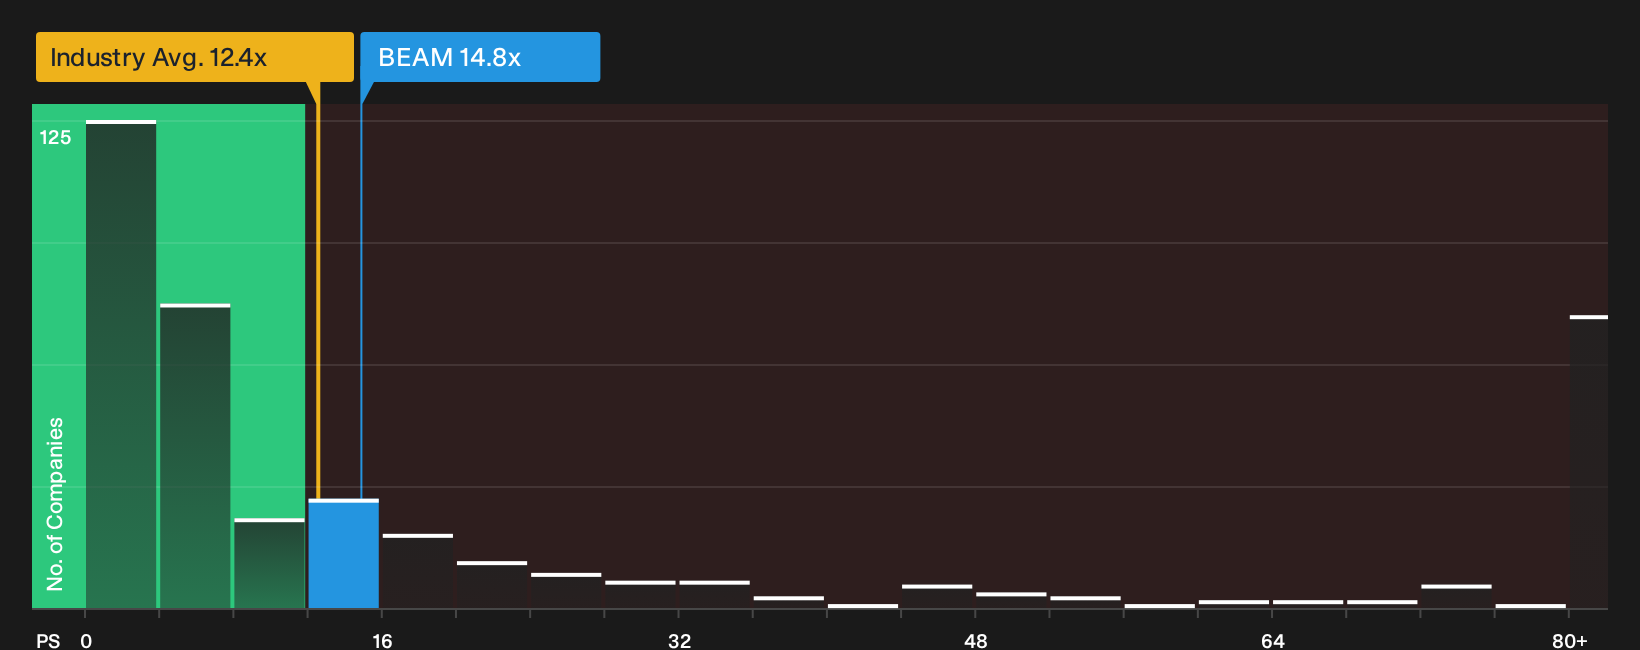
The fair value narrative pegs Beam Therapeutics near $51.07, yet the share price already implies a rich valuation on sales. The stock trades on a P/S ratio of 14.8x, versus 12.5x for the US Biotechs group and a fair ratio of just 0.6x, which points to valuation risk if sentiment cools.
The gap between the current 14.8x and a fair ratio of 0.6x is wide enough that investors need to ask what has to go right, and for how long, for the market to keep paying such a premium.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Beam Therapeutics so far. If you want to move fast and evaluate the balance of promise and risk for yourself, start by checking the 2 key rewards and 2 important warning signs.
Looking for more Beam Therapeutics sized opportunities?
If Beam Therapeutics has sharpened your focus, do not stop here. Use curated screeners to quickly surface other ideas that match your risk and return preferences.
- Target sturdier portfolios by lining up companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (22 results).
- Hunt for better value by scanning markets for potential mispricings using the 33 high quality undervalued stocks.
- Spot future standouts early by tracking lesser known quality opportunities in the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com