
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Seadrill (SDRL) Earnings Views Turn Positive, Is The Stock Still 9% Undervalued?
Analyst sentiment around Seadrill (SDRL) has shifted, with multiple firms raising their earnings estimates for the driller. That swing in expectations is the key storyline investors are reacting to.
Recent trading has been choppy. The share price slipped 3.86% in the last session to US$47.84, yet Seadrill still posts a 24.13% 3 month share price return and a 36.88% year to date share price return, alongside a 41.58% 1 year total shareholder return. This points to momentum building around the story.
Scan for other Seadrill style momentum stories and stress test this setup against a hand picked group of 33 high quality undervalued stocks.
Seadrill trades at a sizeable discount to both intrinsic estimates and analyst targets after that strong run. Is the market rightly cautious about offshore drilling risk, or mispricing the valuation gap that is now opening up?
Most Popular Narrative: 9% Undervalued
Against a last close of $47.84, the most followed Seadrill narrative pegs fair value at about $52.78, pointing to a modest discount that rests heavily on how the offshore cycle plays out and how management deploys future cash flows.
Restructured balance sheet, robust liquidity, and visible cash flow uplift from recontracting legacy rigs at materially higher dayrates position Seadrill for capital returns (e.g., buybacks/dividends) and more reliable free cash flow, which are likely to enhance both net margins and investor sentiment as the cycle turns.
See why 10 investors see Seadrill as 9% undervalued.
Behind that $52.78 marker sit some punchy assumptions. Analysts feeding into this Seadrill framework expect revenue to compound at about 6.8% a year and profit margins to move from roughly 0.1% today to 25.8%, with earnings modeled at $463.7 million by around August 2029 and discounted back using a 7.76% rate.
For those numbers to line up with the narrative fair value, the stock would be trading on a P/E of about 9x those 2029 earnings, which is below the 27.1x currently applied to the wider US Energy Services industry. That gap is where the 9% perceived undervaluation comes from rather than from current profitability, which is held down by one off items and a 0.07% net margin.
That leaves investors weighing a simple question around Seadrill: Do you think earnings can grow as modeled, margins can rise toward the high twenties, and management can convert a tighter ultra deepwater market into the kind of free cash flow that supports sustained capital returns?
Result: Fair Value of $52.78 (UNDERVALUED)
Still, softer utilization with tougher competition through 2026, along with ongoing legal and regulatory disputes in Angola and Brazil, could easily upset that Seadrill earnings path.
Find out about the key risks to this Seadrill narrative.
Another View On Seadrill Valuation
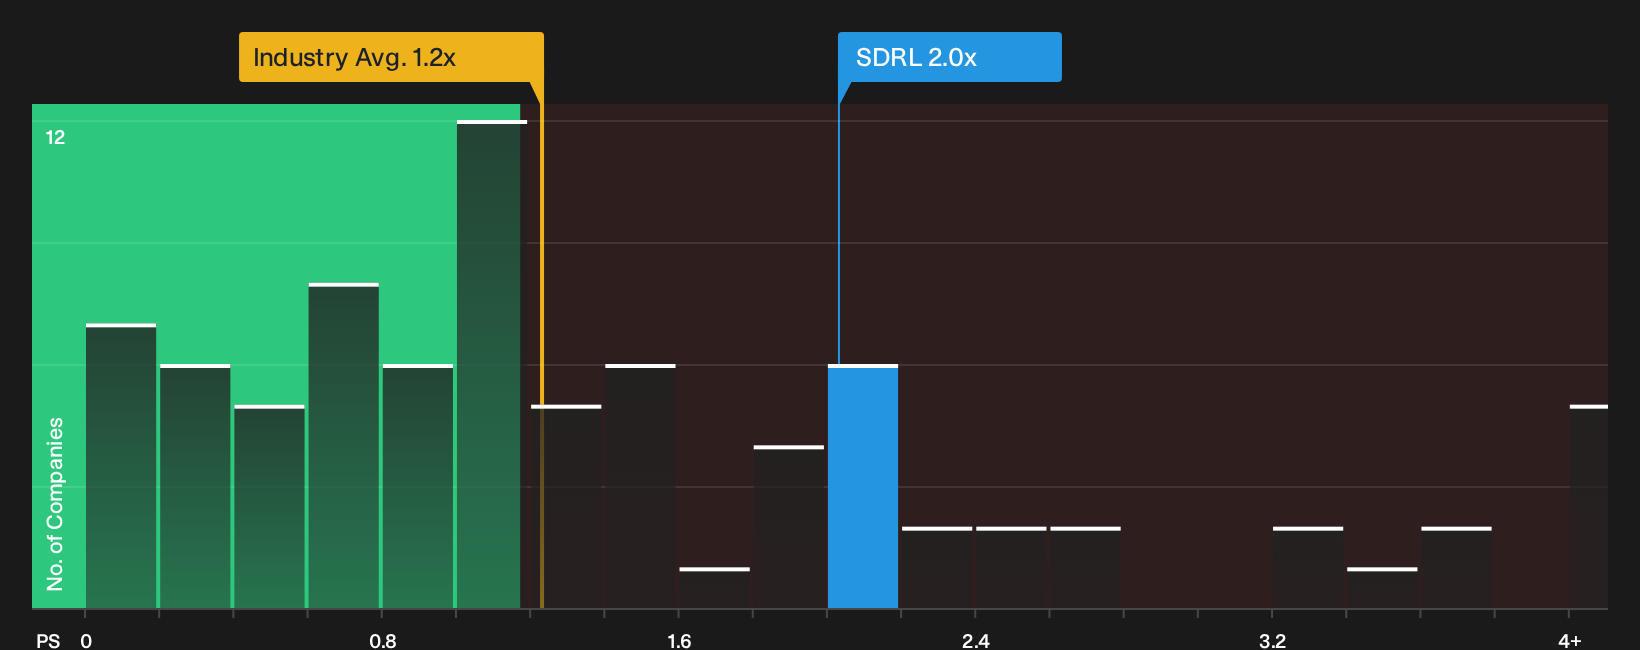
The story shifts when you stop looking at Seadrill through a future earnings lens and focus on what investors are paying for revenue today. On a P/S ratio of 2x, the stock trades above both the US Energy Services peer average of 1.3x and a fair ratio of 1.2x, which points to clear valuation risk if sentiment cools.
That kind of premium means the market already prices in a lot of the offshore drilling optimism, even though revenue is forecast to grow at 6.4% a year, which is slower than both 20% high growth thresholds and the wider US market at 13.3%. If that optimism fades, how comfortable are you owning a business that screens as both undervalued on future cash flows and expensive on sales today?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Seadrill valuation and risk are clear. Move fast, interrogate the numbers, and weigh both sides by checking the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Seadrill?
Do not stop with Seadrill. Broaden your watchlist now so you are not late to the next setup that matches your risk and return preferences.
- Hunt for resilient payout potential by scanning a focused group of income opportunities through 6 dividend fortresses.
- Zero in on resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (22 results).
- Uncover underfollowed opportunities with strong financial markers by working through a curated batch of 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com