
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
OMRON (TSE:6645) Could Be 49% Above Fair Value On Sysmac Studio Backup News
Copia Automation’s decision to support Omron (TSE:6645) Sysmac Studio projects gives manufacturers using NJ and NX-series controllers automated backups, version tracking, and rapid recovery. For investors, it raises fresh questions around ecosystem stickiness and long-term OT integration.
OMRON’s latest share price of ¥6,100 comes after a sharp 1‑month share price return that declined 10.95%. This is despite the year to date share price return of 52.65% and the 1‑year total shareholder return of 55.39%, so recent momentum looks softer than the longer trend.
See how OMRON compares with other automation and robotics plays by running your filters through a curated group of 38 robotics and automation stocks.
After a strong year to date rise but a softer recent patch, OMRON now sits at a different entry point. Does that reset tilt the risk reward toward fresh buyers or argue for more caution as valuation gets unpacked next?
Preferred P/E Multiple of 27.6x: Is It Justified?
Valuation on OMRON now leans heavily on what you think a quality automation player should trade at. The stock closed at ¥6,100, which lines up with a P/E of 27.6x that screens cheaper than close peers but richer than both its own fair ratio and the wider Japanese electronics group.
The P/E multiple measures how much you are paying for each unit of current earnings. For an automation and healthcare hardware producer like OMRON, it often reflects how markets weigh steady equipment demand, incremental software income, and the resilience of industrial capital spending cycles.
On one side, OMRON shows traits that many investors look for. Earnings grew 32.9% over the past year, high quality earnings are flagged, and profit margins of 5.4% are higher than the 4.1% level reported a year earlier. Forecasts point to earnings growth of 15.1% per year, ahead of the 8.8% figure for the broader JP market. Those factors can support a richer earnings multiple when investors believe that profitability and growth are on firmer footing after several weaker years, even if the 5 year earnings track record declined 23% per year.
The other side of the ledger is harder to ignore. The same 27.6x P/E that looks cheap versus a peer average of 40.2x is flagged as expensive relative to an estimated fair P/E of 21.7x, a level the market could move toward if sentiment cools. It is also described as expensive versus the JP Electronic industry average multiple of 16x, which suggests the stock carries a premium that markets are tying to its automation footprint and improving earnings profile rather than to sector-wide conditions.
Explore the SWS fair ratio for OMRON.
Result: Price-to-earnings of 27.6x (OVERVALUED).
Still, the long slide in 3 year and 5 year total returns, along with any disappointment in revenue or net income growth, could quickly challenge this richer P/E story for OMRON.
Find out about the key risks to this OMRON narrative.
Another View: What Our DCF Model Says About OMRON
The P/E story paints OMRON as expensive against a fair ratio of 21.7x, but the SWS DCF model goes further. On that approach, the share price of ¥6,100 sits above an estimated future cash flow value of ¥4,102.84, which points to an overvalued signal instead of a margin of safety. Does that gap reflect real overenthusiasm, or a market willing to pay up for resilience in automation and healthcare hardware?
Look into how the SWS DCF model arrives at its fair value.
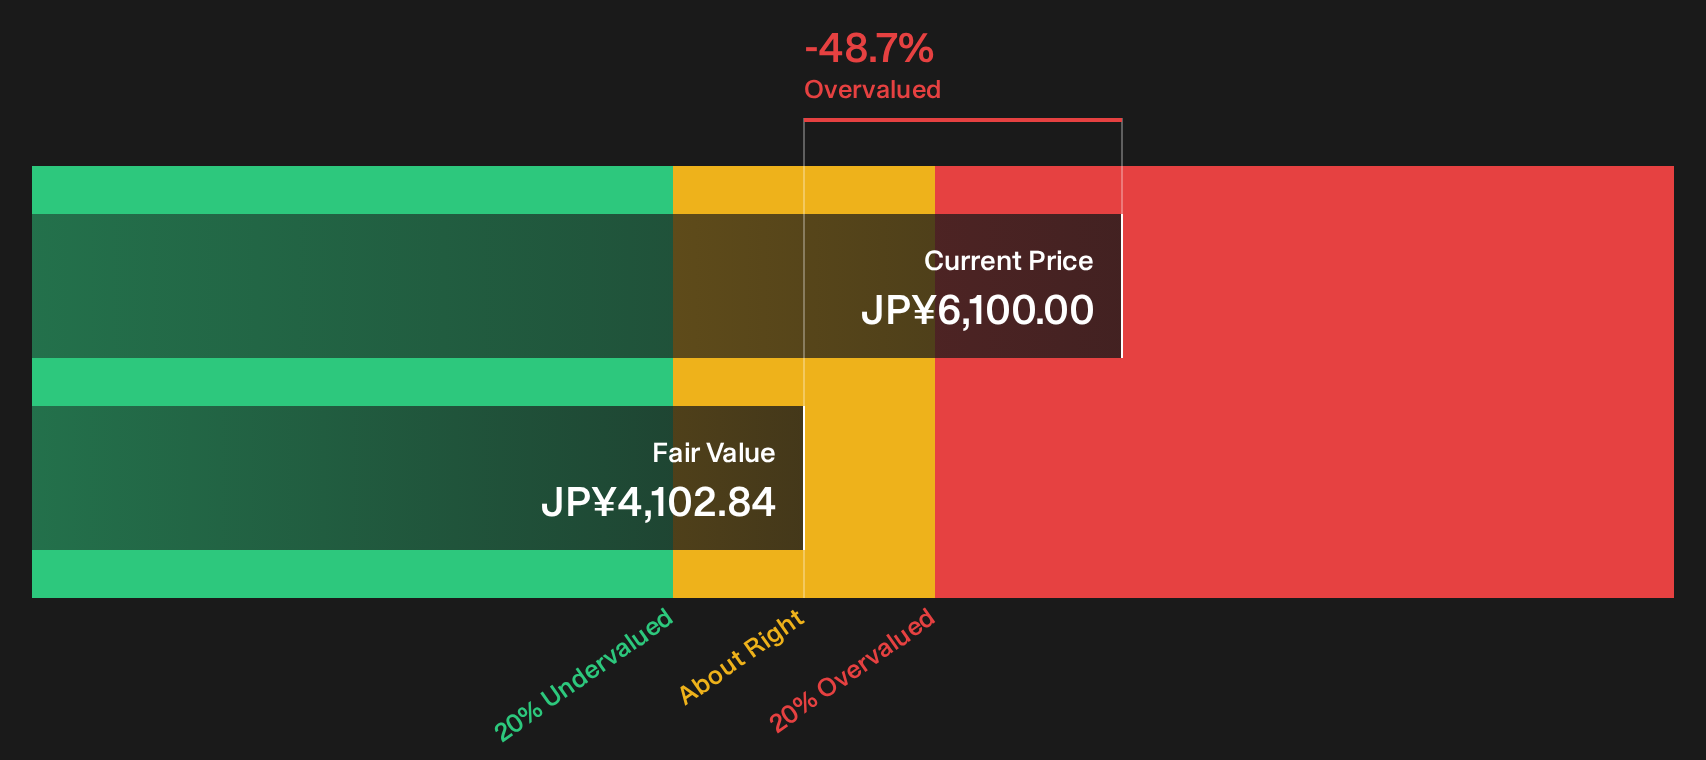
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out OMRON for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around OMRON's valuation and momentum only matter if you use them. Act while this information is fresh and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond OMRON?
If OMRON has your attention, do not stop with a single ticker. Use this momentum to refresh your watchlist with fresh opportunities that fit your style.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (20 results) that can help you sidestep fragile stories.
- Hunt for mispriced quality by running your criteria across 17 high quality undervalued stocks where strong businesses might be trading on more modest expectations.
- Build a stream of potential cash payouts by focusing on 15 dividend fortresses that prioritise higher yields along with stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com