
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Phillips 66 (PSX) Draws Earnings Optimism, Is The Stock Already Above Fair Value?
Phillips 66 (PSX) is back on investors’ radar after workers at its Bayway Refinery in New Jersey scheduled a contract rally, bringing potential labor costs and operational risks into sharper focus.
Recent trading shows how quickly sentiment around Phillips 66 has shifted, with a 30 day share price return of 10.01% building on a powerful 90 day climb of 59.28% and a year to date share price gain of 102.67% that has translated into a 1 year total shareholder return of 104.65%.
Scan refiners riding similar momentum and pricing debates as Phillips 66 by focusing on a curated set of 33 high quality undervalued stocks.
Phillips 66 has built a broad downstream energy platform, yet the share price surge and labor questions at Bayway put a sharper focus on something simpler. Are you now paying up for quality, or still getting a deal on it?
Most Popular Narrative: 27.5% Overvalued
Phillips 66 closed at $264.63, while the most followed narrative pegs fair value at $207.53. The current rally is running well ahead of that framework and puts extra weight on the cash generation story behind the stock.
Phillips 66 is executing on transformational growth opportunities like enhancing its NGL value chain and achieving growth in Midstream, which could drive revenue growth and earnings stability.
The company is improving its refining operations through low-capital, high-return projects, enabling better feedstock flexibility and yield, which can boost net margins.
See why 45 investors see Phillips 66 as 28% overvalued.
Result: Fair Value of $207.53 (OVERVALUED)
Still, the narrative can break if refining and renewable fuels margins weaken, or if higher turnaround and depreciation costs at Phillips 66 reduce the quality of earnings.
Find out about the key risks to this Phillips 66 narrative.
Another Take On Phillips 66 Valuation
The first view frames Phillips 66 as 27.5% overvalued versus a $207.53 fair value, based on analyst price targets. A second lens tells a very different story. The SWS DCF model estimates fair value at $497.41 per share, which puts the current $264.63 level at a large discount instead. Which lens do you trust more when real cash flows are on the line?
Look into how the SWS DCF model arrives at its fair value.
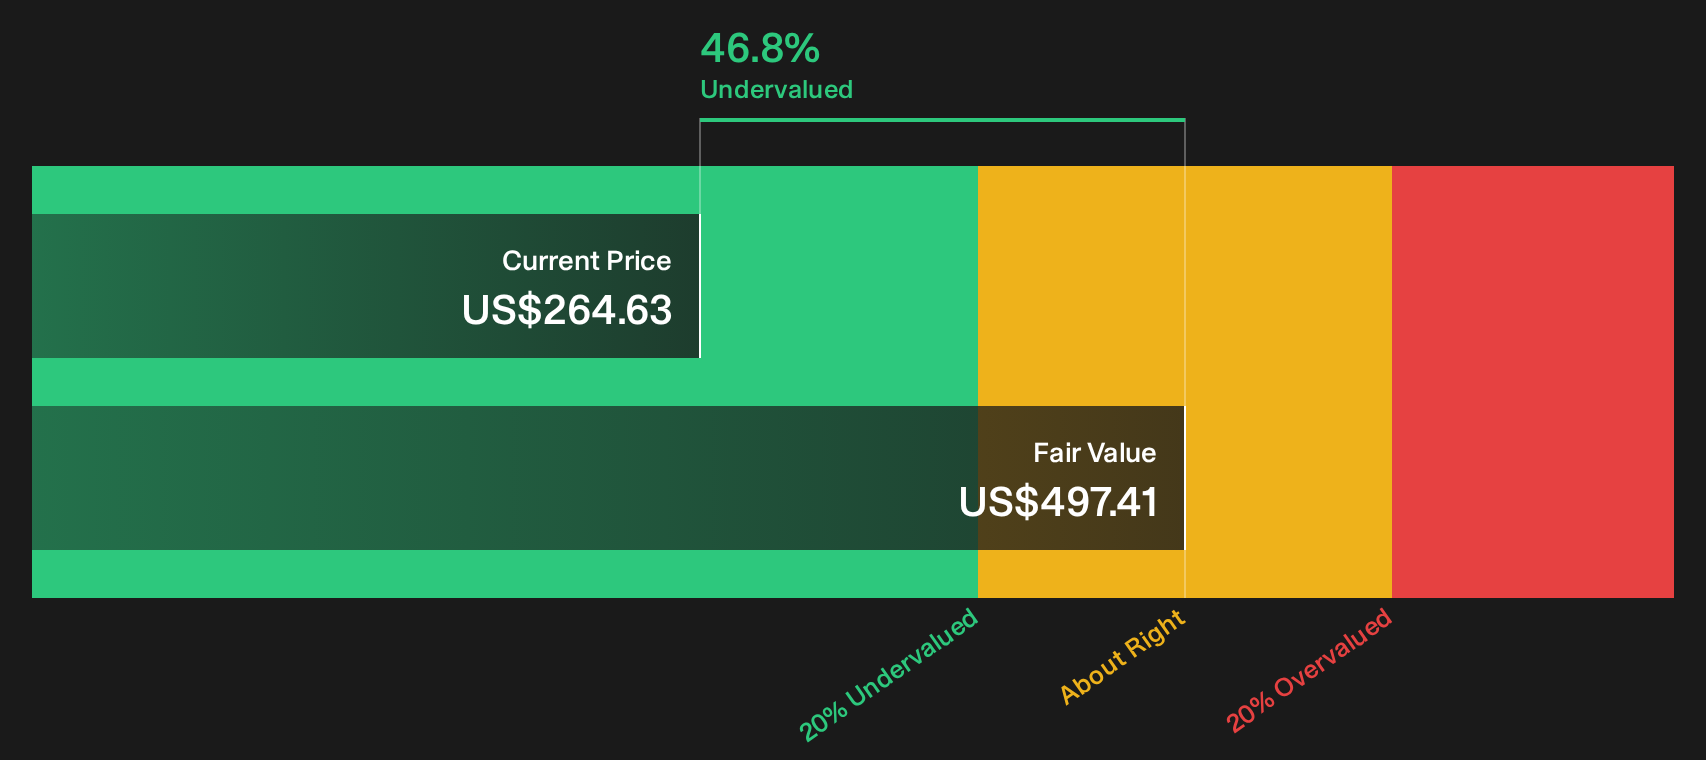
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Phillips 66 for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the cross current between optimism and caution around Phillips 66 feels sharp, that is the point; you are meant to wrestle with it. Move fast, test the numbers against your own expectations, and pressure check both the upside story and the weak spots by reviewing the 3 key rewards and 2 important warning signs.
Ready For More Ideas Beyond Phillips 66?
Do not stop your thinking with Phillips 66 when the real edge comes from lining it up against other high quality prospects on your radar.
- Target dependable income by zeroing in on companies that could sustain higher yields through a 6 dividend fortresses.
- Hunt for resilient businesses that pair solid finances with measured risk using the 11 resilient stocks with low risk scores.
- Spot future leaders early by scanning for quality companies that the market may be overlooking through a 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com