
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DTE Energy (DTE) Following Board Retirement The Fair Value Debate Remains
DTE Energy (DTE) moved into focus for investors after long-serving director David A. Thomas announced his retirement from the board on September 3, 2026, following 13 years of service.
DTE Energy now trades at US$130.70. The share price is down 7.4% over the past month and 11.4% over the past quarter, while the year-to-date share price return is slightly positive. The 3-year total shareholder return of 34.6% points to longer-term momentum that contrasts with the recent pullback as investors absorb this board transition alongside other company-specific developments.
Scan how DTE Energy’s recent pullback compares with other regulated utilities by reviewing our curated list of 11 resilient stocks with low risk scores.
That pullback now meets a very different picture on paper, with DTE Energy trading below both analyst targets and one intrinsic value estimate. How wide is that gap, and what does it say about fair value today?
Most Popular Narrative: 18% Undervalued
DTE Energy closed at $130.70, against a widely followed fair value estimate of $159.25. This frames the recent pullback as a valuation gap rather than just a reaction to board news. That gap is built on detailed assumptions about how grid spending, clean energy policy and data center demand could reshape future earnings.
DTE's $30 billion multi-year capital plan is heavily focused (>90%) on grid modernization, digitalization, and reliability upgrades, including deployment of over 220 smart grid devices this year, which is already showing a 70% year-over-year improvement in reliability. These investments are expected to drive regulated asset base growth, supporting long-term earnings stability and margin improvement from lower O&M expenses.
See why 11 investors see DTE Energy as 18% undervalued.
Result: Fair Value of $159.25 (UNDERVALUED)
Still, that 18% valuation gap depends on heavy grid and renewables spending landing on time and on budget, and on regulators approving sizeable future rate cases.
Find out about the key risks to this DTE Energy narrative.
Another View On DTE Energy’s Valuation
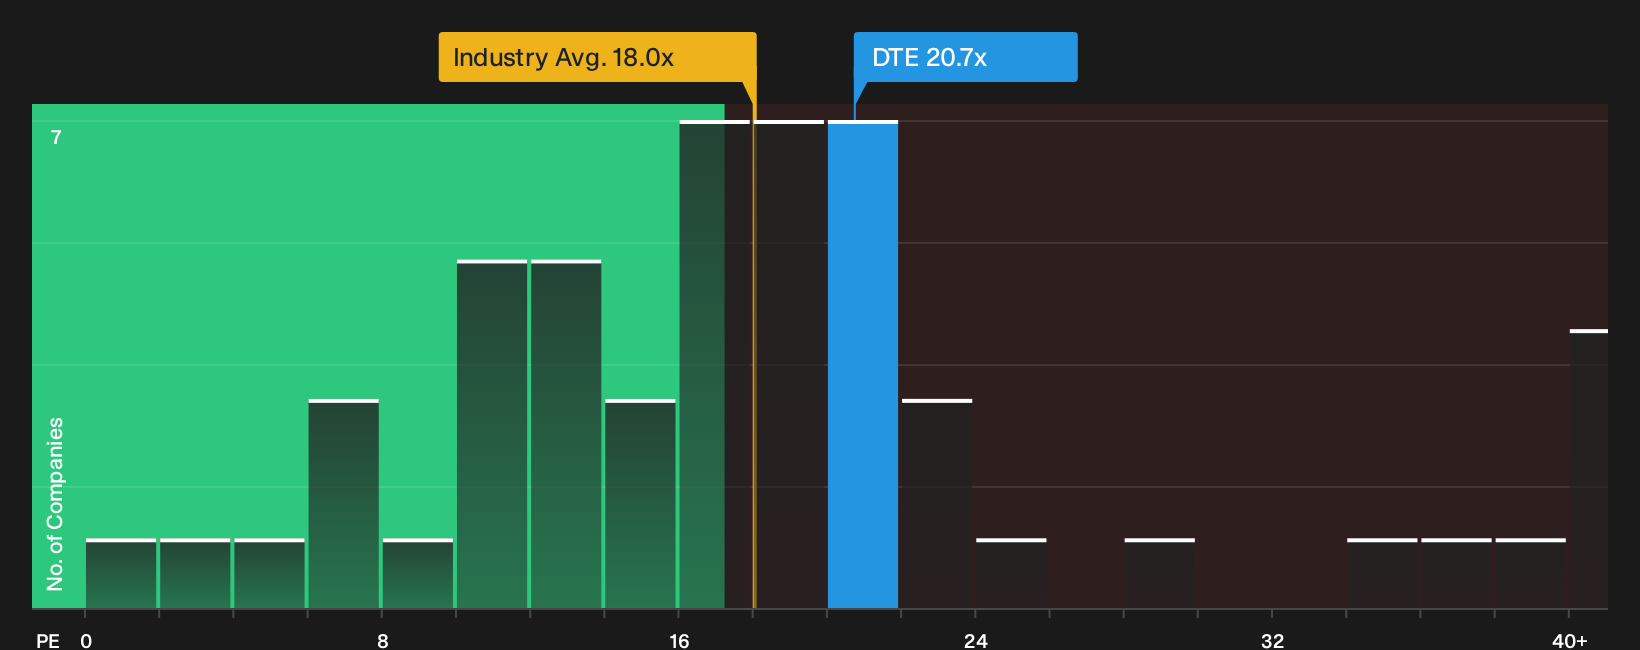
That 18% discount to fair value is only one lens. On simple P/E, DTE Energy trades at 20.7x, slightly richer than US integrated utility peers at 20.3x and well above the broader global group at 17.9x. The fair ratio points to 22.5x. Is that extra multiple premium worth paying for this grid and storage story?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around DTE Energy can feel unsettled. Move quickly, look through the numbers yourself, and weigh both the upside and the red flags. To see the full balance of potential positives and concerns in one place, start with these 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond DTE Energy?
If DTE Energy is on your radar, broaden your watchlist now and compare it with other potential opportunities before the market moves past today’s prices.
- Target potential mispricings by scanning a curated set of 33 high quality undervalued stocks that combine solid fundamentals with room for market sentiment to catch up.
- Strengthen your income stream by reviewing a focused group of 6 dividend fortresses that aim to pair higher yields with balance sheet support.
- Protect against shocks by filtering for a list of solid balance sheet and fundamentals (22 results) that can better handle funding costs, rate moves, and unexpected operational setbacks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com