
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Global Field Trials Change FMC's (FMC) Narrative
- AgroSpheres and FMC Corporation reported that two proprietary RNA-based bioinsecticide candidates targeting lepidopteran pests have moved into global field trial development across the United States, Brazil and Asia after multi year lab, greenhouse and small scale tests.
- This step pushes FMC further into biological pest control, a segment where regulatory scrutiny and grower demand increasingly favor targeted, residue light products over traditional chemistries.
- We will look at how FMC's investment narrative around biologicals and higher margin technologies is influenced by these RNA bioinsecticide trials.
Scan FMC's move into RNA biologicals against a wider peer set by checking which agriculture stocks on our curated list are also leaning into next generation crop protection 11 resilient stocks with low risk scores.
FMC Investment Narrative Recap
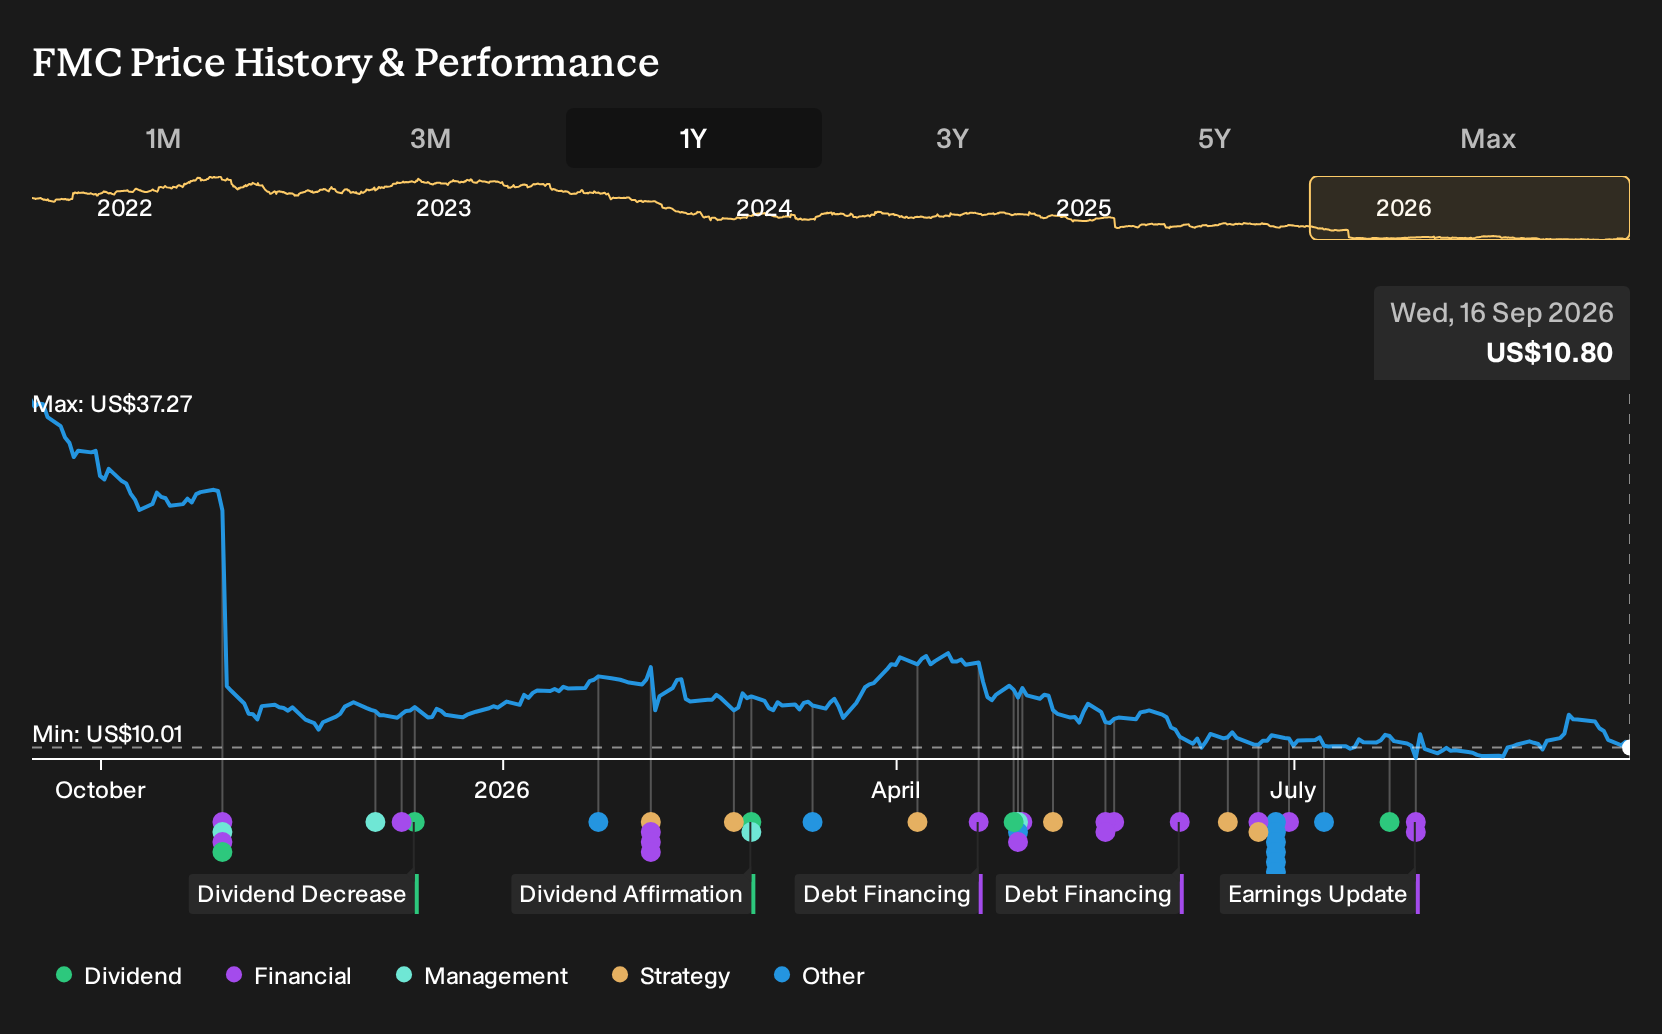
To own FMC, you need to believe the crop protection portfolio, including biologicals, can support steadier earnings after a tough stretch of losses and weak share returns. In the near term, the key swing factor still appears to be execution on new product launches and cost programs, not this single RNA update, which is more of a credibility signal than an immediate volume driver.
The biggest risk remains pressure on pricing, regulatory exposure and the balance sheet, with interest costs not well covered by current earnings and leverage elevated. RNA bioinsecticide field trials could help the longer term mix story if they progress well, but they do not change the near term financing and profitability question.
The RNA bioinsecticide field trials align directly with FMC's push into Biologicals and Plant Health, which analysts already view as a key margin and growth lever. Real world performance data from the United States, Brazil and Asia will feed into that thesis, especially if these products can sit alongside existing actives such as fluindapyr, Isoflex and Dodhylex.
For you as a shareholder, the interest is less about one product win and more about whether FMC can build a broader, higher value portfolio that supports deleveraging and more sustainable cash generation. Progress through trials without major regulatory or efficacy setbacks would support that operational story, while problems here would add to the existing pipeline and execution risk already flagged in the outlook.
FMC's narrative projects US$3.9b revenue and US$313.5 million earnings by 2029. This reflects 6.6% yearly revenue growth and an earnings swing of about US$3.0b from the current loss of US$2.7b to the forecast profit.
Uncover why FMC's fair value indicates a 25% potential upside to its current price. This potential could narrow quickly if FMC executes on its Biologicals plan.
Exploring Other Perspectives
Some of the most optimistic analysts already saw FMC reaching about US$4.5b of revenue and US$593.7 million of earnings by 2029, largely on faster product approvals. You might view the RNA bioinsecticide field trials as a possible extra kicker to that story. Others were closer to US$3.9b and US$313.5 million, so opinions clearly vary.
Explore 4 other FMC fair value estimates, including one that suggests potential upside of up to 177% from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so go with your instincts.
- A great starting point for your FMC research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for FMC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FMC's overall financial health at a glance.
Looking For More Ideas Beyond FMC?
If FMC has sharpened your thinking about crop protection and risk, use that momentum to broaden your watchlist with other businesses that match your preferred balance of quality, income and resilience.
- If you want potential mispricings with stronger fundamentals, start by scanning our 33 high quality undervalued stocks that already combine financial quality with a discount to fair value estimates.
- For readers who care most about dependable income, focus on companies in our 6 dividend fortresses that pair higher yields with more robust dividend profiles.
- When capital preservation matters just as much as upside, consider stocks in our list of solid balance sheet and fundamentals (22 results) to anchor your portfolio with sturdier finances.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com