
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Intuitive Machines (LUNR) Could Be 40% Below Fair Value On SiriusXM Satellite Handover
Intuitive Machines (LUNR) just completed the handover of the SXM-11 satellite to long-time partner SiriusXM after in-orbit testing, a fresh signal about execution on real commercial space hardware.
For context, Intuitive Machines shares trade at US$13.87 after a 30-day share price return that is down 31.94% and a 90-day share price return that is down 39.30%. Yet the 1-year total shareholder return of 49.46% and 3-year total shareholder return of roughly 2.5x suggest longer term holders have still seen strong gains even as recent momentum has faded around the latest contract wins and record revenue headlines.
Scan other space and defense plays that are progressing on real hardware execution with our curated list of 38 robotics and automation stocks.
Intuitive Machines trades well below a clustered set of analyst targets while still up sharply over twelve months. Does that gap flag mispricing, or does it simply reflect the risk investors now assign to those forecasts?
Most Popular Narrative: 40% Undervalued
Against the last close at $13.87, the most followed narrative on Intuitive Machines anchors fair value closer to $23, which frames today’s drop as a discount rather than a warning signal.
Balancing High-Growth Potential with Capital Dilution Intuitive Machines (LUNR) has successfully shifted from a high-risk startup to a Lunar Infrastructure Prime, backed by a $943M backlog and a strategic pivot toward high-margin data services via the Lanteris acquisition. While the trajectory toward positive Adjusted EBITDA in 2026 is clear, the current stock price reflects a "perfection premium" that overlooks recent share dilution.
See why 25 investors see Intuitive Machines as 40% undervalued.
According to sorkdhkddlek, that fair value of about $23 per share is built on a discounted rate of 7.68% and a view that the backlog and data services shift justify paying up for future earnings power even after accounting for dilution and execution risk in the lunar economy.
Result: Fair Value of $23 (UNDERVALUED)
Still, the Intuitive Machines story could be jolted if capital needs drive heavier dilution than bulls expect, or if lunar mission execution timelines slip further.
Find out about the key risks to this Intuitive Machines narrative.
Another View On Intuitive Machines’ Valuation
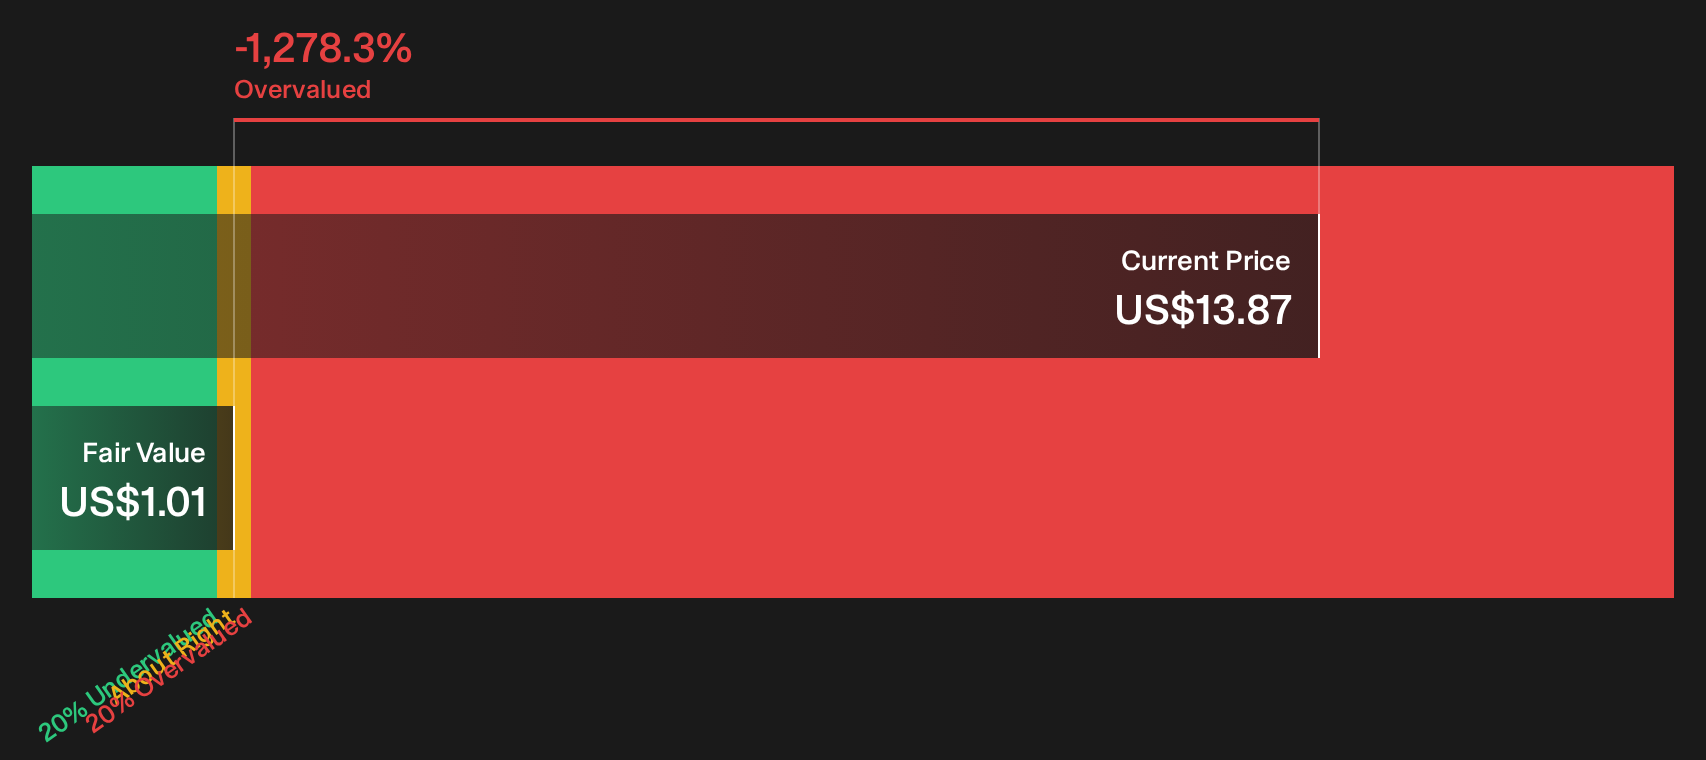
That $23 fair value narrative leans on future revenue and a peer-style P/S multiple. Our DCF model tells a very different story. On that view, Intuitive Machines at $13.87 trades far above an estimated future cash flow value of about $1.01, which points to an overvalued setup. Which lens do you trust more when the cash flows are still mostly in the future?
To see how this framework is built out in detail, including each step in the cash flow path and discounting, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on Intuitive Machines so far. If you think the balance of risk and potential reward looks skewed, move fast, review the numbers, then weigh the 1 key reward and 3 important warning signs.
Looking for more Intuitive Machines investment ideas?
If Intuitive Machines has your attention, do not stop here. Use the data-driven screeners below to hunt for the next opportunity before others catch on.
- Target resilient cash flows and strong cushions by scanning a list of solid balance sheet and fundamentals (22 results) that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced opportunities by reviewing a focused set of 33 high quality undervalued stocks where fundamentals and valuation work together for you.
- Explore recurring income potential by checking a curated pool of 6 dividend fortresses built around higher yields with an eye on staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com