
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Meridian Energy (NZSE:MEL) Climbed, What Is Behind The Fresh Attention?
Meridian Energy (NZSE:MEL) just reported August 2026 operating data, with monthly generation of 1,432 GWh compared with 1,179 GWh in August 2025. That shift gives investors fresh information on recent portfolio performance.
Recent trading has picked up, with Meridian Energy’s share price gaining 2.24% over the last day and 3.99% over the past week, even though it is still down 9.29% on a 90 day share price return basis. The 1 year total shareholder return sits at 1.89%, which suggests short term momentum is improving while longer term investors have seen steadier but more modest gains.
Scan how other renewable-focused utilities are trading right now by comparing Meridian Energy's latest move against a curated list of 38 power grid technology and infrastructure stocks
Meridian Energy appears to be a solid renewable utility based on recent operating and shareholder returns, but the share price move this month raises a sharper question. Are you paying a fair price for that quality, or stretching for it?
Price-to-Earnings of 111.4x: Is it justified?
Valuation work on Meridian Energy presents a split picture, with the stock trading at NZ$5.47 while our DCF model points to a future cash flow value of NZ$9.84. At the same time, the P/E ratio of 111.4x signals a very full earnings multiple compared with peers.
The P/E multiple measures how much investors are currently paying for each dollar of net profit. For a renewable utility like Meridian Energy, a higher P/E can reflect expectations for steadier cash flows, longer life assets, or improvement in profitability after a period of weaker earnings. With the firm only recently becoming profitable and reporting annual net income of NZ$130.0m on NZ$3,883.0m of revenue, that ratio is being calculated off relatively thin earnings.
A P/E of 111.4x is very high compared with both the estimated Fair P/E of 35.4x and the global renewable energy industry average of 15.2x. That suggests the market is paying a heavy premium to today’s earnings level. It could also mean the multiple may move closer to the fair ratio over time if profit growth does not keep pace.
Explore the SWS fair ratio for Meridian Energy.
Result: Price-to-Earnings of 111.4x (OVERVALUED)
Still, the high P/E leaves Meridian Energy exposed if earnings soften or if investors begin to question paying a premium for relatively modest net income.
Find out about the key risks to this Meridian Energy narrative.
Another view on Meridian Energy's value
The SWS DCF model presents a very different picture for Meridian Energy. At NZ$5.47 compared with an estimated future cash flow value of NZ$9.84, the shares appear materially undervalued on cash flows, even though the P/E ratio looks stretched. Which signal should be treated as more important?
Look into how the SWS DCF model arrives at its fair value.
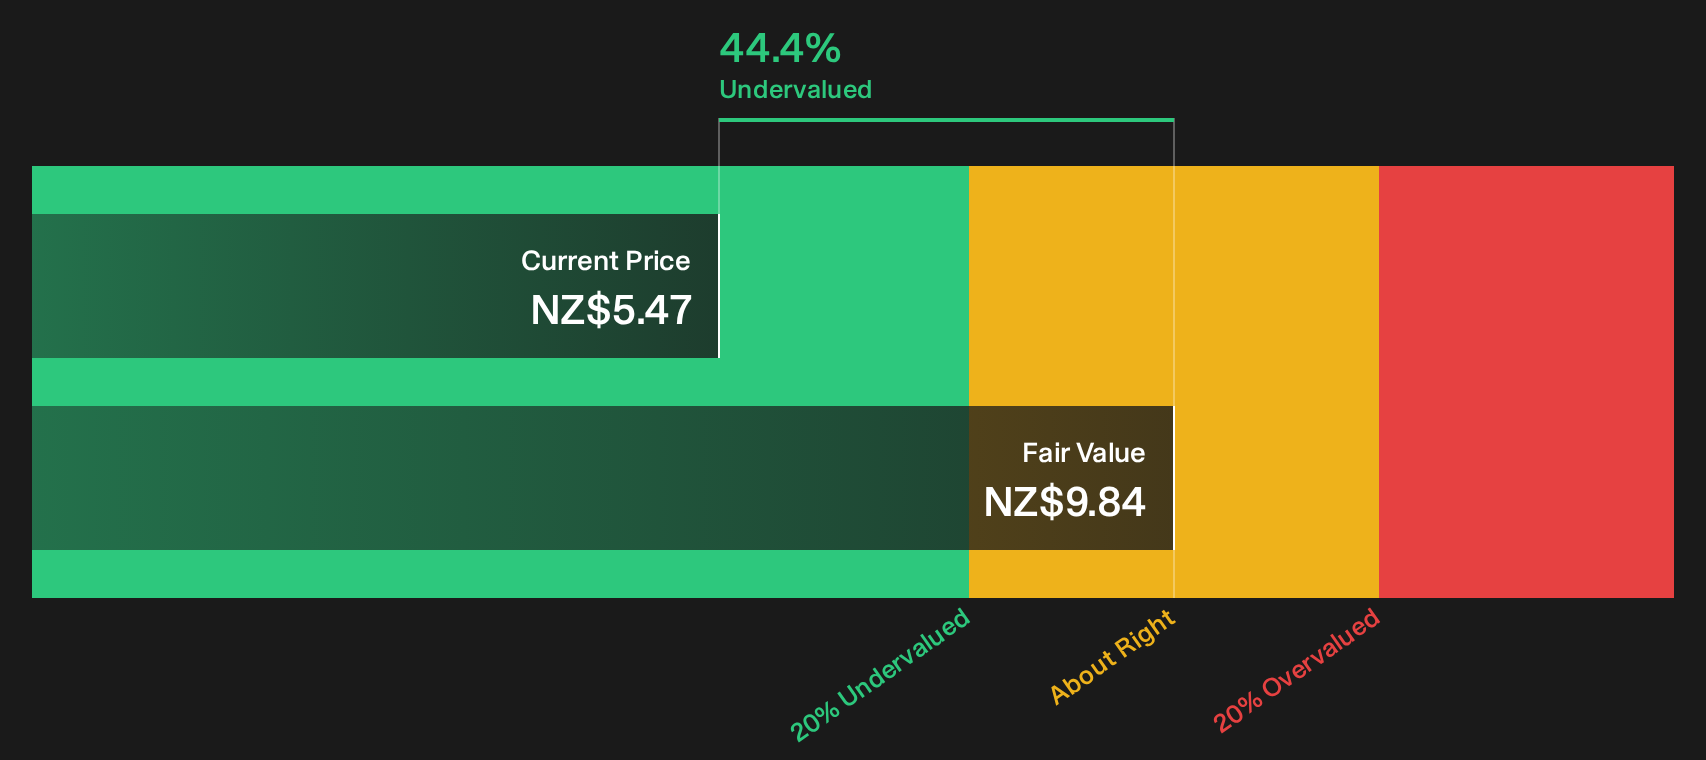
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Meridian Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 184 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Meridian Energy are clear enough. Move quickly, pull up the full data set, and stress test the 3 key rewards and 1 important warning sign through the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Meridian Energy?
If you stop here, you only see one piece of the puzzle. Broaden your watchlist with other potential opportunities that fit different goals and risk levels.
- Target potential mispricing by scanning a curated pool of companies that screen as attractively valued using the 184 high quality undervalued stocks.
- Strengthen your income stream by focusing on businesses that combine higher yields with resilience through the 162 dividend fortresses.
- Dial down risk while staying invested by filtering for financially robust businesses via the 104 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com