
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Expanded AI Partnership Altering The Investment Case For Siemens Stock (XTRA:SIE)?
- Siemens and Salesforce recently expanded their partnership, integrating Salesforce’s Agentforce with Siemens’ Teamcenter Service Lifecycle Management to embed AI driven, engineering grade answers directly into industrial sales and service workflows.
- The move positions Siemens’ quality and automation platforms as central tools for connecting engineering data, field service, and customer information. This could influence how efficiently industrial clients manage complexity and lifetime service costs.
- We will now examine how Siemens' investment narrative could be affected by the expanded use of Salesforce Agentforce across its global operations.
Scan how Siemens’ AI heavy quality and automation push compares with other potential beneficiaries of the same trend by reviewing our curated list of 60 AI infrastructure stocks.
Siemens Investment Narrative Recap
To own Siemens, you need to be comfortable with a mature industrial group that leans heavily on electrification, digital automation, and a very large order book to support future cash flows. The big near term swing factor remains how quickly demand in automation and software stabilizes in weaker regions like China and Germany, because softness there can weigh on Digital Industries margins.
The expanded Agentforce rollout looks directionally helpful, but on its own it does not change the main short term story. The key risk still sits in macro sensitive capital spending and pricing pressure in automation, amplified by Siemens’ high debt load and the execution burden from ongoing software and cloud transitions.
The Agentforce integration into Siemens’ Teamcenter Service Lifecycle Management is the clearest operational tie in to the current news. It plugs industrial grade engineering data directly into sales and service workflows. For you as an investor, the notable angle is whether this tight link between field information, customers, and engineering can shorten sales cycles and improve service productivity.
Quality management is the second piece worth your attention. Siemens was listed among leaders in a 2026 Quality Management System technology matrix, alongside peers like Honeywell and MasterControl. That recognition, together with the AI centric Salesforce partnership, supports the existing catalyst narrative that Siemens is pushing further into higher margin digital workflows, while still facing the usual execution and competitive risks in automation and industrial software.
Siemens' current analyst narrative points to €96.4b revenue and €12.1b earnings by 2029, based on a 5.9% yearly revenue growth rate and a move from €7.9b earnings today to that €12.1b figure. This implies an earnings increase of roughly €4.2b over the period.
Uncover why Siemens' fair value indicates a 16% potential upside to its current price that may not last much longer.
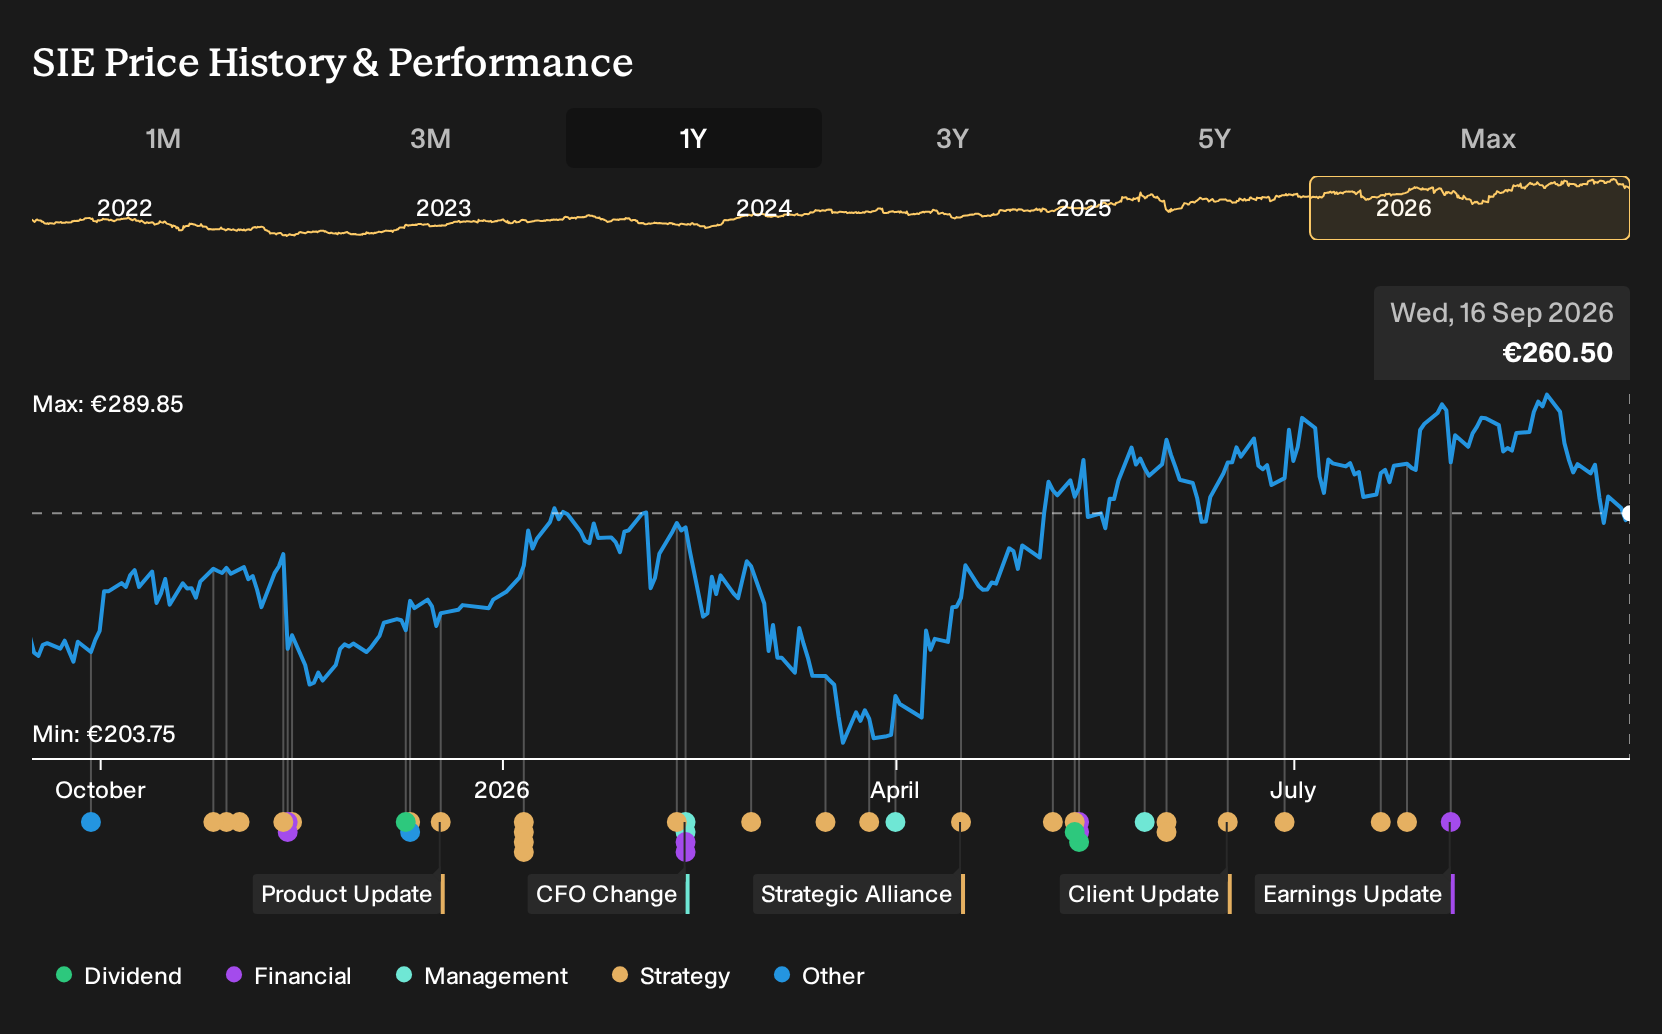
Exploring Other Perspectives
Some of the most optimistic analysts frame Siemens as an AI and data center winner rather than just a mature industrial group. Before this Salesforce news, the bullish camp already penciled in about €108.8b of revenue and €13.8b of earnings by 2029. You can now ask whether this Agentforce rollout pushes that upbeat scenario even further or forces a rethink, and explore how far your own expectations sit from those forecasts.
Explore 4 other Siemens fair value estimates, including one that suggests the potential for as much as 50% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Siemens research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Siemens. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Siemens' overall financial health at a glance.
Looking For More Ideas Beyond Siemens?
If you want to stress test your Siemens thesis against other opportunities, the Simply Wall St Screener can help you quickly surface stocks that match the type of risk and reward profile you prefer.
- If capital preservation matters most to you, start with a basket of companies that score well on resilience and risk controls through our 104 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, compare Siemens against a curated set of companies that pair solid fundamentals with attractive valuations using the 185 high quality undervalued stocks.
- Income focused readers who care about reliable cash returns can benchmark Siemens against a group of high yield candidates by running the 161 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com