
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Power Sports Growth At Yamaha Motor Stock Has Changed Its Investment Story
- Recent industry research projects the global power sports market to reach US$44.5b by 2035, supported by rising outdoor recreation demand and vehicle technology development from manufacturers such as Yamaha Motor, Polaris, and BRP.
- The same report highlights how Yamaha Motor’s focus on product development, smarter vehicle systems, and stronger dealer and after sales coverage could align closely with this expanding power sports opportunity.
- We will now look at how Yamaha Motor’s exposure to a growing global power sports market could reshape the existing investment narrative.
Scan Yamaha Motor alongside other power sports and recreation plays by checking a curated 38 robotics and automation stocks that groups companies exposed to similar outdoor and equipment trends.
Yamaha Motor Investment Narrative Recap
To own Yamaha Motor, you need to believe the power sports and outdoor vehicle push can offset pressure in areas like Marine and Outdoor Land Vehicle, while the premium motorcycle and robotics plans keep earnings momentum intact. The fresh market research on power sports demand supports that broad thesis but does not, on its own, change the story.
The key short term swing factor still looks operational. Execution on OLV integration, cost control and inventory discipline across dealers could tighten margins or leave them exposed to raw material and labor inflation. Quality issues, recall costs, or renewed softness in Marine demand remain the biggest near term risk to that picture.
Recent commentary around integrating the RV business with golf cars into a single Outdoor Land Vehicle unit is particularly relevant here. Power sports exposure only pays off for shareholders if Yamaha Motor can run that combined division efficiently, keep discounts in check, and avoid excess stock building up at dealers while the market grows.
If OLV restructuring delivers the targeted cost reductions and smoother logistics, it could help offset pressure from higher input costs and currency swings. If execution is slow, investors are left with the same exchange rate and demand risks, but with extra restructuring and potential impairment noise on top of them.
Yamaha Motor's current earnings of ¥76.9 billion are set against analyst expectations of ¥175.9 billion by 2029. This implies an earnings increase of about ¥99.0 billion and a yearly revenue growth rate assumption of 3.5%. These figures are all tied to a broader forecast that projects revenues of ¥3,057.6 billion and earnings of ¥175.9 billion in 2029.
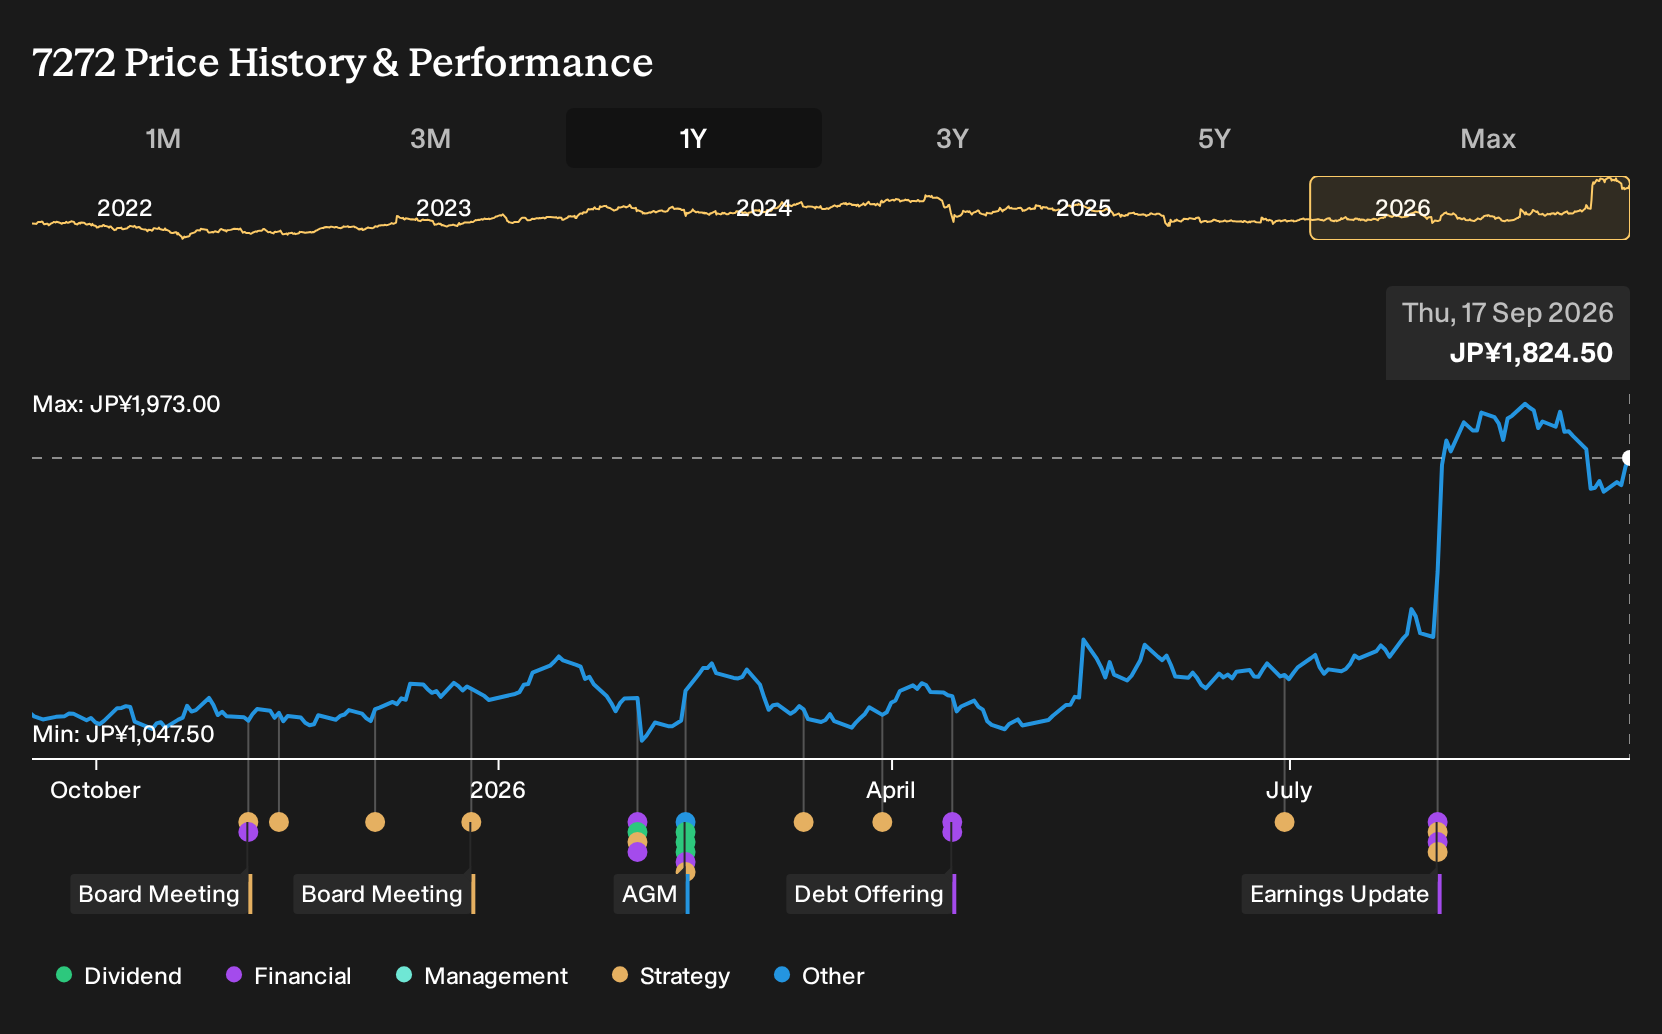
Uncover why Yamaha Motor's fair value points to a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between ¥1,509.64 and ¥2,100, which leaves plenty of room for disagreement on Yamaha Motor. When you set those views against risks around raw material costs, Marine softness, and exchange rates, you can reach very different conclusions. Use that spread to test your own thesis.
Explore 2 other Yamaha Motor fair value estimates, including one that suggests up to 15% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Yamaha Motor research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Yamaha Motor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Yamaha Motor's overall financial health at a glance.
Looking for more Yamaha Motor investment ideas?
Once you have a view on Yamaha Motor, it can help to cross check that thinking against other opportunities with similar or contrasting traits using the Simply Wall St Screener.
- If you want potential value with quality attached, scan a 17 high quality undervalued stocks that filters for companies with support from both earnings and balance sheet strength.
- If resilience matters most to you, focus on a 12 resilient stocks with low risk scores that screens for businesses with steadier risk profiles and fewer financial red flags.
- If you prefer solid foundations before anything else, start with a list of solid balance sheet and fundamentals (20 results) that surfaces companies with stronger funding structures and healthier leverage metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com