
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Renewable Tyvek Launch At DuPont De Nemours Has Changed Its Investment Story
- DuPont de Nemours recently launched Tyvek with Renewable Attribution for global consumer and industrial uses, offering HDPE grades with 30% to 100% ISCC PLUS certified bio-circular content on a mass balance basis while keeping existing Tyvek specifications unchanged.
- The drop-in, no-requalification design, combined with second-generation waste-derived feedstocks and audited traceability, aims to cut customers’ product carbon footprints without redesign costs or process disruption.
- We will look at how DuPont de Nemours' investment narrative is affected by Tyvek's renewable attribution and no redesign requirement.
Scan DuPont de Nemours alongside other materials and packaging players that may be moving on lower-carbon themes with our hand picked list of solid balance sheet and fundamentals (22 results).
DuPont de Nemours Investment Narrative Recap
To own DuPont de Nemours, you need to believe the refocus on Healthcare & Water and higher value industrial materials can translate forecast revenue growth of 4.3% a year and faster earnings progress into steadier profitability. The Tyvek with Renewable Attribution launch fits that tilt toward cleaner, higher spec products, but it is one product line inside a broad portfolio.
The bigger short term swing factors still sit elsewhere. Execution around portfolio reshaping after Qnity and any future divestitures, along with pricing power in Diversified Industrials, will likely drive how earnings quality evolves. PFAS related legal exposure remains the key overhang. The new North Carolina settlement spreads cash outflows but does not remove future case risk.
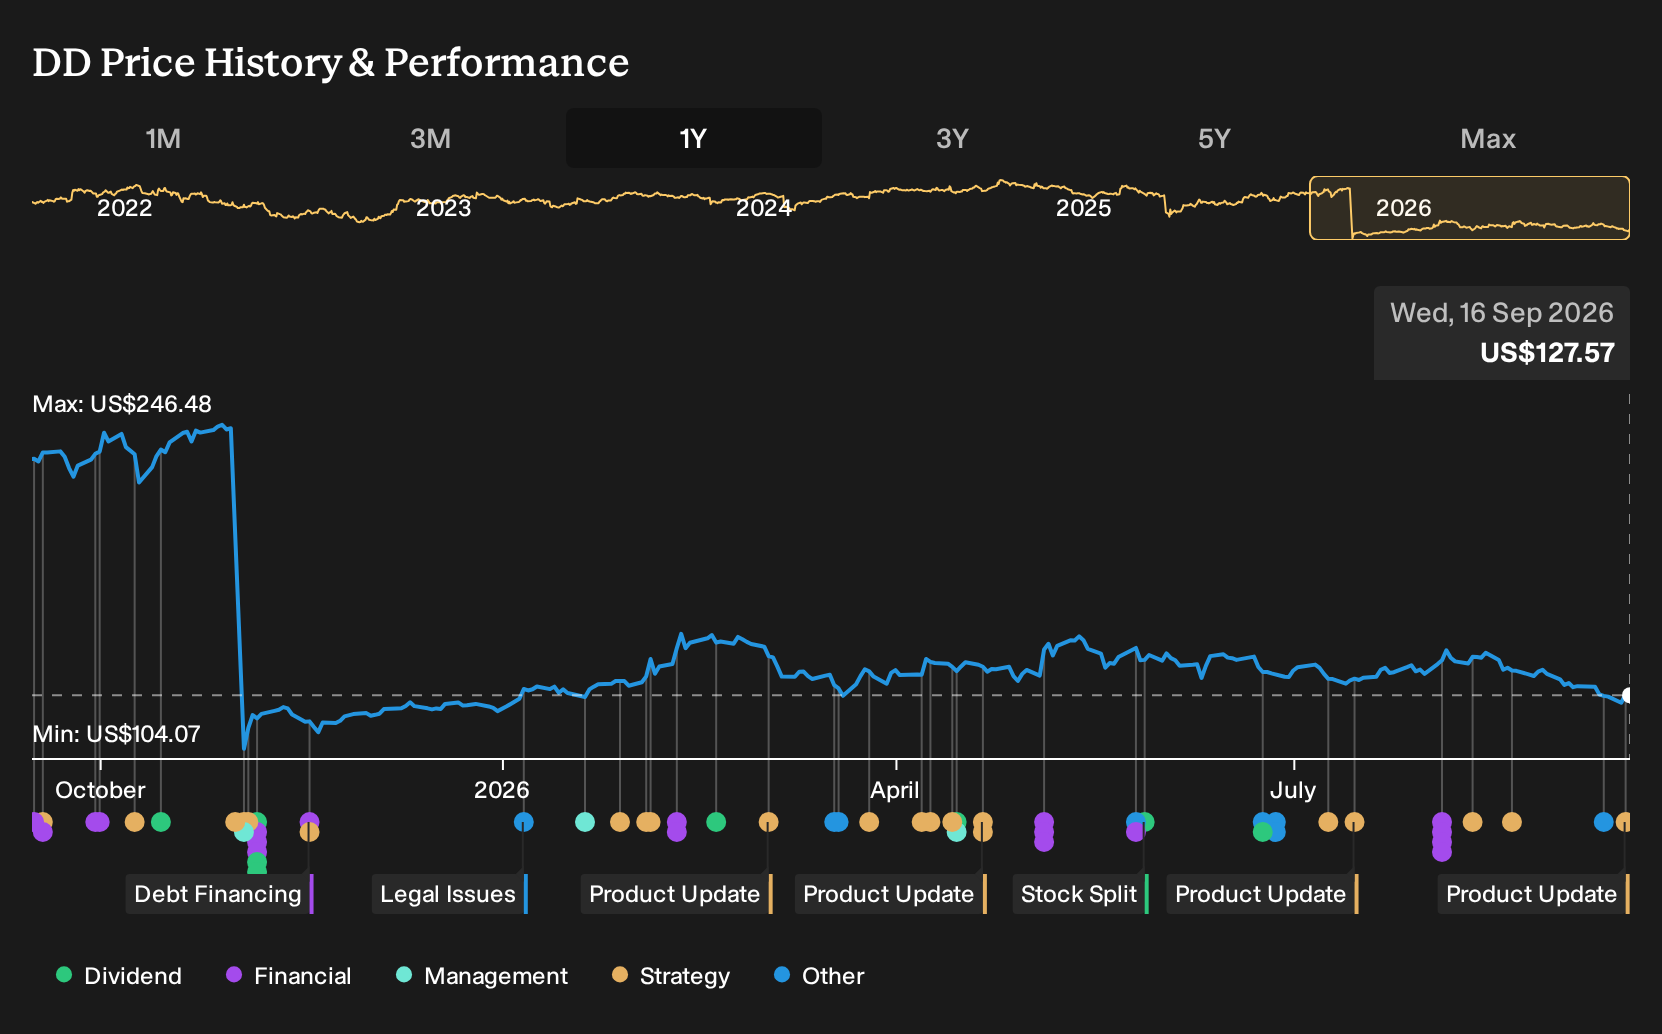
The PFAS settlement announced on 10 September 2026 is the most relevant counterweight to the Tyvek news for anyone tracking DuPont de Nemours today. The US$455 million agreement with North Carolina and 11 local entities is structured over 15 years, with DuPont sharing payments under the existing memorandum of understanding.
This structure matters for catalysts because it supports the thesis of more predictable free cash flow, which analysts already link to higher earnings stability. The settlement is applied as US$210 million of qualified spend against the US$4b cap using a net present value method. That accounting treatment, plus use of the MOU escrow, helps limit future escrow contributions, although PFAS claims elsewhere still sit in the risk column.
DuPont de Nemours' current analyst script points to US$7.8b in revenue and US$919.6m in earnings by 2029. This outlook is built on revenue growth of 4.3% per year and a jump in earnings from US$132.0m today to US$919.6m, which is roughly a 6x increase.
Discover how DuPont de Nemours' fair value indicates a 35% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One bullish twist on DuPont de Nemours focuses on sustainable materials as the real swing factor. The most optimistic analysts were already pencilling in revenue of about US$8.0b and earnings of roughly US$1.0b by 2029 before this Tyvek news. You can now ask whether this kind of product launch nudges those expectations even higher or prompts a rethink.
Explore 3 other DuPont de Nemours fair value estimates, including one that suggests as much as 55% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your DuPont de Nemours research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for DuPont de Nemours. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DuPont de Nemours' overall financial health at a glance.
Looking for more investment ideas beyond DuPont de Nemours?
If the DuPont de Nemours story has sharpened your thinking about risk, balance sheets, and future potential, it can be useful to line that up against other opportunities on your radar.
- If you want potential upside with a bit more punch, consider smaller companies that still clear quality hurdles by scanning our 11 elite penny stocks with strong financials.
- For investors who care most about paying a reasonable price for solid fundamentals, filter for companies that screen as both durable and potentially mispriced through the 33 high quality undervalued stocks.
- If steady cash payouts matter to your plan, compare DuPont de Nemours to businesses focused on income strength using the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com