
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Bank Leumi Shares Investors Should Know About Its €750 Million Bond Issue
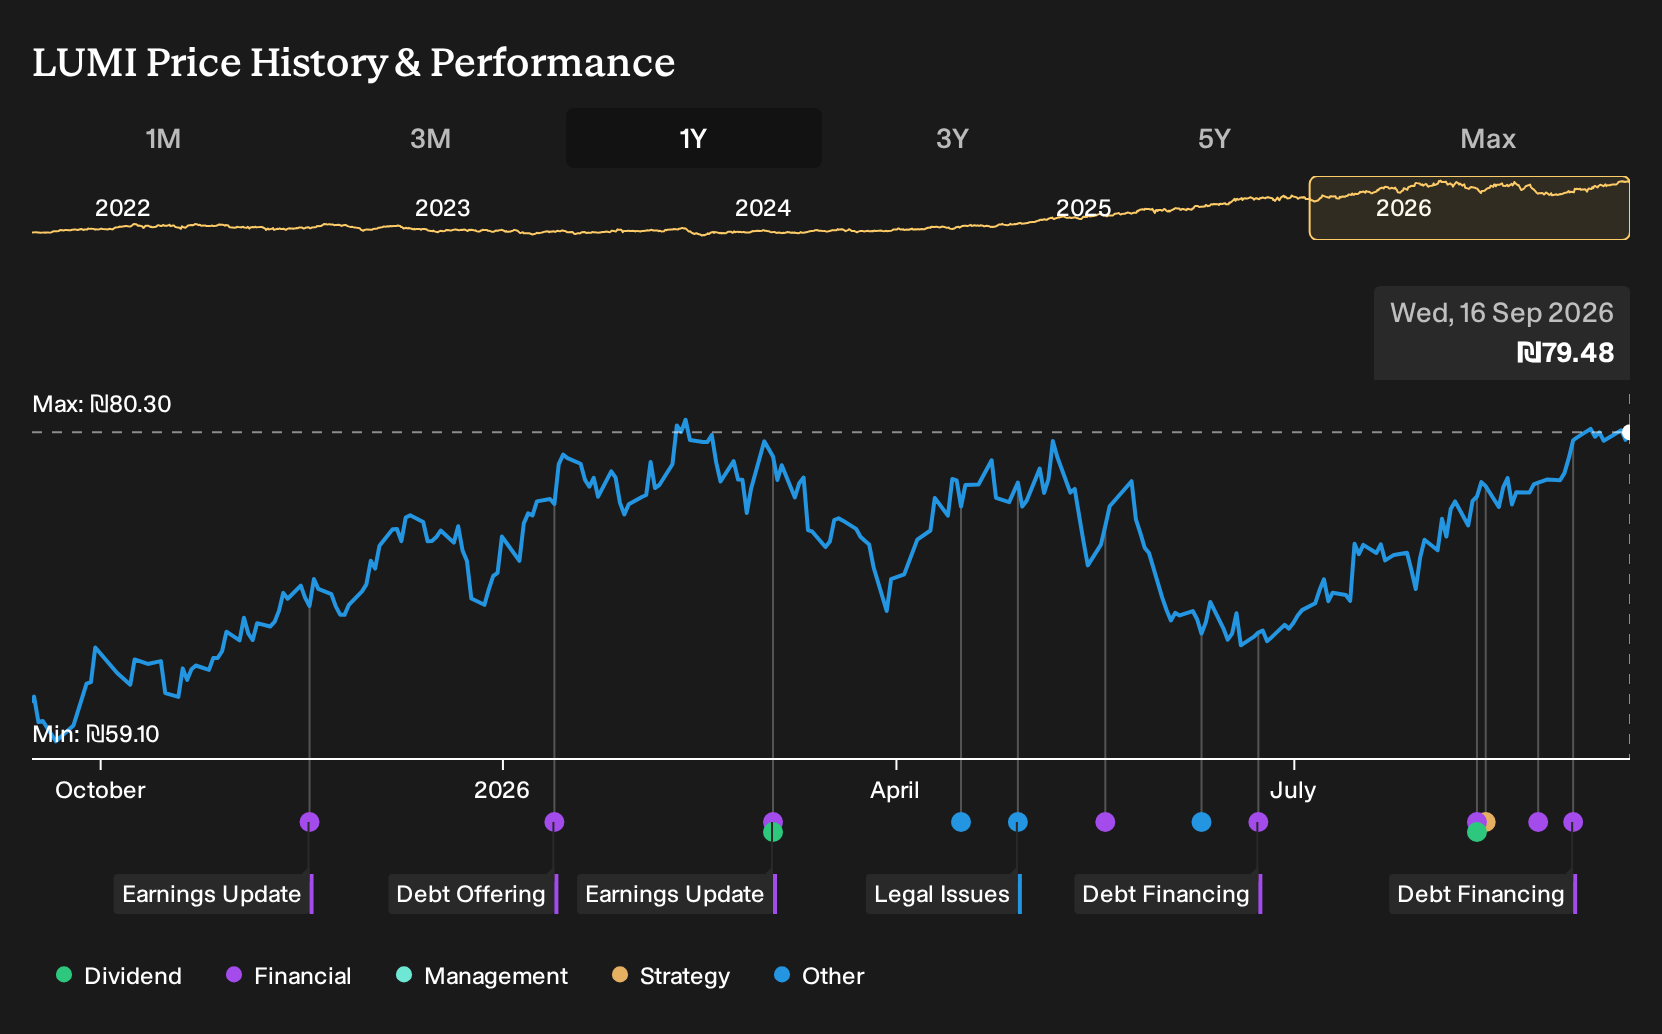
- Bank Leumi le-Israel B.M. completed a €750,000,000 Series 2 covered bond issuance in September 2026, paying a 3.609% fixed coupon to qualifying non-Israeli investors under its €3b Global Covered Bond Programme.
- The deal, backed by Aa3 and AA- ratings from Moody's and Fitch and distributed via a global syndicate, highlights Bank Leumi le-Israel B.M.'s access to large-scale institutional funding outside its home market.
- We now examine how Bank Leumi le-Israel B.M.'s €750,000,000 covered bond deal could influence the bank's broader investment narrative.
Bank Leumi le-Israel B.M Investment Narrative Recap
To hold Bank Leumi le-Israel B.M, you need to be comfortable with a large, universal bank that leans heavily on net interest income, fee streams and a high credit quality profile. The big swing factor near term is the interest rate path in Israel, since management has flagged that a 1% cut could pressure results by about ₪800m and ROE by roughly 0.8 percentage points.
The new €750m covered bond does not radically alter that equation. It reinforces access to wholesale funding and supports credit growth if demand persists, but the core risk still sits with potential rate cuts, regulatory shifts around bank taxation or mortgages, and any move away from unusually low credit loss levels.
The Series 2 covered bond issue, carrying a 3.609% fixed coupon to September 2029 and strong Aa3 and AA ratings, is the clearest operational signal tied to this story. It aligns with Bank Leumi le-Israel B.M’s need to fund a broad loan book that spans mortgages, commercial clients, real estate and high tech oriented corporates without leaning solely on domestic deposits.
For catalysts, the focus is whether this type of wholesale funding helps sustain credit portfolio momentum while preserving the cost to income discipline that had improved to 27% in 2025. The flip side is refinancing and interest rate risk if the Bank of Israel eases policy meaningfully, which could squeeze spreads even as the bank continues to access institutional markets like TASE-UP and the broader European investor base.
Bank Leumi le-Israel B.M's narrative points to revenues of ₪27.4b and earnings of ₪12.3b by 2029, based on analysts’ assumption of 6.4% yearly revenue growth and an earnings increase of about ₪1.9b from current earnings of ₪10.4b.
Uncover how Bank Leumi le-Israel B.M's fair value indicates a 12% potential upside to its current price, before sentiment closes that discount gap.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between ₪79.72 and ₪89.65 per share, so retail opinions around Bank Leumi le-Israel B.M already span a meaningful range. When this is considered alongside rate cut risk, regulatory uncertainty and the new euro funding channel, it results in a mix of scenarios worth exploring from multiple angles.
Explore 2 other Bank Leumi le-Israel B.M fair value estimates, including one that suggests it could be worth just ₪79.72.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank Leumi le-Israel B.M research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bank Leumi le-Israel B.M. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank Leumi le-Israel B.M's overall financial health at a glance.
Looking for more investment ideas beyond Bank Leumi le-Israel B.M?
If the Bank Leumi le-Israel B.M story has sharpened your focus on funding, risk and valuation, broaden that lens by scanning other opportunities with the Simply Wall St Screener. Use it to compare balance sheet strength, income potential and quality indicators across a wider watchlist, then decide where Bank Leumi le-Israel B.M fits in your own plan.
- For income seekers who care about consistency as much as yield, review a curated set of income payers through 161 dividend fortresses and see which ones fit your payout and stability criteria.
- If capital preservation and resilience matter most to you, filter for companies that score well on financial strength and business durability using the 104 resilient stocks with low risk scores.
- When you want quality businesses that the crowd may be overlooking, scan through 619 high quality undiscovered gems and see which stories deserve a closer look next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com