
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
FirstCash Holdings (FCFS) Beats Q2 Expectations, Is The Stock Too Expensive?
FirstCash Holdings (FCFS) is back on investors’ radar after a strong Q2 showing, with revenue up 29.4% year on year and earnings per share topping analyst expectations.
FirstCash Holdings shares have pulled back over the past week despite the upbeat Q2, with a 7 day share price return of down 3.4%. However, the year to date share price return of 40.1% and 1 year total shareholder return of 49.2% still point to strong underlying momentum.
Scan beyond FirstCash Holdings and consider other financially solid operators serving similar consumer demand trends with our curated list of solid balance sheet and fundamentals (22 results)
After a big year to date run and a small pullback, FirstCash Holdings now trades between a raised analyst target and a much lower intrinsic estimate. Where does fair value really sit in that gap?
Price-to-Earnings of 24.5x: Is it justified?
FirstCash Holdings now carries a P/E of 24.5x at a last close of $219.70, which points to a rich valuation compared to peers and sector benchmarks.
The P/E ratio compares what investors are paying today for each dollar of current earnings. For a lender focused on pawn operations and point of sale financing, this gauge effectively captures how much the market is willing to pay for its profit stream.
For FCFS, that willingness is high. The stock is described as expensive versus a fair P/E estimate of 16.1x. This is a level the market could move toward if sentiment or growth expectations cool. The current multiple also runs well ahead of the peer average P/E of 17.4x, which signals that investors are attributing a premium to FirstCash Holdings relative to similar consumer finance operators.
The gap becomes even more pronounced when set against the broader US Consumer Finance industry, where the average P/E is 9.4x. That means the current valuation for FCFS is well over double the sector norm, and the fair ratio points to a considerably lower level than today if the market were to price earnings more in line with historical relationships.
Explore the SWS fair ratio for FirstCash Holdings.
Result: Price-to-Earnings of 24.5x (OVERVALUED)
Still, if credit conditions tighten or regulators clamp down on pawn and point of sale financing, the premium on FirstCash Holdings could reset quickly.
Find out about the key risks to this FirstCash Holdings narrative.
Another View on FirstCash Holdings' Value
The P/E story points to an expensive stock, yet the SWS DCF model paints an even starker picture. On that framework, FirstCash Holdings at $219.70 trades far above an estimated future cash flow value of $88.26, which implies a large premium over what long term cash generation suggests.
That kind of gap can reflect strong belief in the business model, or it can signal that expectations have run ahead of fundamentals. Which explanation feels closer to reality for you?
Look into how the SWS DCF model arrives at its fair value.
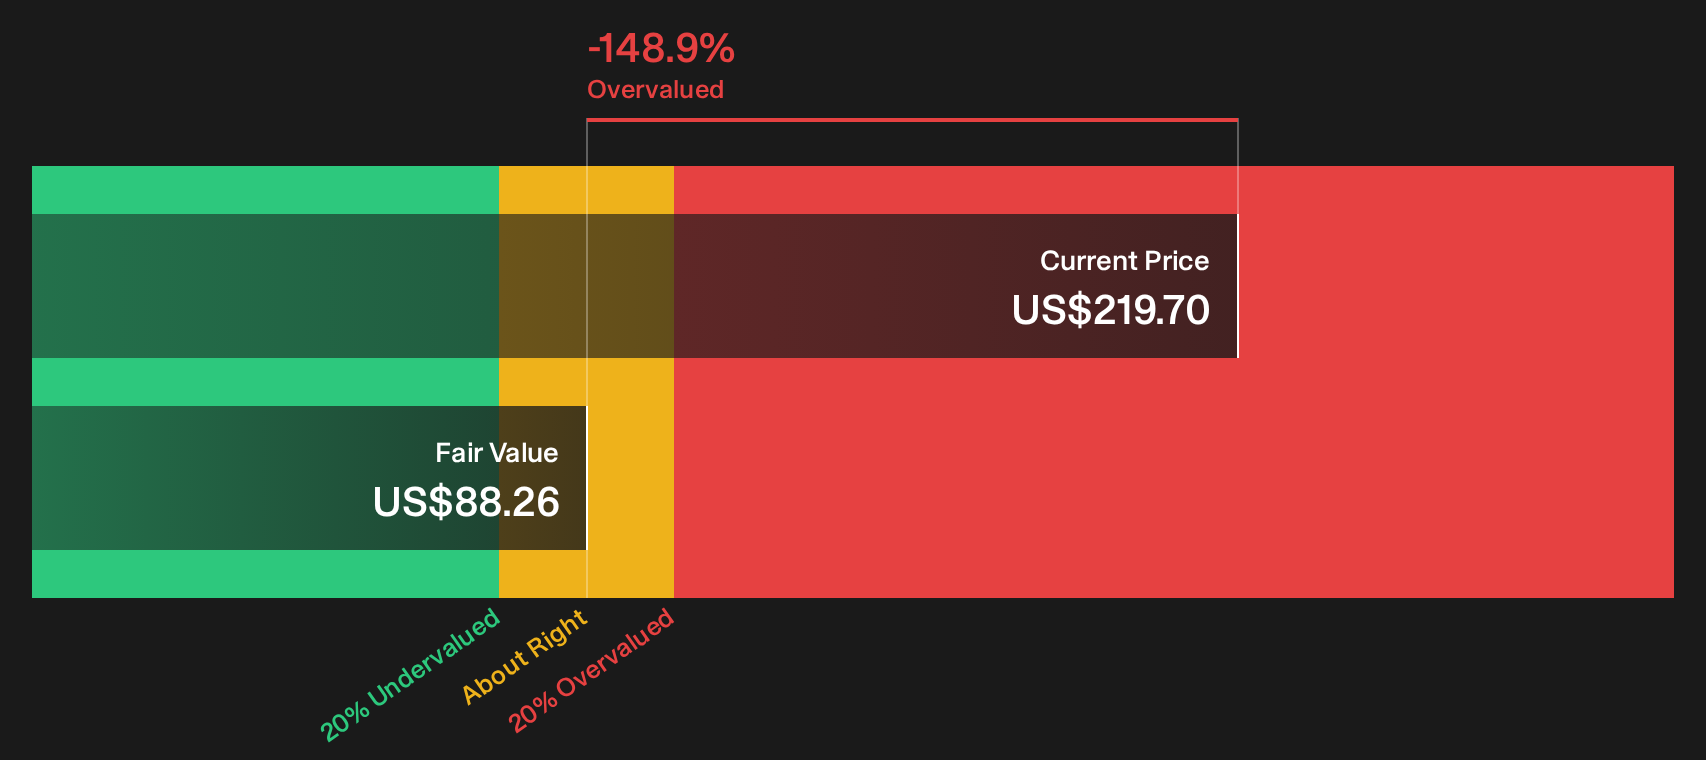
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out FirstCash Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around FirstCash Holdings is mixed, with strong recent results set against a valuation that looks stretched. Consider taking prompt action to review the full picture for yourself, and weigh both the potential upside and the downside using our breakdown of 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond FirstCash Holdings?
If you stop at FirstCash Holdings, you risk missing other opportunities that fit your style. Spend a few focused minutes and expand your opportunity set fast.
- Target resilient compounding potential by scanning a curated pool of companies in our 33 high quality undervalued stocks.
- Seek more predictable cash returns by filtering for income-heavy opportunities through the 6 dividend fortresses.
- Limit downside risk by narrowing the universe to financially robust operators using the 11 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com