
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Ermenegildo Zegna (ZGN) Sales Rose In Half Year Results, Is The Stock Still Undervalued?
Ermenegildo Zegna (ZGN) just posted half year 2026 earnings, with sales of €987.29 million versus €927.69 million a year earlier, while net income moved to €23.16 million from €43.08 million.
Ermenegildo Zegna shares trade at $11.8, with a 1-day share price return of 1.72% and a 7-day gain of 0.85%. However, the 30-day move is down 11.74% and the 90-day return is down 14.92%. In contrast, the 1-year total shareholder return of 27.53% alongside a 5-year total shareholder return of 25.87% points to longer term momentum that differs from the more recent weakness, as the latest half-year earnings refocus attention on how consistently the business can translate higher sales into profit.
Compare Ermenegildo Zegna’s latest earnings shift with a curated group of luxury and consumer names by scanning the 16 high quality undiscovered gems that may be flying under most investors' radar.
Ermenegildo Zegna is trading at $11.8 after a weak 3 month spell, while analyst targets and intrinsic estimates point to a very different range. Where does a fair price really line up between those anchors?
Most Popular Narrative: 18.7% Undervalued
Against the last close at $11.8, the most followed narrative on Ermenegildo Zegna pins fair value near $14.52. This frames today’s pullback as a discount to a higher long run earnings profile.
The strategic focus on direct-to-consumer (DTC) channels, aimed at increasing brand control, improving gross margins, and enhancing customer experience, is expected to drive long-term revenue growth and improve net margins across the Zegna, Thom Browne, and TOM FORD brands.
Geographic expansion and store openings in key markets like the U.S. and Dubai, alongside a focus on local and tourist customer bases, are expected to support sustained revenue growth and improve earnings by tapping into new consumer demographics and increasing store productivity.
See why 8 investors see Ermenegildo Zegna as 19% undervalued.
Result: Fair Value of $14.52 (UNDERVALUED)
Still, the bullish Ermenegildo Zegna story could unravel if Greater China remains weak and Thom Browne wholesale declines are not offset by direct to consumer growth.
Find out about the key risks to this Ermenegildo Zegna narrative.
Another View on Ermenegildo Zegna’s Valuation
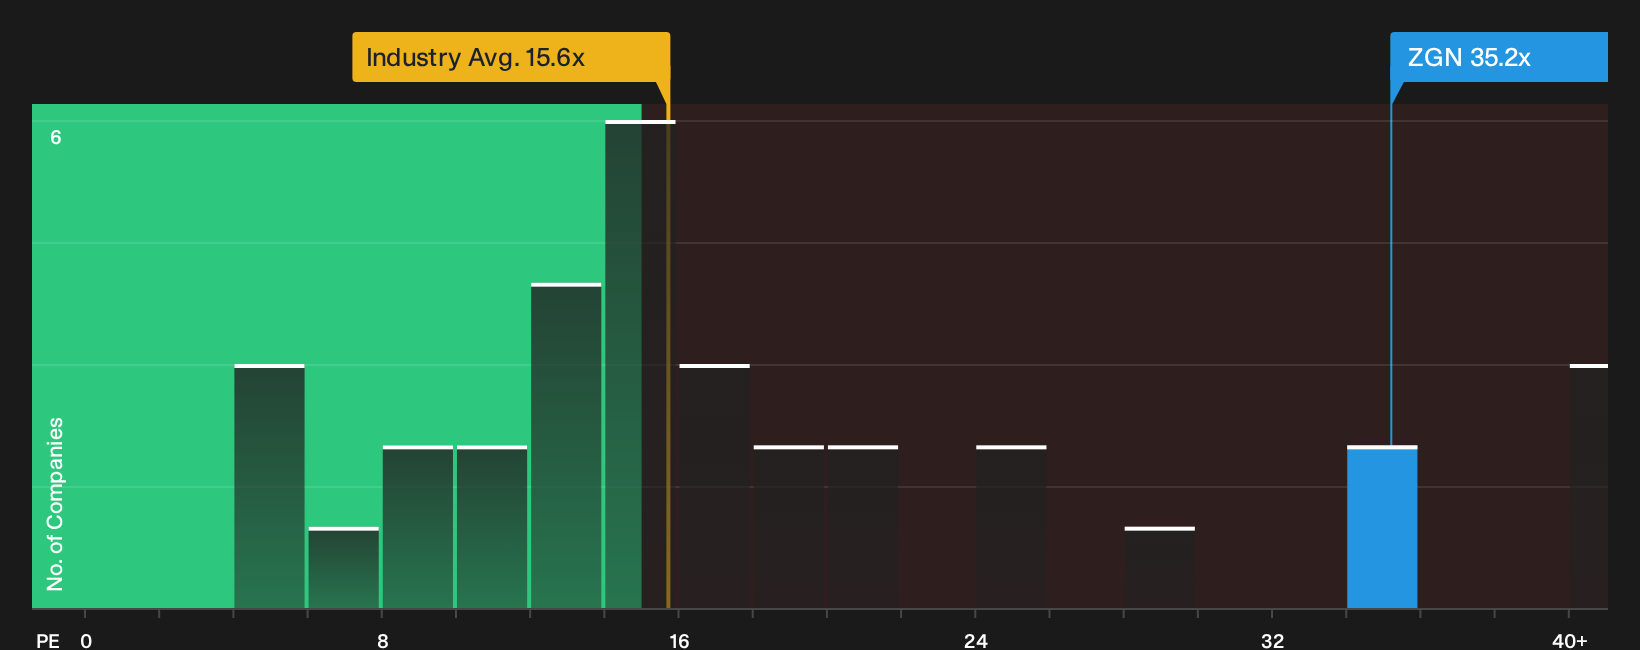
The earlier narrative leans on earnings forecasts and a premium P/E to argue Ermenegildo Zegna looks about 18.7% undervalued around $11.8. If you switch lenses to the current P/E of 35.2x, though, the picture tightens because that level sits well above peers at 20.1x and a fair ratio of 24.3x.
That gap suggests investors are already paying up for quality and execution, which can limit protection if growth assumptions slip. If the market eventually gravitates closer to the 24.3x fair ratio, how much room is really left for upside from here?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Positive or cautious on Ermenegildo Zegna after these numbers, the key is to act while the data is fresh and decide where you stand. To see what optimism is already baked into the thesis around future strengths, review the 2 key rewards
Looking for more Ermenegildo Zegna investment ideas?
If Ermenegildo Zegna is on your radar, use this moment to widen your opportunity set and pressure test your thesis against what else the market offers.
- Target acceleration potential by scanning the 33 high quality undervalued stocks that pair solid fundamentals with prices that have not yet caught up.
- Strengthen your income stream by reviewing the 6 dividend fortresses that focus on higher yields with staying power.
- Prioritise resilience by comparing Ermenegildo Zegna with the 11 resilient stocks with low risk scores designed to highlight businesses with sturdier financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com