
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Demand Stabilization Might Change The Case For Investing In Sarepta Stock (SRPT)
- Sarepta Therapeutics reported that ELEVIDYS demand has stabilized following prior safety related disruption. Management now expects second half 2026 usage to sit modestly below the first half and has also flagged upcoming multiple ascending dose data for FSHD and DM1 programs.
- The update that FSHD and DM1 trials so far show target engagement without dose limiting toxicities, together with a sirolimus study aiming to address ELEVIDYS related acute liver injury, indicates that management is working on both new potential revenue paths and risk management around its existing gene therapy.
- We will now look at how Sarepta Therapeutics' investment narrative could shift as ELEVIDYS stabilizes and key FSHD data approaches.
Contrast Sarepta Therapeutics' gene therapy risk profile with other healthcare companies by scanning 11 resilient stocks with low risk scores that focus on steadier balance sheets and more resilient fundamentals.
Sarepta Therapeutics Investment Narrative Recap
To own Sarepta Therapeutics, you need to be comfortable with a concentrated gene therapy story where ELEVIDYS funds a broader rare disease pipeline. The belief is that demand for ELEVIDYS remains durable enough to support ongoing investment, even as Sarepta works through safety concerns and complex treatment logistics that can slow recognized revenue.
The recent update that ELEVIDYS demand has stabilized, with second half 2026 slightly below the first, does not radically change that near term setup. The key near term catalyst still sits in FSHD and DM1 multiple ascending dose readouts, while the biggest current operational risk remains any renewed safety or regulatory pressure on ELEVIDYS.
The sirolimus study in non ambulatory patients is the announcement that most directly ties back to this news. It addresses acute liver injury related to ELEVIDYS and gives investors a concrete operational effort to watch around safety management and treatment continuity in gene therapy.
If that study eventually shows a cleaner safety profile, it could support steadier ELEVIDYS use and help Sarepta Therapeutics convert interest into completed infusions more reliably. Combined with the FSHD and DM1 data expected in the second half of 2026, it frames a catalyst path that is tightly linked to execution on safety and trial outcomes rather than broader market factors.
Sarepta Therapeutics' narrative cites analyst assumptions that revenues reach about US$1.4b and earnings reach US$87.3 million by 2029, from a current earnings loss of US$713.4 million. This implies a very large earnings swing higher and an annual revenue decline of 13.3% over the next 3 years.
Uncover why Sarepta Therapeutics' fair value indicates a 10% potential upside to its current price that could narrow quickly.
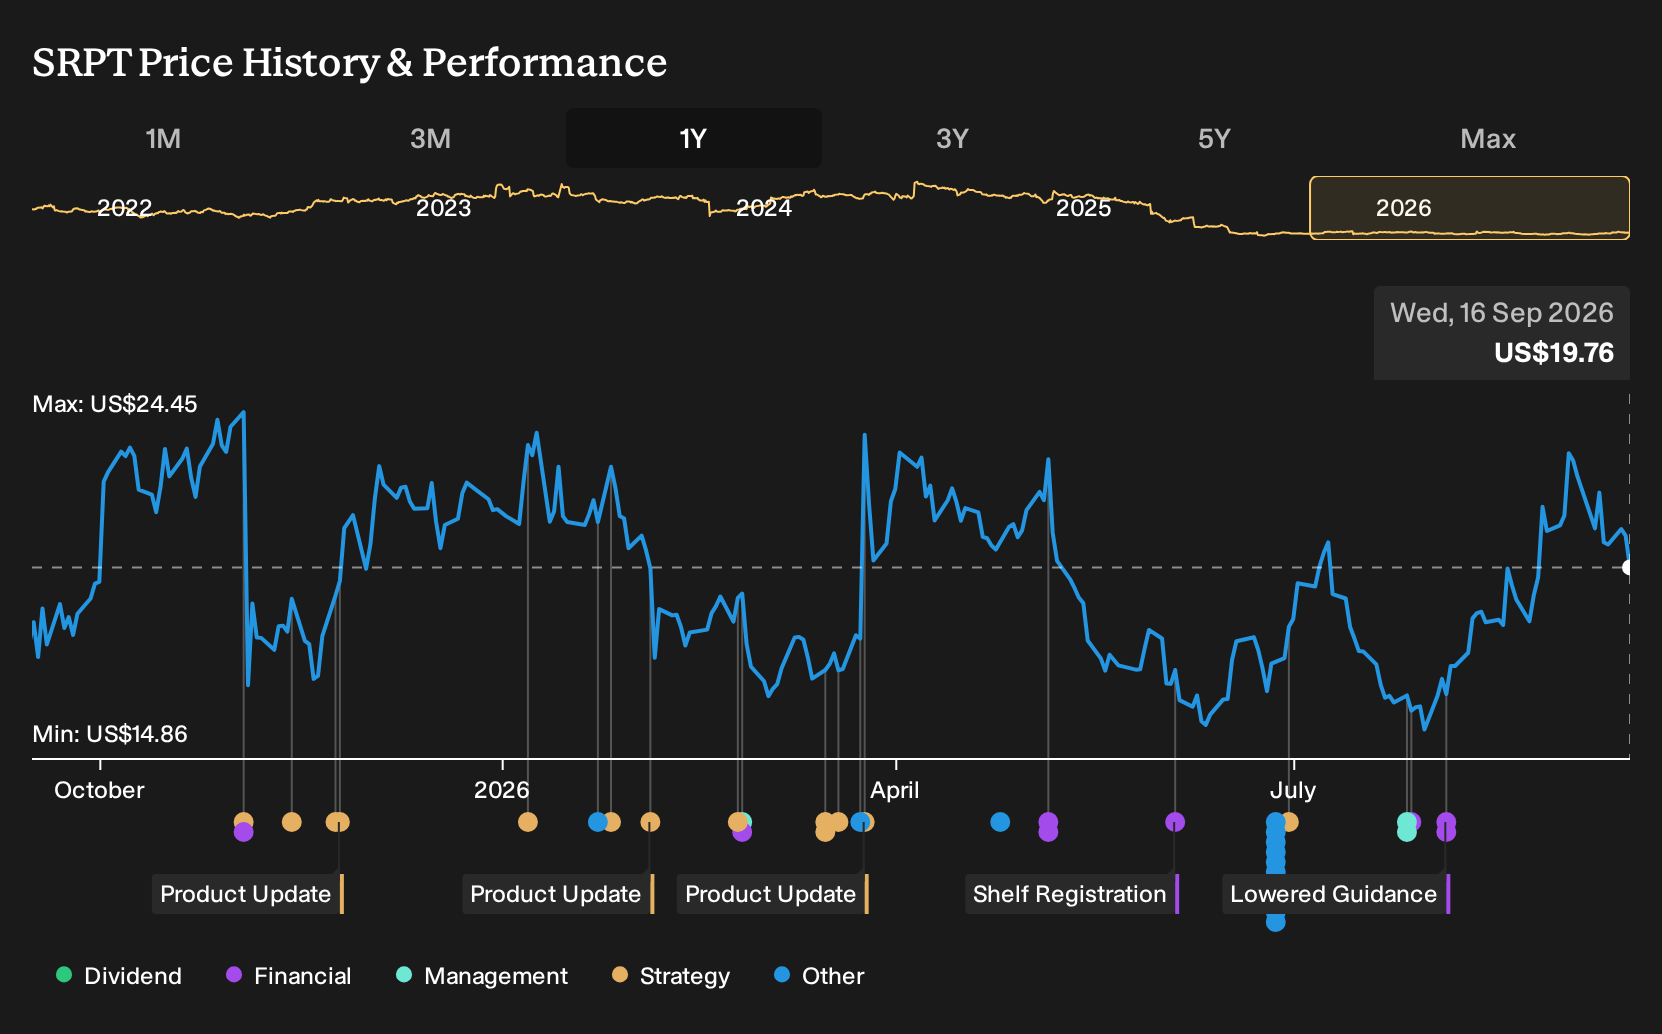
Exploring Other Perspectives
For Sarepta Therapeutics, the biggest swing factor in the more cautious narrative is regulatory pressure. The lowest analysts were already modeling a steep 36.1% annual revenue decline and only about US$569.3 million of sales by 2029, compared with US$1.4b in consensus. Those views predate this ELEVIDYS update, so use them as a reference point and explore how opinions might shift.
Explore 3 other Sarepta Therapeutics fair value estimates, including one that suggests as much as 64% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sarepta Therapeutics research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sarepta Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sarepta Therapeutics' overall financial health at a glance.
Looking For More Ideas Beyond Sarepta Therapeutics?
Once you have a view on Sarepta Therapeutics, it can help to set that thesis against other opportunities using the Simply Wall St Screener so you can see how risk, quality and potential return trade off across different businesses.
- If you want potential mispricing combined with underlying quality, scan through 33 high quality undervalued stocks that may offer stronger fundamentals at more modest valuations.
- For investors who care most about financial resilience, compare Sarepta Therapeutics with a list of solid balance sheet and fundamentals (22 results) to see which businesses better match your risk tolerance.
- If you prefer to focus on income, you can look at companies in the 6 dividend fortresses that pair higher yields with a focus on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com