
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Missile Strike Altering The Investment Case For ArcelorMittal (ENXTAM:MT)?
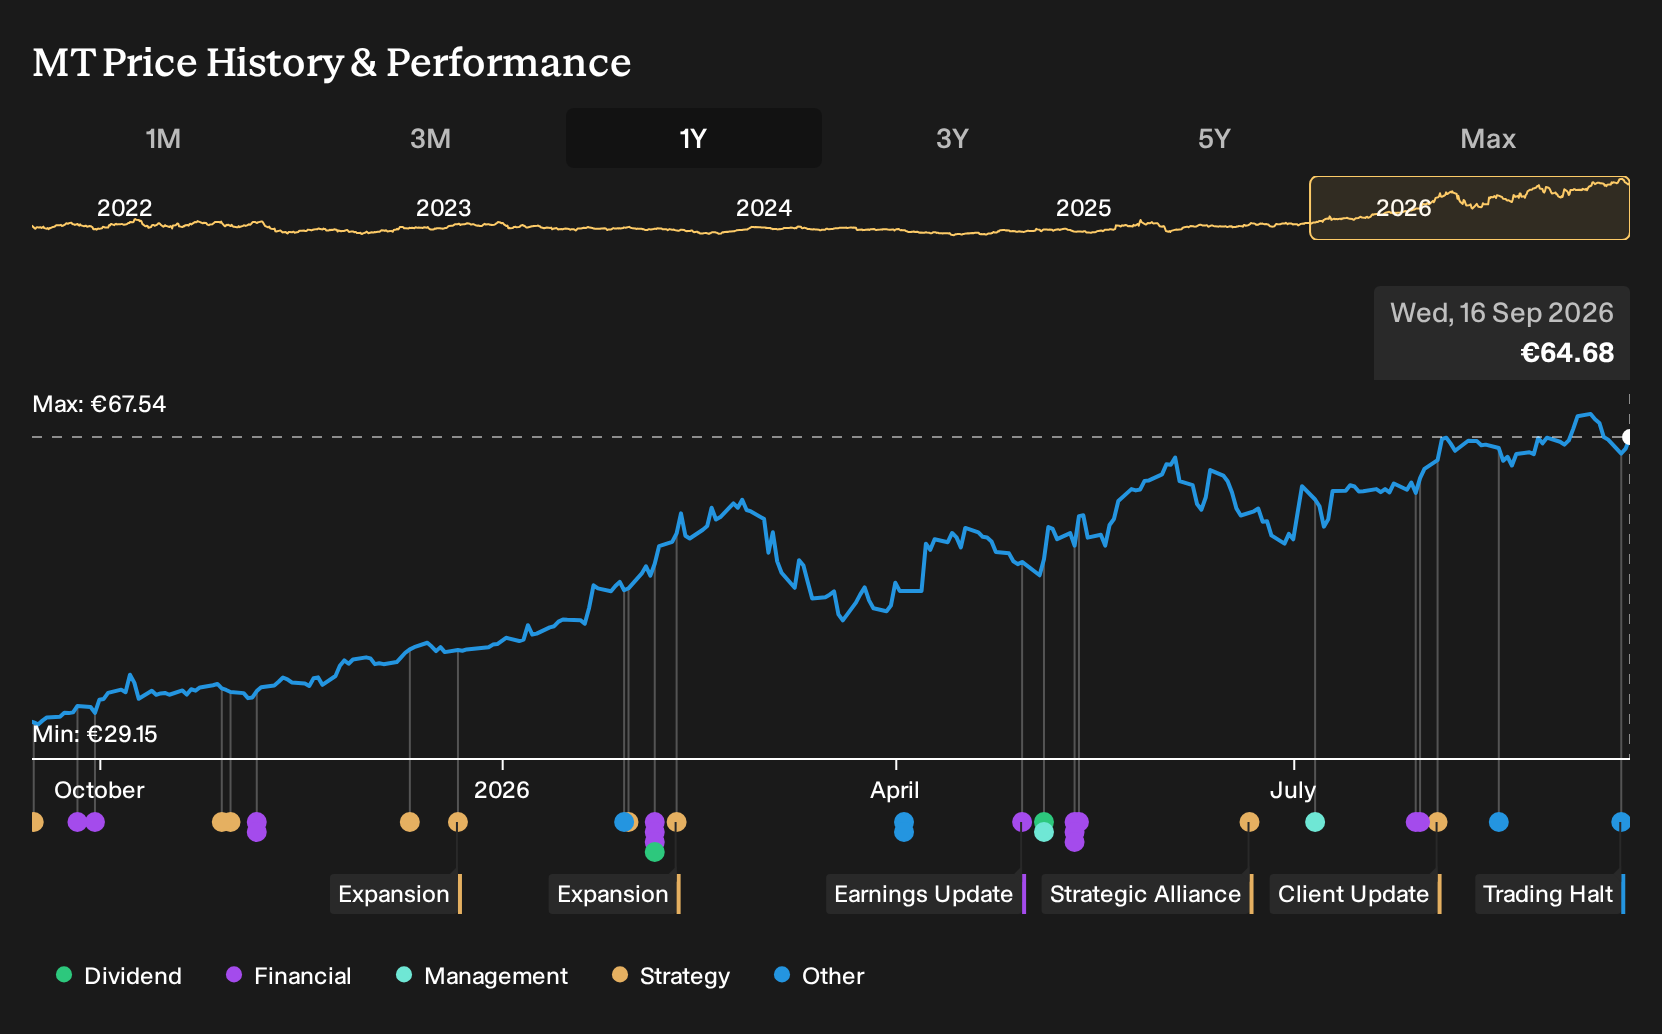
- In mid September 2026, a ballistic missile strike hit ArcelorMittal Kryvyi Rih’s ironmaking complex #1, killing two contractors, injuring two employees, and forcing a halt to primary steel production. Most other units are idled or operating at minimum output.
- The repeat strike within five weeks adds significant operational uncertainty at a major integrated site, increasing repair costs and complicating ArcelorMittal’s production planning across its wider steel and mining network.
- We will now explore how ArcelorMittal's broader investment narrative could be affected by primary steel production being halted at Kryvyi Rih.
ArcelorMittal Investment Narrative Recap
To own ArcelorMittal, you need to believe the steel and mining platform can keep turning a €48.8b market value into stronger earnings through decarbonization projects, higher value products and growth regions like India and Brazil, despite uneven demand. The Kryvyi Rih strike hits one integrated site, not the entire network, but it raises operational noise around asset reliability.
The key near term swing factor remains execution on big capex programs and major expansions while keeping cash generation and balance sheet discipline intact. The biggest risk is that heavy green steel and capacity investments collide with weaker pricing or new trade frictions, which could tighten financial headroom just as spending remains elevated.
The latest update on Kryvyi Rih is the most relevant development for that thesis. Primary steel output there is halted while damage is assessed, and other facilities are idled or at minimum levels. For a group that runs integrated steel and mining operations across several continents, the question is how flexibly it can reroute volumes and procurement around a partially offline Ukrainian asset.
This incident sits on top of existing risks around tariffs, global overcapacity and large project pipelines in Europe, India and North America. Execution on decarbonization and expansion plans still looks central to the story, but investors now also have to watch how ArcelorMittal manages security, redundancy and repair timelines at a site that has been hit twice in five weeks.
ArcelorMittal's current earnings are $1.8b and the analyst narrative points to revenue of $75.2b and earnings of $5.7b by 2029. This implies 6.2% yearly revenue growth and an earnings increase of about $3.9b from today.
Uncover why ArcelorMittal's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You are now seeing how security risk can sit alongside the usual tariff and capex worries. The most pessimistic analysts already assumed slower progress for ArcelorMittal, with revenue only reaching about $69.3b and earnings around $4.8b by 2029. Those forecasts were made before this attack, so their story may evolve further.
Explore 2 other ArcelorMittal fair value estimates, including one that suggests it could be worth just €66.61.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ArcelorMittal research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for ArcelorMittal. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ArcelorMittal's overall financial health at a glance.
Looking For More ArcelorMittal Style Investment Ideas?
If the ArcelorMittal story has you thinking about resilience, cash generation and balance sheet strength, it can help to widen the lens and see how other companies stack up on those same traits. The Simply Wall St Screener lets you filter the market by quality, risk and income characteristics so you can line up fresh ideas next to your current watchlist.
- For investors who want a cushion when conditions get rough, filter for sturdier finances with a 104 resilient stocks with low risk scores that may better handle unexpected shocks.
- If value is your priority, look for companies that combine strong fundamentals with prices that still look restrained using our hand picked 187 high quality undervalued stocks.
- For those focused on steady income, shortlist potential payers that match your yield and payout preferences through a curated 161 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com