
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is CGN Mining (SEHK:1164) Below Fair Value On Its Hang Seng Index Inclusion?
CGN Mining (SEHK:1164) has been added to the Hang Seng China Affiliated Corporations Index, a move that can reshape how index funds and institutional investors treat the uranium supplier.
Recent trading has moved the other way. CGN Mining’s 1-day share price return declined 1.41% and the 30-day share price return is down 22.98%, while the 1-year total shareholder return has fallen 26.64% but remains well ahead over three and five years.
Scan beyond CGN Mining and see how it compares with other uranium and nuclear-linked players in our curated list of 91 nuclear energy infrastructure stocks.
CGN Mining now sits in a benchmark index while its share price has been sliding. Is that gap saying more about the uranium business or about sentiment, and what does the current valuation imply?
Price-to-Earnings of 36.7x: Is it justified for CGN Mining?
CGN Mining trades on a P/E of 36.7x, well above both peers and its own estimated fair level. This suggests the current share price reflects a rich earnings expectation despite the recent pullback.
The P/E ratio compares what investors pay today for each unit of current profit. For a uranium trader like CGN Mining, this metric reflects how much the market is willing to pay for its earnings profile, including its exposure to nuclear fuel demand and its geographic spread across China, Europe and North America.
Right now, the stock trades on a P/E of 36.7x, which is materially higher than the peer average of 12.3x and the wider Asian Oil and Gas industry on 11.9x. The estimated fair P/E of 12.9x sits far below where the market is currently pricing the shares. This is a strong signal that the valuation multiple could compress if sentiment or growth expectations weaken from here.
Explore the SWS fair ratio for CGN Mining.
Result: Price-to-Earnings of 36.7x (OVERVALUED)
Still, the uranium trade is cyclical, and any pullback in contract activity or shifts in nuclear policy could quickly challenge CGN Mining’s premium valuation.
Find out about the key risks to this CGN Mining narrative.
Another view of CGN Mining’s valuation
The P/E looks expensive, yet the SWS DCF model points in the opposite direction. At around HK$2.10, CGN Mining is assessed as trading well below an estimated future cash flow value of HK$10.83. That is a very different message for anyone weighing long term potential.
Look into how the SWS DCF model arrives at its fair value.
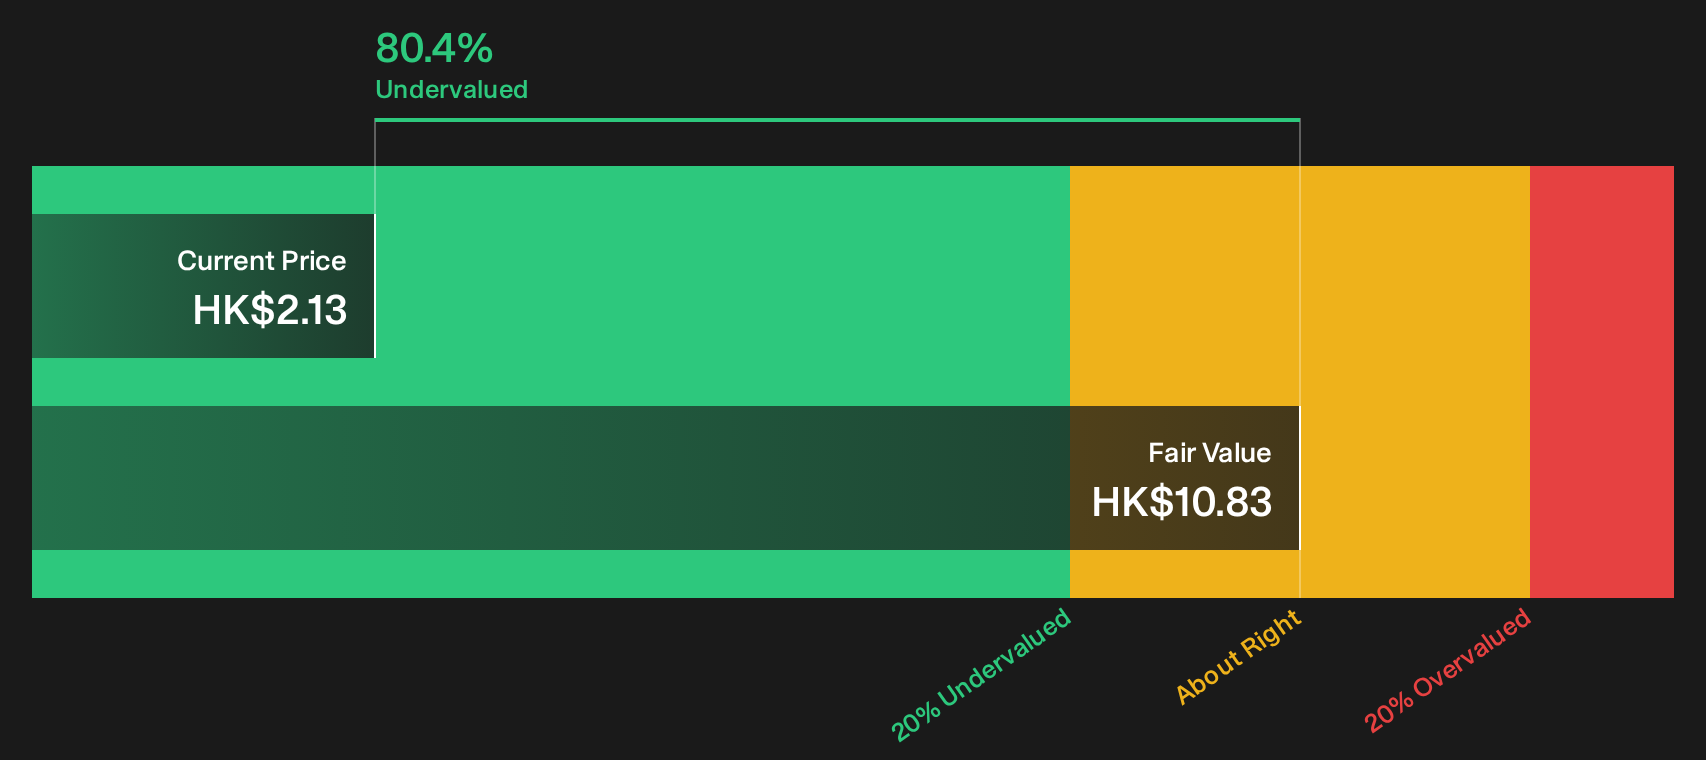
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CGN Mining for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 187 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around CGN Mining is clearly split, which is exactly when fresh data can matter most for your decision. Act quickly: stress test the bullish factors in the story, and weigh them against your own risk tolerance with the 3 key rewards.
Looking for more CGN Mining style investment ideas?
If CGN Mining has caught your attention, do not stop here. Use fresh data, compare across sectors and let curated shortlists spark your next move.
- Target value potential by scanning companies that screen as high quality and potentially mispriced through the 187 high quality undervalued stocks.
- Protect your downside by focusing on resilience and balance sheet strength filtered via the list of solid balance sheet and fundamentals (194 results).
- Spot under-the-radar opportunities early by reviewing a curated set of 619 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com