
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
AI Partnerships Might Change The Case For Investing In Tenable Stock (TENB)
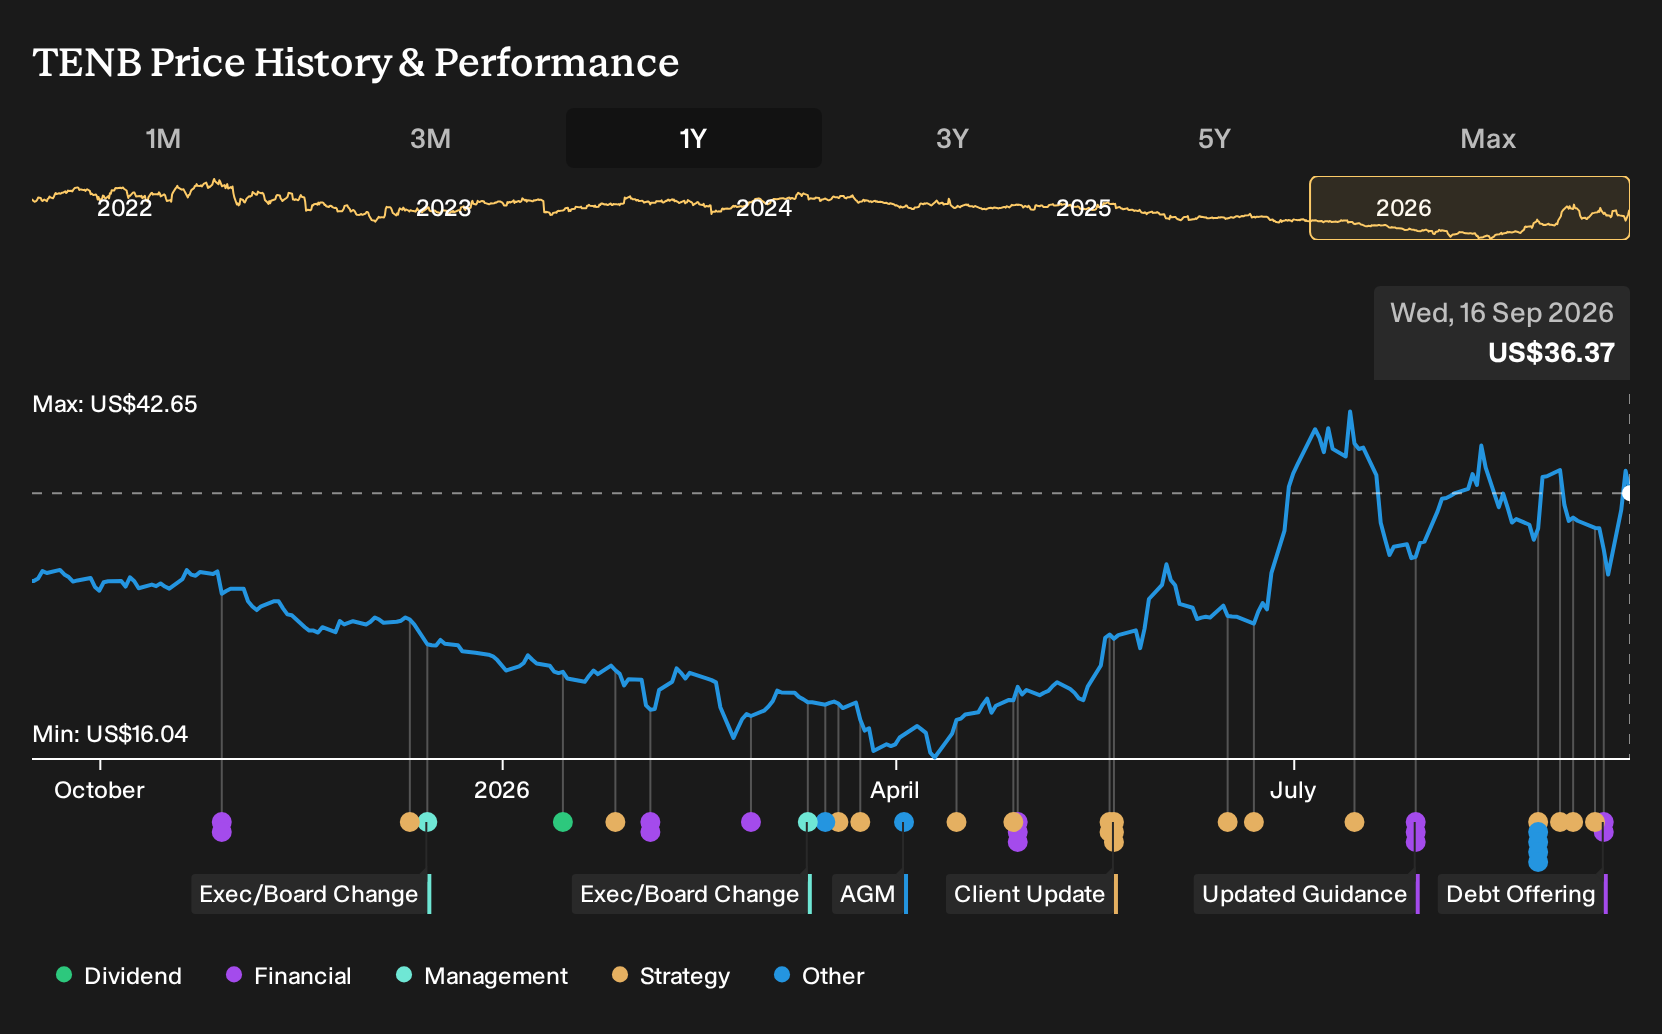
- Tenable Holdings completed a US$725 million offering of 0.25% senior unsecured convertible notes due 2031 and expanded AI-driven exposure management through new integrations with Anthropic’s Claude Mythos 5 and OpenAI’s CyberAgents Exchange.
- The fresh capital from the convertible notes and deeper AI partnerships give Tenable more room to fund product development, absorb rising R&D costs, and push its unified exposure management platform further into enterprise and government security workflows.
- Next, the focus will be on how Tenable Holdings' expanded Anthropic Claude integration could reshape its investment narrative around AI exposure management.
Scan how Tenable Holdings fits into the broader cybersecurity and AI trend by sizing it up against 60 AI infrastructure stocks that are helping secure the next wave of digital infrastructure.
Tenable Holdings Investment Narrative Recap
Tenable Holdings appeals to investors who believe unified exposure management can stay relevant as attack surfaces widen and regulations tighten. The recent US$725 million convertible note deal and fresh AI partnerships speak directly to that bet. The near term swing factor is whether Tenable One keeps driving a healthy mix of new business, larger deals, and multi year commitments.
The biggest risk is execution drag. R&D and AI spending are rising, competition from bundled platforms is intense, and public sector deal cycles can stretch. If these new AI features and acquisitions take longer to monetize, margins and earnings could come under pressure even if revenue continues to grow.
The Anthropic Claude Mythos 5 integration into Tenable One looks most relevant right now. Adversary View, powered by Claude, is designed to surface hidden attack paths and remediation steps using exposure data Tenable already collects. That fits tightly with the thesis that Tenable can sell broader platform capabilities, not just point tools.
For catalysts, the question is whether features like Adversary View and Tenable One AI Exposure help sustain Tenable Holdings' recent momentum in net dollar expansion and platform adoption. The risk side of that same coin is clear. If customers do not meaningfully adopt these AI capabilities or prefer rival platforms, Tenable could feel more pricing pressure and slower upsell into its unified exposure suite.
Tenable Holdings' narrative projects US$1.3b revenue and US$68.4 million earnings by 2029. This assumes 6.6% yearly revenue growth and an earnings increase of about 10x from US$6.7 million today.
Uncover why Tenable Holdings' fair value indicates a 3% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For Tenable Holdings, the big swing factor in the alternate narrative is R&D strain. The most cautious analysts worry that heavy AI and exposure management spending could weigh on margins for years. They were only modeling about 5.7% annual revenue growth and US$38.3 million in 2029 earnings before this US$725 million convertible deal and new Claude and OpenAI work, so their view is far more restrained. Those forecasts may shift as the impact of this funding and AI expansion becomes clearer. This is why it helps to compare several viewpoints before you decide what this story means for you.
Explore 2 other Tenable Holdings fair value estimates, including one that suggests it could be worth just $35.35.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research and going with your instincts.
- A great starting point for your Tenable Holdings research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Tenable Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tenable Holdings' overall financial health at a glance.
Looking For More Ideas Beyond Tenable Holdings?
If the Tenable Holdings story has you thinking about where to deploy capital next, a broader scan of the market can help you stress test your thesis and uncover alternatives with different risk and return profiles.
- Focus on value first by comparing Tenable Holdings with companies that combine healthy fundamentals and potentially attractive pricing through the 33 high quality undervalued stocks.
- Prefer resilience and capital preservation, especially when backing more mature businesses, by checking out the 11 resilient stocks with low risk scores that screens for sturdier balance sheets and lower risk scores.
- If you are hunting for lesser known opportunities with solid financial footing, sort through the 16 high quality undiscovered gems and see which stocks merit a place on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com