
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Garmin (GRMN) Fully Valued As Its New Drive GPS Launch Meets A Pullback?
Garmin (GRMN) just rolled out a fully redesigned Garmin Drive line, a fresh set of in-car GPS devices with ultrawide displays and app-connected features, giving investors new detail on its consumer automotive push.
Despite the new Garmin Drive launch, Garmin’s share price has recently cooled. The 30-day share price return is down about 10% after a strong 90-day gain of 18.3% and a 3-year total shareholder return above 170%. This suggests that momentum, which has been strong over time, is pausing rather than accelerating.
Scan Garmin’s GPS refresh alongside other hardware-focused opportunities by reviewing the hand-picked 11 resilient stocks with low risk scores that combine resilient balance sheets with room for the story to develop.
Garmin now trades only slightly below the average analyst target and close to one intrinsic value estimate, while the share price has just pulled back. Does that narrow gap still leave enough margin of safety?
Most Popular Narrative: 4.6% Undervalued
Garmin closed at $276.93, while the most followed narrative pegs fair value around $290.29 using an 8.02% discount rate. This implies a modest valuation gap that depends on how durable the current product momentum and margins prove to be.
The launch of the Garmin Connect+ premium service, which offers AI-based health and fitness insights, is presented as likely to support subscription-based revenue growth and improve overall margins through higher-margin services. The new vívoactive 6 smartwatch release, with advanced features like an AMOLED display and enhanced sports apps, is described as suggesting potential revenue growth in the Fitness segment, supported by demand for advanced wearables.
See why 48 investors see Garmin as 5% undervalued.
Result: Fair Value of $290.29 (UNDERVALUED)
Still, the story around Garmin can shift quickly if Marine softness persists, or if rising R&D and SG&A outpace revenue and squeeze profitability.
Find out about the key risks to this Garmin narrative.
Another View: Garmin Looks Expensive On Earnings
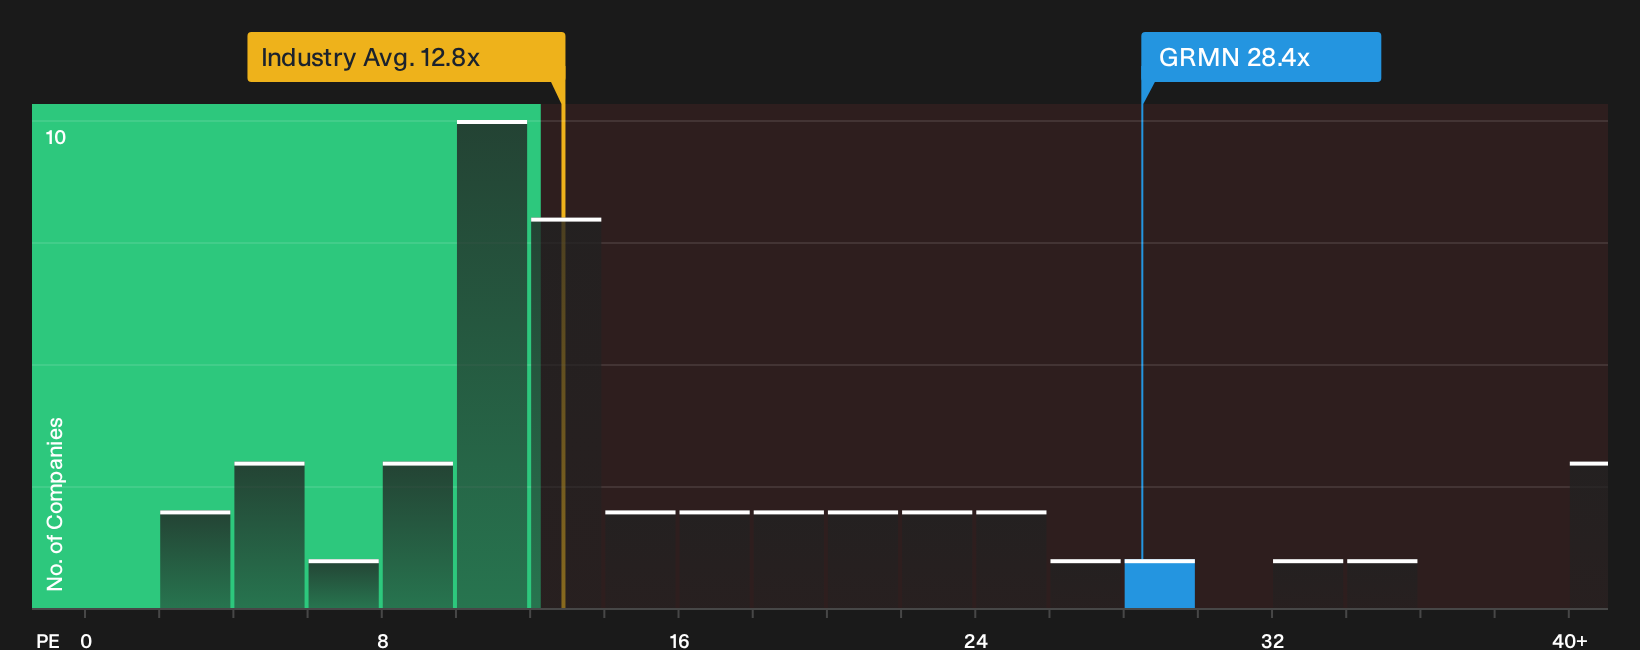
The narrative fair value for Garmin suggests a 4.6% undervaluation, yet the market is pricing the shares very differently when earnings multiples are used. The current P/E of 28.4x sits well above the US Consumer Durables industry at 12.8x and also above the peer average of 22.8x.
Our fair ratio for Garmin is 21.5x. That is a material gap, which points to valuation risk if sentiment cools or growth expectations soften. The question for you is simple. Does the quality and growth profile justify paying a premium this wide, or is patience the better option?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Garmin’s valuation and sentiment can be confusing. Move quickly, review the data first hand, and weigh both the 3 key rewards and 1 important warning sign.
Hunt For Your Next Idea Beyond Garmin
If Garmin has your attention, do not stop here. Use the Simply Wall Street Screener to quickly surface fresh ideas before the crowd does.
- Target resilient compounding potential by scanning a 33 high quality undervalued stocks that combine quality fundamentals with prices that still look reasonable.
- Lock in potential income streams by reviewing a 6 dividend fortresses built around higher-yield companies with the financial strength to keep paying investors.
- Prioritise capital protection by checking a list of solid balance sheet and fundamentals (22 results) so you can focus on businesses with sturdy finances backing their story.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com