
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kerry Properties (SEHK:683), What Is Behind The Latest Attention?
Kerry Properties (SEHK:683) has fallen about 9% over the past month, extending a decline of roughly 6% over the past 3 months. This puts recent share weakness in sharp focus for investors.
At a share price of HK$17.29, Kerry Properties has not only declined over the past week and month, but the year to date share price return is also down 15.49%, even though the 3 year total shareholder return of 62.53% and 5 year total shareholder return of 23.81% show a very different long run experience for investors.
Scan the recent weakness in Kerry Properties relative to other potential opportunities by reviewing a curated 187 high quality undervalued stocks that may also be trading away from their long term fundamentals.
Kerry Properties has scale, assets and a long trading record, yet the recent share slide raises a sharper issue. Are investors now paying a fair price for that profile, or a discount, or even a premium?
Price-to-Earnings of 24x: Is it justified?
Kerry Properties trades on a P/E of 24x while the last close sits at HK$17.29, and that leaves the stock looking expensive compared with both its peers and the wider Hong Kong real estate sector.
The P/E ratio compares what investors are paying today for each dollar of current earnings. For a property developer and asset owner like Kerry Properties, it reflects how the market weighs recent earnings growth, income from its Hong Kong and Mainland China portfolios, and expectations around the stability of that profit stream.
On one hand, the P/E of 24x is above the peer average of 22.5x, which implies investors are paying a richer price for each unit of earnings than for similar companies. On the other hand, this valuation sits below an estimated fair P/E of 29.9x, which suggests there is room for the market view to shift closer to that level if earnings delivery and growth expectations hold over time.
Compared with the wider Hong Kong Real Estate industry average P/E of 8.9x, Kerry Properties is priced far higher on earnings, which points to a very different market expectation profile than the broader sector.
Explore the SWS fair ratio for Kerry Properties.
Result: Price-to-Earnings of 24x (OVERVALUED)
Still, the narrative for Kerry Properties could be challenged if earnings soften relative to its 24x P/E, or if sentiment toward Hong Kong and Mainland China real estate weakens further.
Find out about the key risks to this Kerry Properties narrative.
Another view on Kerry Properties using cash flows
While the 24x P/E makes Kerry Properties look expensive on earnings, the SWS DCF model points the other way. It estimates a future cash flow value of about HK$13.04 per share versus the current HK$17.29 price, which screens as overvalued on this lens and raises a simple question: Which signal do you trust more, earnings or cash flows?
Look into how the SWS DCF model arrives at its fair value.
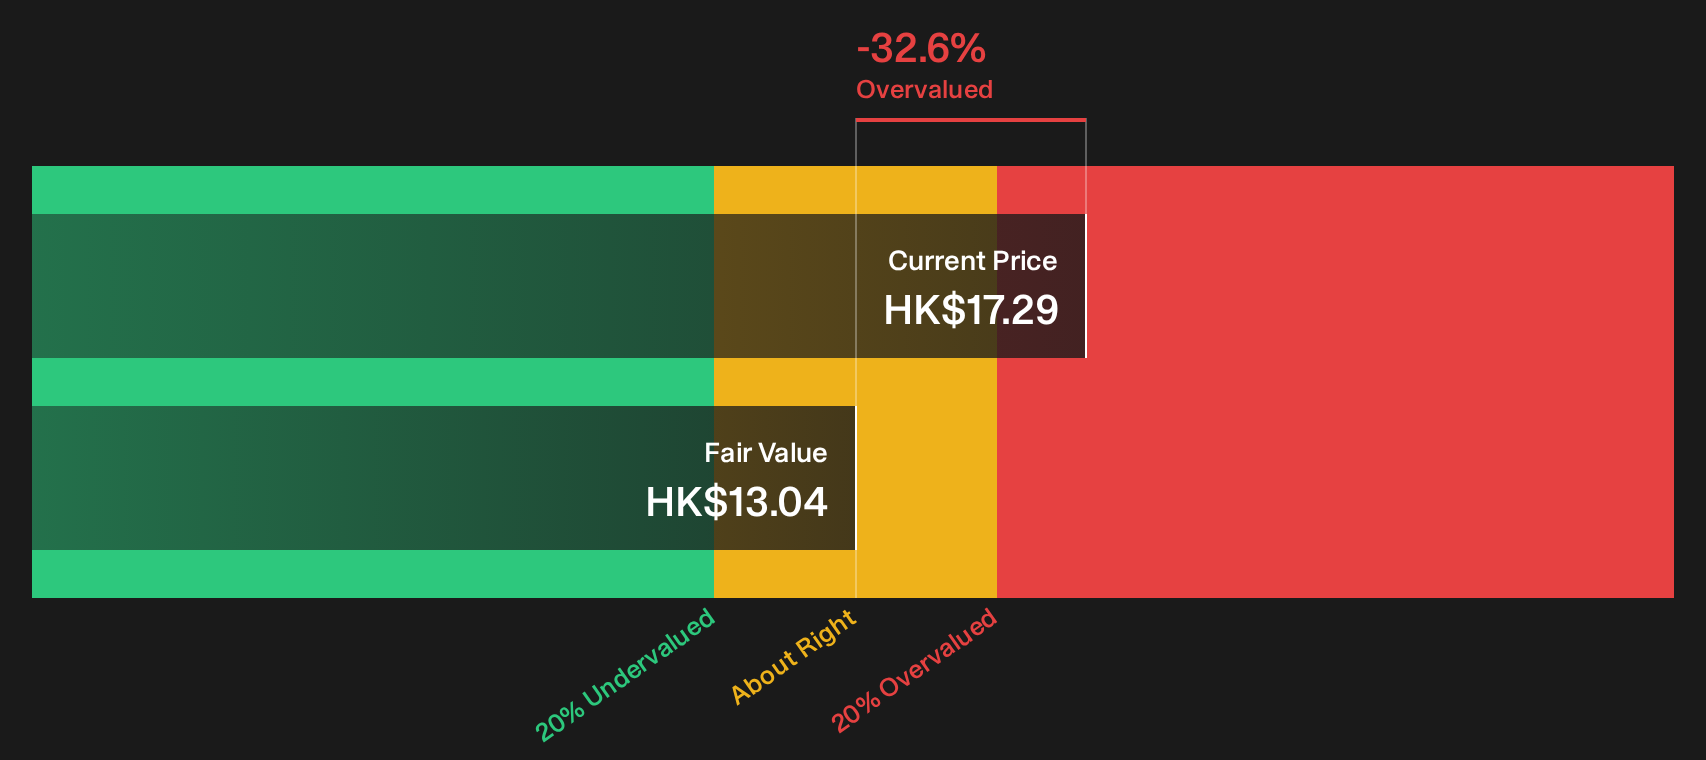
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kerry Properties for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 187 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Kerry Properties leave you torn, that is the point. Act while the data is fresh, weigh both sides, and ground your stance in the 3 key rewards and 2 important warning signs.
Looking for more Kerry Properties style investment ideas?
If Kerry Properties has sharpened your focus on valuation and risk, keep that momentum going by scanning other opportunities with the Simply Wall St stock screener.
- Target resilient balance sheets and steady fundamentals by reviewing a curated list of solid balance sheet and fundamentals (194 results) that can help you sidestep weaker candidates.
- Hunt for mispriced quality by checking a focused 187 high quality undervalued stocks that may be trading away from what their fundamentals imply.
- Zero in on potential early movers by tracking a tighter 141 elite penny stocks with strong financials that filters for stronger financial profiles in this higher risk corner of the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com